










Sahasra Electronic Solutions Limited semiconductor mix reaches 34.8%
Key highlights
- Sahasra’s semiconductor revenue rose 1,123% to Rs 31.8 crore in H1 FY27 from Rs 2.6 crore in H1 FY26.
- Semiconductors contributed 34.8% of consolidated revenue in H1 FY27, compared with 4.4% a year earlier.
- Sahasra’s Bhiwadi semiconductor facility operated at 25.5% utilisation in H1 FY27 against stated peak utilisation of 100%.
- Consolidated revenue grew 51% to Rs 91.4 crore in H1 FY27, while EBITDA margin declined to 13.3% from 17.5%.
powered by IRIS
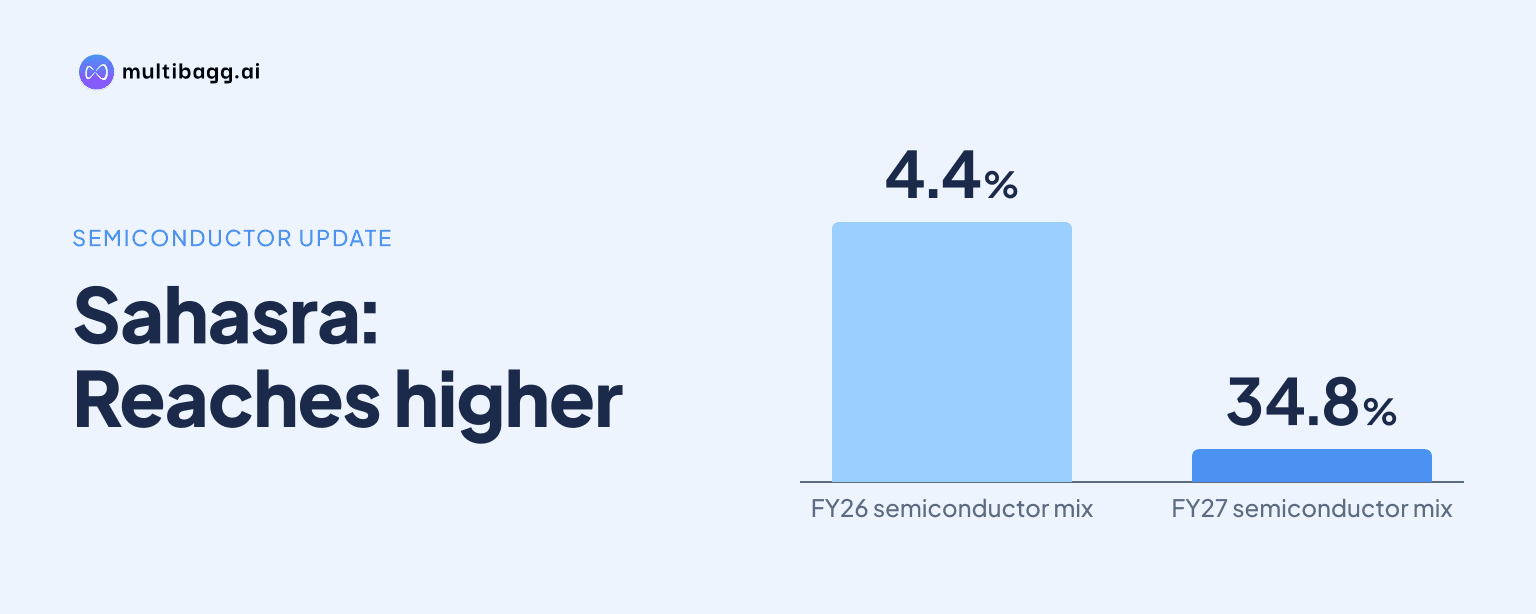
Sahasra Electronic Solutions Limited’s semiconductor revenue rose 1,123% year on year to Rs 31.8 crore in H1 FY27, lifting its share of consolidated revenue to 34.8% from 4.4% in H1 FY26. The Rs 29.2 crore increase in semiconductor revenue accounted for most of the Rs 30.8 crore rise in consolidated revenue, while its Bhiwadi semiconductor facility operated at 25.5% utilisation.
Know Sahasra Electronic Solutions inside out
Results, valuation, peers and who's buying, in one view.
How did Sahasra’s revenue mix change in H1 FY27?
Sahasra’s revenue mix changed materially in H1 FY27 because semiconductor revenue rose to Rs 31.8 crore from Rs 2.6 crore, whereas electronics manufacturing services, or EMS, remained the largest segment at Rs 48.9 crore. Consolidated revenue increased 51% to Rs 91.4 crore from Rs 60.6 crore, with semiconductor contribution rising by 30.4 percentage points to 34.8%.
EMS revenue grew 6%, or Rs 2.6 crore, but its contribution fell to 56.2% from 76.4% because semiconductor growth was much larger. Memory solutions declined 11% to Rs 8.1 crore and computer and IT accessories declined 4% to Rs 2.5 crore; the presentation reports their H1 FY27 revenue contributions at 8.8% and 0.2%, respectively.
What does the semiconductor increase represent for Sahasra?
Sahasra’s semiconductor business became its second-largest reported revenue segment in H1 FY27, at Rs 31.8 crore, ahead of memory solutions at Rs 8.1 crore and computer and IT accessories at Rs 2.5 crore. Its 1,123% year-on-year growth followed a low H1 FY26 base of Rs 2.6 crore, so the percentage increase should be read alongside the Rs 29.2 crore absolute revenue rise.
The company describes semiconductor packaging as an emerging back-end manufacturing capability, with offerings including quad flat no-leads, or QFN, dual flat no-leads, or DFN, small outline package, or SOP, and MicroSD packaging. The presentation does not provide product-wise semiconductor revenue or volumes for H1 FY27, so it does not identify which of these packaging formats generated the Rs 31.8 crore segment revenue.
Management said the semiconductor business recorded positive earnings before interest, taxes, depreciation and amortisation, or EBITDA, in H1 FY27 and expects EBITDA-level breakeven for FY27. It also said Sahasra is exploring advanced non-memory semiconductor packaging opportunities with global players, although the presentation gives no revenue target, contract value or timetable for those opportunities.
How much semiconductor capacity is Sahasra using?
Sahasra’s Bhiwadi semiconductor unit reported H1 FY27 revenue of Rs 31.8 crore against stated peak revenue of Rs 125 crore, with utilisation of 25.5% against peak utilisation of 100%. This indicates that the revenue increase occurred while the dedicated facility was operating at roughly one-quarter of its reported utilisation level.
The semiconductor site has a 6,000-square-metre area, stated annual capacity of 60 million units and 10k and 100k clean rooms. The presentation does not specify whether the 60 million-unit capacity is allocated among QFN, DFN, SOP and MicroSD products, nor does it give a planned utilisation level for the remainder of FY27.
The other two manufacturing locations reported different H1 FY27 operating levels. The Noida unit generated Rs 37.4 crore of revenue at 74.9% utilisation, compared with Rs 22.3 crore and 22.3% utilisation at the Bhiwadi electronics unit; both reported 100% peak utilisation. Sahasra’s company snapshot separately reports overall H1 FY27 capacity utilisation of 39.8% across installed capacity of 18 million units per annum.
Got a follow-up? Ask IRIS
What did the changing mix mean for Sahasra’s financial performance?
Sahasra reported consolidated revenue of Rs 91.4 crore in H1 FY27, up 51% year on year, while consolidated EBITDA rose 15% to Rs 12.2 crore. EBITDA margin fell to 13.3% from 17.5% in H1 FY26, showing that the faster semiconductor-led revenue expansion did not translate into a higher consolidated EBITDA margin during the half year.
Consolidated profit after tax, including other income, increased 42% to Rs 8.3 crore, while profit after tax margin declined to 9.0% from 9.6% in H1 FY26. These consolidated figures differ from standalone results, where revenue was Rs 59.7 crore, up 3%, and EBITDA was Rs 8.9 crore compared with Rs 9.4 crore in H1 FY26.
Management attributed H1 FY27 execution effects to material availability, customer validation and project commencement timelines. The consolidated order book stood at Rs 148.3 crore, while management said Rs 86 crore of the standalone order book was scheduled for execution in the remainder of FY27 as those constraints ease.
What are Sahasra’s next disclosed operating milestones?
Sahasra has entered the automotive supply chain after vendor approval from a leading global automotive player, while an electric-vehicle charging project covering alternating-current and direct-current solutions was under project initiation and customer approvals. The presentation does not disclose expected revenue from either development, but both form part of the company’s stated execution agenda beyond the Rs 91.4 crore reported in H1 FY27.
The company is also reassessing business plans and strategic priorities in response to policy changes under India Semiconductor Mission 2.0, according to management. Separately, the proposed amalgamation of three group companies had received Securities and Exchange Board of India and stock-exchange approvals, with National Company Law Tribunal filing as the next step; management said completion may extend beyond FY27.
Conclusion
Sahasra’s H1 FY27 results show a substantial business-mix shift: semiconductor revenue grew from Rs 2.6 crore to Rs 31.8 crore and its share of consolidated revenue rose from 4.4% to 34.8%. EMS still produced the largest segment revenue at Rs 48.9 crore, but its contribution fell by 20.2 percentage points as semiconductor packaging became a major reported sales contributor.
The next indicators are whether the Bhiwadi semiconductor unit can lift utilisation above 25.5%, whether the business achieves management’s FY27 EBITDA-level breakeven expectation, and how Rs 86 crore of scheduled standalone order-book execution progresses in the remainder of FY27. Management’s exploration of advanced non-memory packaging and the proposed amalgamation, which may extend beyond FY27, remain disclosed but unresolved developments.