










Sahasra revenue rises 51% as EBITDA margin falls to 13.3%
Key highlights
- Sahasra reported Rs 91.4 crore of consolidated H1 FY27 revenue, up 51% year on year.
- Sahasra's H1 FY27 EBITDA margin was 13.3%, down from 17.5% in H1 FY26.
- Sahasra's semiconductor revenue rose 1,123% to Rs 31.8 crore in H1 FY27.
- Sahasra reported an Rs 148.3 crore order book, with Rs 86 crore scheduled for execution during the rest of FY27.
powered by IRIS
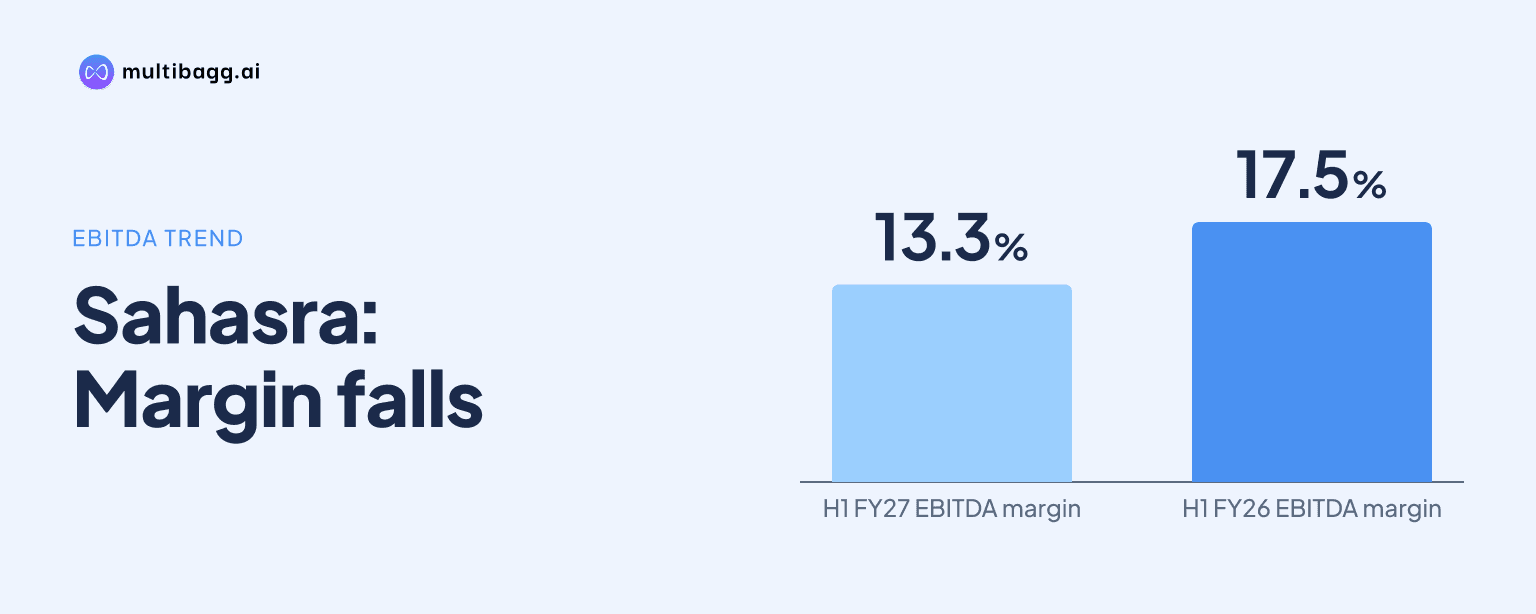
Sahasra Electronic Solutions Limited reported consolidated revenue of Rs 91.4 crore in H1 FY27, up 51% year on year, while its EBITDA margin fell to 13.3% from 17.5% in H1 FY26. EBITDA rose 15% to Rs 12.2 crore, trailing revenue growth and producing a 420-basis-point margin contraction.
Know Sahasra Electronic Solutions inside out
Results, valuation, peers and who's buying, in one view.
Why did Sahasra's EBITDA margin decline in H1 FY27?
Sahasra's reported revenue expanded faster than its EBITDA in H1 FY27, reducing the EBITDA margin to 13.3% from 17.5% in H1 FY26. Revenue from operations increased by Rs 30.8 crore, to Rs 91.4 crore from Rs 60.6 crore, whereas EBITDA grew 15% to Rs 12.2 crore. The presentation does not provide a cost bridge or another detailed explanation for the difference between revenue and EBITDA growth.
The margin movement equals 4.2 percentage points, or 420 basis points, using the two reported margins. Profit after tax, which Sahasra says includes other income, increased 42% to Rs 8.3 crore in H1 FY27. Its margin nevertheless declined to 9.0% from 9.6%, showing that profit growth also lagged the increase in consolidated revenue.
Sahasra's consolidated result was materially different from its standalone snapshot for the same period. Standalone revenue was Rs 59.7 crore, up 3% year on year, while standalone EBITDA was Rs 8.9 crore versus Rs 9.4 crore in H1 FY26. The standalone EBITDA margin declined to 14.9% from 16.1%, compared with the consolidated margin of 13.3%.
Which segments generated Sahasra's H1 FY27 revenue growth?
Sahasra's semiconductor segment generated most of the increase in consolidated revenue, with sales rising 1,123% to Rs 31.8 crore in H1 FY27 from Rs 2.6 crore in H1 FY26. The Rs 29.2 crore increase in semiconductor revenue accounted for most of the Rs 30.8 crore rise in total consolidated revenue. Management said the semiconductor business recorded positive EBITDA in H1 FY27.
Electronic manufacturing services, or EMS, remained Sahasra's largest reported segment at Rs 48.9 crore, but its revenue grew 6% from Rs 46.3 crore. Memory solutions revenue declined 11% to Rs 8.1 crore, while computer and information-technology accessories revenue fell 4% to Rs 2.5 crore. The period's revenue growth therefore came primarily from semiconductor activity rather than the established EMS segment.
Sahasra reported that semiconductor's contribution rose to 34.8% of revenue in H1 FY27 from 4.4% in H1 FY26. EMS's reported share fell to 56.2% from 76.4%, reflecting the changed mix. The presentation lists computer and IT accessories as 0.2% of H1 FY27 revenue despite showing Rs 2.5 crore of segment revenue; it does not explain this apparent mismatch with the Rs 91.4 crore consolidated total.
Got a follow-up? Ask IRIS
What do Sahasra's capital, client and workforce figures show?
Sahasra reported debtor days of 84 in H1 FY27, down from 93 days in FY26, but its cash conversion cycle increased to 147 days from 140 days. Net debt to equity remained 0.2 in both periods. Return on equity rose to 5.7% from 4.9%, while return on capital employed increased to 3.2% from 3.0%.
Sahasra's consolidated order book stood at Rs 148.3 crore in H1 FY27, alongside 159 clients and a workforce of 282. The client count increased from 119 in H1 FY26 and the workforce rose from 207. The top five clients accounted for 63.6% of revenue, up from 62.0%, while repeat business declined to 88.4% from 91.9%.
The disclosed measures show different movements across collection and operating-cycle indicators. Debtor days improved by nine days against FY26, but the cash conversion cycle extended by seven days. The Rs 148.3 crore order book provides a stated pipeline measure, while the 63.6% contribution from the top five clients shows the degree of reported revenue concentration.
What is Sahasra management expecting for H2 FY27?
Management expects stronger H2 FY27 standalone performance as material availability, customer validation and project commencement constraints ease. It said Rs 86 crore of order book is scheduled for execution during the remainder of FY27. These three execution factors affected H1 FY27 delivery, according to the company's business update.
Management expects the semiconductor business to reach EBITDA-level breakeven in FY27 after reporting positive EBITDA in H1 FY27. Sahasra is also exploring advanced non-memory semiconductor packaging opportunities with global players to diversify the portfolio. The presentation does not disclose the H1 FY27 semiconductor EBITDA amount or a revenue target for the packaging opportunities.
Sahasra said it entered the automotive supply chain after receiving vendor approval from a leading global automotive player. It also secured an electric-vehicle charging project covering alternating-current and direct-current solutions, although this project remains under initiation and customer approvals. Neither the automotive approval nor the charging project carries a disclosed revenue value or execution date.
What is the status of Sahasra's group-company amalgamation?
Sahasra has received Securities and Exchange Board of India and stock-exchange approvals for the proposed amalgamation of subsidiaries with the listed entity. The next stated step is a filing with the National Company Law Tribunal, or NCLT. Management said completion of the amalgamation of three group companies may extend beyond FY27 because it remains subject to NCLT proceedings and regulatory approvals.
The promoters established UltraMax Sahasra Energy Pvt. Ltd. with a 60:40 ownership structure and Sahasra Asetronics Pvt. Ltd. with a 55:45 structure. They intend to integrate their respective joint-venture stakes into the listed entity after amalgamation, subject to the required approvals and processes. Sahasra is also reassessing business plans and strategic priorities in response to policy changes under ISM 2.0.
Conclusion
Sahasra's H1 FY27 consolidated performance combined a 51% increase in revenue to Rs 91.4 crore with slower 15% EBITDA growth to Rs 12.2 crore, resulting in a 13.3% margin. Semiconductor revenue rose Rs 29.2 crore year on year to Rs 31.8 crore, changing the mix as EMS grew 6% and memory solutions declined 11%.
The next disclosed markers are execution of Rs 86 crore of order book during the remainder of FY27, management's expectation of semiconductor EBITDA-level breakeven in FY27, and the NCLT filing for the proposed amalgamation. Management has also said the amalgamation may extend beyond FY27 and that H2 standalone performance depends on easing material, validation and project-start constraints.