










ANUP order book reaches Rs 941 crore, Rs 390 crore for FY28
Key highlights
- ANUP reported a Rs 941 crore pending order book, including letters of intent, at September 30, 2026.
- About Rs 390 crore of ANUP's pending order book is booked for FY28.
- ANUP said its order book was 67% domestic business and 33% exports.
- ANUP disclosed a Rs 1,200 crore enquiry pipeline across FY27 and FY28.
powered by IRIS
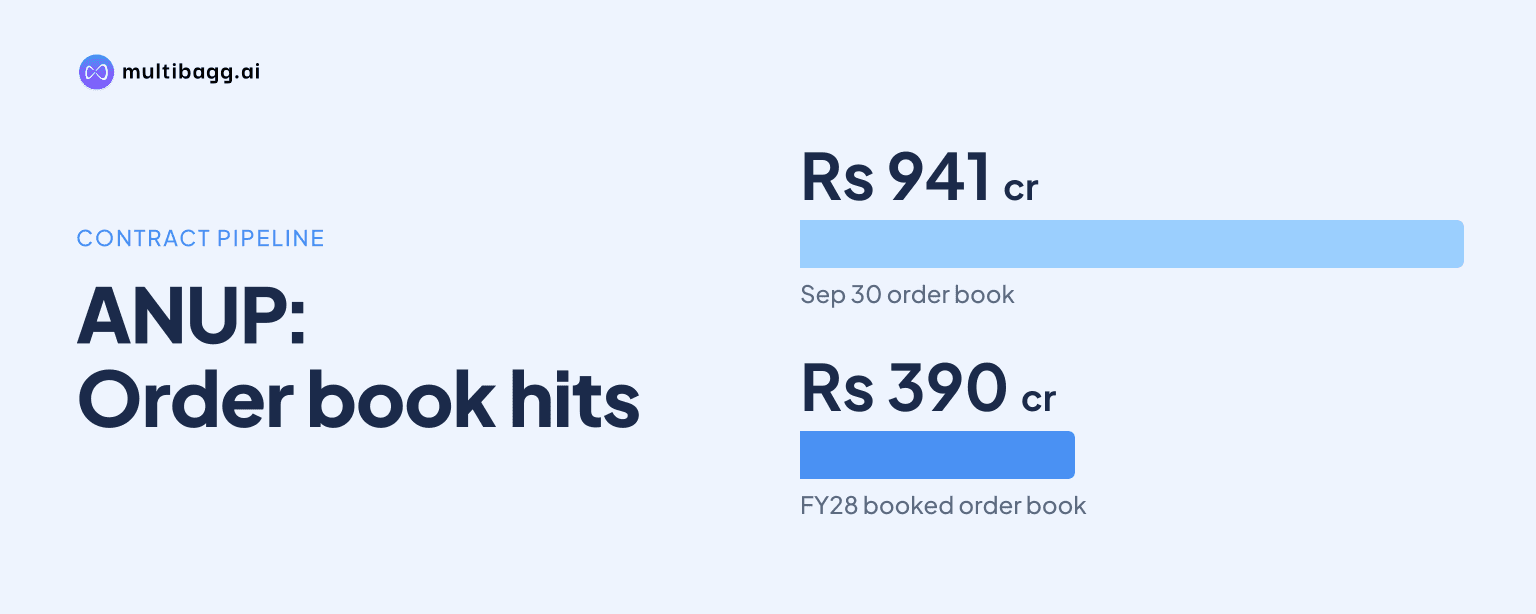
The Anup Engineering Limited reported a pending order book of Rs 941 crore, including letters of intent, at September 30, 2026, with about Rs 390 crore booked for FY28. ANUP disclosed the position with its November 6, 2026 results, alongside H1 FY27 revenue of Rs 308 crore and a Rs 1,200 crore enquiry pipeline across FY27 and FY28.
Know The Anup Engineering inside out
Results, valuation, peers and who's buying, in one view.
How much of ANUP's order book is booked for FY28?
ANUP said about Rs 390 crore of its Rs 941 crore pending order book, including letters of intent (LOIs), is booked for FY28. The company made the disclosure in its FY27 outlook following results for the quarter and half year ended September 30, 2026.
The remaining approximately Rs 551 crore of the pending order book was not allocated to a specific financial year in the release. ANUP did not provide a quarter-by-quarter execution plan, project names, customer details or a split between firm orders and LOIs, so the disclosed Rs 390 crore should not be read as a revenue forecast.
The FY28-booked component was about Rs 82 crore higher than ANUP's H1 FY27 revenue of Rs 308 crore. These are different measures: revenue reflects work recognised in the six months ended September 30, 2026, while the order book represents pending work that includes LOIs.
What is the domestic and export split of ANUP's pending work?
ANUP said domestic business accounted for 67% of the Rs 941 crore order book and exports accounted for 33%. Management said this mix suggested a pickup in domestic demand, although the release did not disclose comparable prior-period geographic shares.
Applying the disclosed percentages to the Rs 941 crore total indicates domestic work of about Rs 630 crore and export work of about Rs 311 crore. These are calculated amounts rather than figures separately reported by ANUP, and the company did not identify export markets, customers or delivery dates.
ANUP reported a business mix led by Oil & Gas at 57%, followed by other sectors at 31% and Power & Energy at 12%. It serves process industries including Petrochemicals, liquefied natural gas, hydrogen, fertilisers, chemicals, pharmaceuticals, power, water, paper and pulp, and aerospace.
The product mix was led by Reactors & Vessels at 66%, while Heat Exchangers accounted for 27% and Rotary Equipment & Silos for 7%. The filing did not provide order values, margins or execution periods for these sector and product categories.
How does ANUP's pending order book compare with recent revenue?
ANUP's Rs 941 crore pending order book was more than three times its Rs 308 crore H1 FY27 revenue. The comparison shows that pending work exceeded revenue recognised during the six months ended September 30, 2026, but the release does not specify how much of the order book will convert into FY27 revenue.
Revenue from operations rose sequentially to Rs 182 crore in Q2 FY27 from Rs 125 crore in Q1 FY27, a 46% increase. It was nonetheless 22% lower than Rs 232 crore in Q2 FY26, which ANUP linked to a subdued order environment over the past year amid geopolitical disruptions.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, were Rs 18 crore in Q2 FY27, compared with Rs 10 crore in Q1 FY27 and Rs 52 crore in Q2 FY26. EBITDA margin improved to 9.6% from 7.6% sequentially, while remaining below 22.2% a year earlier.
Got a follow-up? Ask IRIS
What could affect ANUP's execution and profitability?
ANUP said sub-optimal revenue levels in Q2 and H1 FY27 caused under-absorption of fixed costs, affecting EBITDA margins. The company also said geopolitical tensions contributed to an approximately 6% increase in raw-material costs, creating an additional profitability headwind.
Management said gross margins had seen only a modest impact from higher raw-material costs, but did not disclose a gross-margin percentage for Q2 or H1 FY27. It is prioritising stability, consolidation and stronger risk management amid geopolitical volatility, without giving revenue, margin or delivery-time guidance.
ANUP said it had proactively realigned and debottlenecked operations during the period of lower revenue. The company said these initiatives strengthened its execution platform, but did not quantify capacity added, capital expenditure, output improvement or the effect on the Rs 941 crore pending order book.
The release also said ANUP began executing a patented Clean Energy Storage solution for a new end-user category with a European technology partner. A repeat order was cited as evidence of scalability and long-term potential, although no value, timing or order-book inclusion was disclosed for either order.
What opportunities does ANUP identify beyond the booked order book?
ANUP disclosed an enquiry pipeline of Rs 1,200 crore across FY27 and FY28. Management said the pipeline provides visibility for order-book build-up, but enquiries are not booked orders and the release did not state a conversion rate, likely timing or value by end market.
Management also said large thermal power projects are in prospect and that the segment is poised for growth for at least three years. ANUP said its presence in thermal power creates an opportunity, while Power & Energy represented 12% of its reported business mix; it did not disclose tender values, project numbers or an order-win target.
ANUP plans to scale up its Technical Services vertical with a focus on improving overall profitability. The filing does not disclose a spending commitment, timetable, revenue target or margin target for that plan.
The company therefore distinguishes between Rs 941 crore of pending work, including LOIs, and Rs 1,200 crore of enquiries across FY27 and FY28. Only about Rs 390 crore of the pending order book was explicitly identified as booked for FY28.
Conclusion
ANUP's September 30, 2026 disclosure provides visibility into both the size and timing of its pending work: Rs 941 crore including LOIs, with about Rs 390 crore booked for FY28. The order base was 67% domestic and 33% export, while Q2 FY27 revenue recovered 46% sequentially to Rs 182 crore despite remaining below the Rs 232 crore reported a year earlier.
The next disclosed factors to watch are conversion of the Rs 1,200 crore enquiry pipeline, execution of the about Rs 390 crore booked for FY28, and the effect of the approximately 6% raw-material cost increase on profitability. Management's plans to expand Technical Services and pursue thermal power opportunities are also relevant, though the release sets no financial target or timetable for either initiative.