










ANUP Q2 revenue gains 46%, stays 22% below prior year
Key highlights
- ANUP reported Q2 FY27 revenue of Rs 182 crore, up 46% from Rs 125 crore in Q1 FY27.
- Q2 FY27 EBITDA was Rs 18 crore and EBITDA margin improved to 9.6% from 7.6% sequentially.
- Q2 FY27 revenue was 22% below Rs 232 crore in Q2 FY26, while EBITDA was 66% below Rs 52 crore.
- ANUP reported an order book of Rs 941 crore, including approximately Rs 390 crore booked for FY28.
powered by IRIS
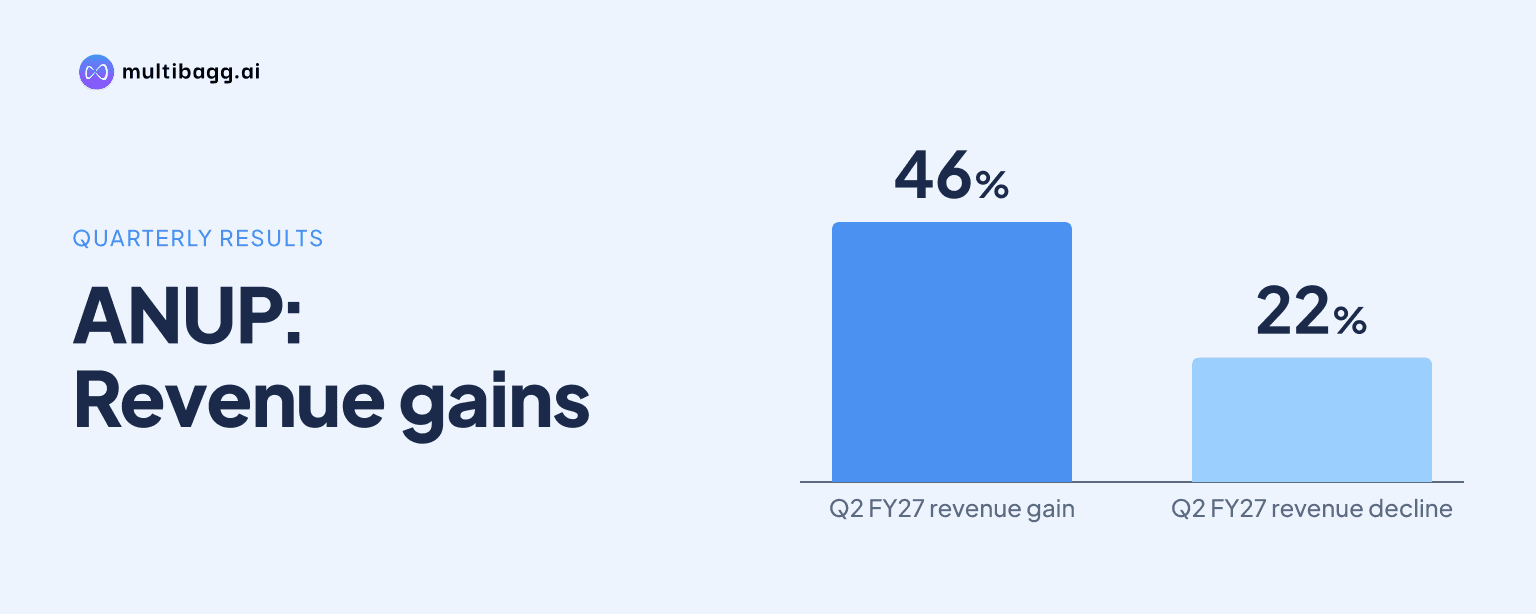
The Anup Engineering Limited reported consolidated Q2 FY27 revenue of Rs 182 crore, up 46% from Q1 FY27 but 22% below Q2 FY26, while EBITDA stood at Rs 18 crore and margin improved to 9.6% from 7.6% sequentially. The result reflects better quarter-on-quarter execution but lower revenue and profitability than a year earlier.
Know The Anup Engineering inside out
Results, valuation, peers and who's buying, in one view.
What drove ANUP's Q2 FY27 revenue recovery?
ANUP's Q2 FY27 revenue increased to Rs 182 crore from Rs 125 crore in Q1 FY27, a 46% quarter-on-quarter rise. Management said a subdued order environment caused by geopolitical disruptions over the past year had reduced revenue levels, while giving the company time to realign and debottleneck its operations.
The sequential recovery did not return revenue to the prior-year level. Q2 FY27 revenue was Rs 50 crore below Rs 232 crore in Q2 FY26, matching the disclosed 22% year-on-year decline, while H1 FY27 revenue was Rs 308 crore. Management said the operational initiatives strengthened ANUP's execution platform for opportunities represented by its order book.
Why was ANUP's Q2 FY27 EBITDA below last year?
ANUP reported Q2 FY27 EBITDA of Rs 18 crore, up 84% from Rs 10 crore in Q1 FY27 but 66% below Rs 52 crore in Q2 FY26. H1 FY27 EBITDA was Rs 27 crore. Management attributed the year-on-year profitability gap partly to lower revenue and the resulting under-absorption of fixed costs during Q2 and H1 FY27.
ANUP's EBITDA margin rose 200 basis points, with one basis point equal to one-hundredth of a percentage point, from 7.6% in Q1 FY27 to 9.6% in Q2 FY27. The margin remained below 22.2% in Q2 FY26. Management also said geopolitical tensions had contributed to an approximately 6% increase in raw-material costs, although gross margins saw only a modest effect.
What does ANUP's order book show about future work?
ANUP reported a pending order book, including letters of intent, of Rs 941 crore in its November 6, 2026 release. Approximately Rs 390 crore of that order book is booked for FY28, so the disclosed order position extends beyond FY27. Management described the order book as healthy despite the earlier geopolitical disruption to the order environment.
ANUP's order book comprised 67% domestic business and 33% exports, a split management said suggested a pickup in domestic demand. The company also reported an enquiry pipeline of Rs 1,200 crore across FY27 and FY28. That pipeline is separate from the Rs 941 crore order book, and the release did not disclose a conversion rate, expected timing or value of orders that may result.
Got a follow-up? Ask IRIS
Which sectors and products make up ANUP's business mix?
ANUP's disclosed sector mix was led by Oil & Gas at 57%, followed by Other sectors at 31% and Power & Energy at 12%. The company serves industries including Oil & Gas, Petrochemicals, liquefied natural gas, liquefied petroleum gas, Hydrogen, fertilisers, chemicals, pharmaceuticals, power, water, paper and pulp, and aerospace.
Reactors & Vessels formed 66% of ANUP's reported product mix, compared with 27% for Heat Exchangers and 7% for Rotary Equipment & Silos. ANUP also began executing a patented Clean Energy Storage solution for a new end-user category with a European technology partner. Management said a repeat order supported the solution's scalability and long-term potential, but did not disclose its value or contribution to Q2 FY27 revenue.
What plans has ANUP disclosed for FY27 and beyond?
ANUP plans to scale up its Technical Services vertical, with management identifying improved overall profitability as its focus. Management also said large thermal-power projects could support segment growth for at least three years and that ANUP's existing presence provides an opportunity. The release did not provide revenue, order-intake or profitability targets for either Technical Services or thermal power.
ANUP said it is prioritising stability, consolidation and stronger risk management amid heightened geopolitical volatility. That approach follows the approximately 6% increase in raw-material costs reported for Q2 and H1 FY27, as well as the decline in quarterly revenue from Rs 232 crore in Q2 FY26 to Rs 182 crore in Q2 FY27. Execution of the Rs 941 crore order book is the disclosed base for assessing that plan.
Conclusion
ANUP delivered a sequential improvement in Q2 FY27, with revenue rising Rs 57 crore from Rs 125 crore in Q1 FY27 to Rs 182 crore and EBITDA increasing Rs 8 crore from Rs 10 crore to Rs 18 crore. Yet revenue remained Rs 50 crore lower than Q2 FY26 and EBITDA was Rs 34 crore lower, while the 9.6% EBITDA margin remained below the prior-year 22.2% level.
The next disclosed markers are execution of the Rs 941 crore order book, including about Rs 390 crore booked for FY28, and development of the Rs 1,200 crore enquiry pipeline across FY27 and FY28. Management's planned expansion of Technical Services, work on Clean Energy Storage with its European partner, and thermal-power opportunities identified for at least three years will also be areas to watch.