










Apsis Aerocom Unit II adds 15 machines, ₹15 crore outlook
Key highlights
- Apsis Aerocom commissioned Unit II on 14 August 2026 with 15 machines and 20,000 square feet.
- Apsis Aerocom had 33 CNC machines and 125 employees across both units as of 30 September 2026.
- Apsis Aerocom expects about Rs 15 crore this year from newly developed parts across Unit I and Unit II.
- Apsis Aerocom reported H1 FY27 revenue of Rs 21.17 crore, up 55.1% year on year.
powered by IRIS
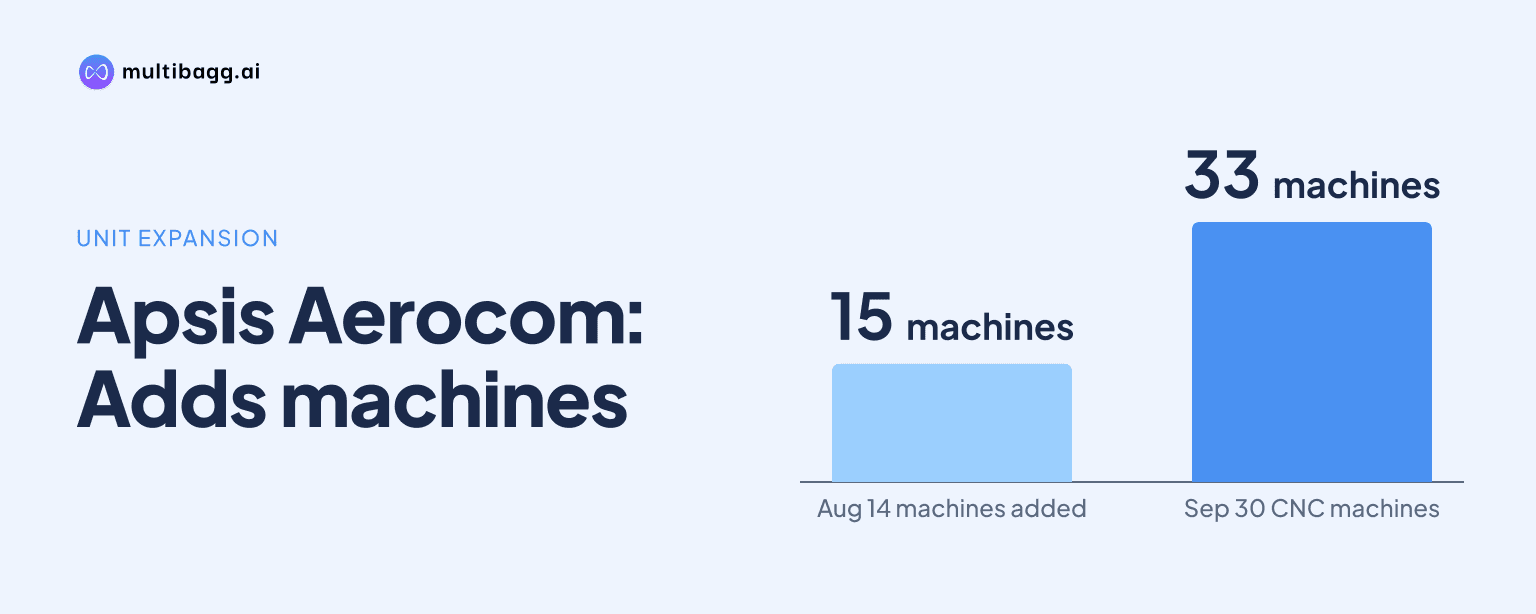
Apsis Aerocom Limited commissioned Unit II on 14 August 2026 with 15 machines and expects about Rs 15 crore from newly developed parts this year across both units. As of 30 September 2026, the addition brought its installed base to 33 computer numerical control (CNC) machines and its operational area to 28,500 square feet.
Know Apsis Aerocom inside out
Results, valuation, peers and who's buying, in one view.
Where is Apsis Aerocom’s Unit II and what was commissioned?
Apsis Aerocom’s Unit II is located at Hitech Defence & Aerospace Park and was inaugurated on 14 August 2026 with 15 machines. The facility has 20,000 square feet of space and employed more than 45 people as of 30 September 2026, according to the H1 FY27, or first half of fiscal year 2027, presentation.
The commissioning followed an H1 FY27 capital-expenditure programme of Rs 23.3 crore, including advances, of which Rs 13.3 crore was gross new fixed assets. The presentation does not assign the full H1 spend exclusively to Unit II, but identifies the August inauguration as a key event during the half-year.
How does Unit II change Apsis Aerocom’s manufacturing capacity?
Unit II increased Apsis Aerocom’s CNC-machine count to 33 across its two operating sites as of 30 September 2026. Unit I had 18 machines and 8,500 square feet of operational area, while Unit II had 15 machines and 20,000 square feet, taking the combined footprint to 28,500 square feet.
Apsis Aerocom says Unit II includes advanced turning, turn-mill, multitasking, and four- and five-axis machines. Its workforce reached 125 people across the two units, while Unit II accounted for the larger share of operational space despite having fewer machines than Unit I.
Apsis Aerocom also reports a Systems, Applications and Products (SAP)-connected shop floor, machine monitoring and digital traceability. The presentation does not disclose machine utilisation, output per machine, or a date for Unit II to reach full utilisation.
What revenue does Apsis Aerocom expect from its new-parts pipeline?
Apsis Aerocom expects about Rs 15 crore this year from newly developed parts moving into production across Unit I and Unit II. Management says it developed about 250 new parts last year, of which about 140 are now in production, linking the revenue expectation to parts that have converted from development into manufacturing orders.
The remaining pipeline includes more than 100 parts that Apsis Aerocom expects to convert into production orders in FY27 and FY28. This is a forward-looking expectation, not reported revenue, and the presentation does not split the expected Rs 15 crore by unit, customer, end market or part programme.
The disclosed figures show that about 140 of roughly 250 parts developed last year had reached production by the presentation date, while more than 100 remained for possible conversion during FY27-FY28. Apsis Aerocom also added one new customer during H1 FY27, but does not identify it or link it to the new-parts programme.
Got a follow-up? Ask IRIS
What financial context surrounds Apsis Aerocom’s expansion?
Apsis Aerocom reported H1 FY27 revenue of Rs 21.17 crore, up 55.1% from Rs 13.65 crore in H1 FY26, while earnings before interest, tax, depreciation and amortisation (EBITDA) rose 35.7% to Rs 6.52 crore. Management said defence revenue rose 56% and healthcare revenue was nearly three times the prior-year level, without disclosing segment revenue amounts.
Profit after tax increased 21.4% to Rs 3.97 crore, but its margin declined to 18.7% from 23.9% in H1 FY26. EBITDA margin similarly moved to 30.8% from 35.2%; Apsis Aerocom attributes the change to higher material intensity and Unit II running costs ahead of full utilisation.
Material cost, including inventory changes, represented 37.5% of H1 FY27 revenue versus 33.6% in H1 FY26, while other expenses rose to 12.4% from 10.7%. Management says margins are expected to be supported as Unit II utilisation rises through H2 FY27, but gives no utilisation percentage or margin target.
How does the order book relate to Apsis Aerocom’s FY27 plan?
Apsis Aerocom reported an order book of Rs 31.8 crore, equal to 1.5 times H1 FY27 revenue of Rs 21.17 crore. The Managing Director said this order book provides visibility for the rest of the year while reiterating management’s FY27 revenue target of about Rs 48 crore.
The Rs 48 crore target is above the Rs 21.17 crore reported in the first half, leaving the second half material to the full-year outcome. The presentation does not disclose the order book’s timing, cancellation terms, segment mix or the portion scheduled for Unit II.
Apsis Aerocom also reported net worth of Rs 52.9 crore as of H1 FY27, up 8.2% from Rs 48.9 crore in March 2026. Net cash was Rs 11.6 crore and the debt-to-equity ratio was 0.07, alongside the Rs 23.3 crore H1 capital-expenditure figure including advances.
Conclusion
Unit II adds 15 machines, 20,000 square feet and more than 45 employees to Apsis Aerocom’s operating base, taking the company to 33 CNC machines and 28,500 square feet as of 30 September 2026. The expansion coincided with H1 FY27 revenue growth of 55.1% to Rs 21.17 crore, although EBITDA margin declined by 4.4 percentage points to 30.8% as material costs and Unit II running costs increased.
The next disclosed milestones are conversion of more than 100 additional parts into production during FY27-FY28, rising Unit II utilisation through H2 FY27, and management’s about Rs 48 crore FY27 revenue target. Delivery against the roughly Rs 15 crore new-parts expectation and the Rs 31.8 crore order book will show how quickly the added capacity translates into reported sales.