










Apsis Aerocom Limited H1 capex reduces cash, retains net cash
Key highlights
- Apsis Aerocom invested Rs 23.33 crore in H1 FY27, including capital advances for Unit II.
- Cash and cash equivalents declined from Rs 34.44 crore to Rs 12.95 crore during H1 FY27.
- Apsis Aerocom reported net cash of Rs 11.61 crore at 30 September 2026.
- Net PPE increased from Rs 12.30 crore in March 2026 to Rs 24.61 crore.
powered by IRIS
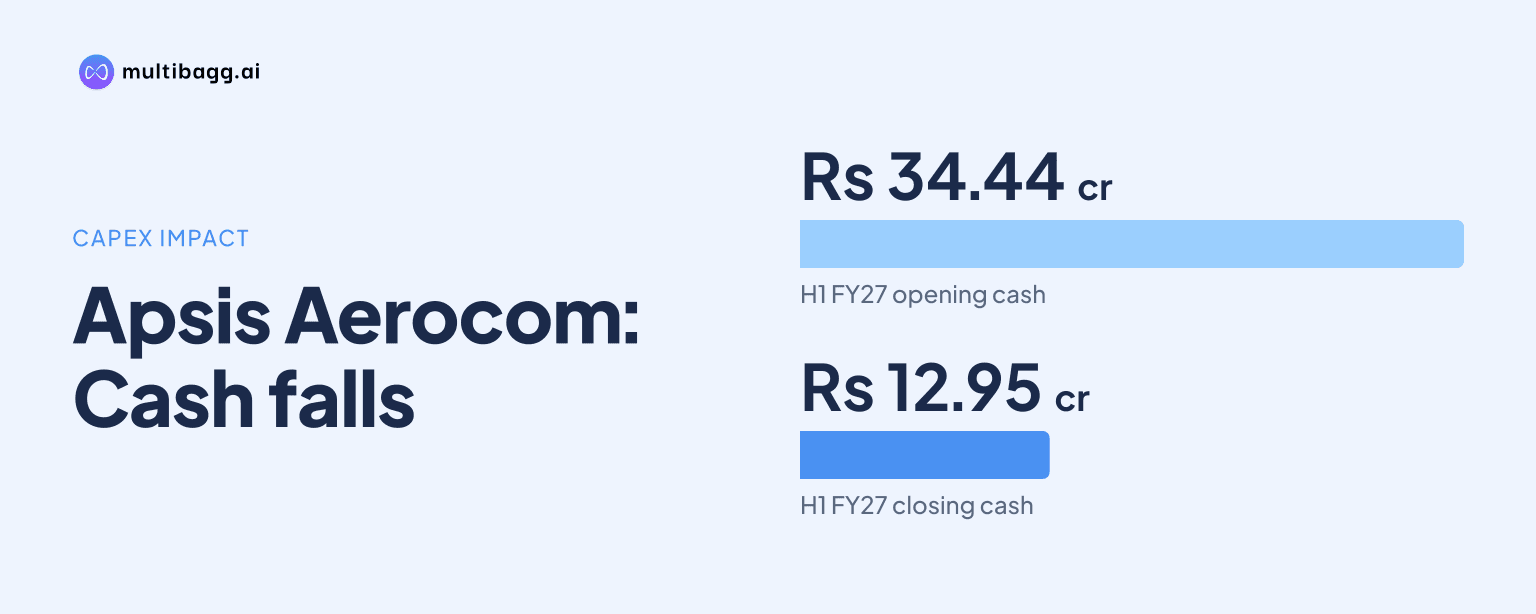
In H1 FY27, Apsis Aerocom Limited invested Rs 23.33 crore in Unit II capacity, reducing cash and cash equivalents to Rs 12.95 crore while retaining net cash of Rs 11.61 crore at 30 September 2026. The investment included capital advances and lifted property, plant and equipment to Rs 24.61 crore from Rs 12.30 crore in March 2026.
Know Apsis Aerocom inside out
Results, valuation, peers and who's buying, in one view.
How much did Apsis Aerocom invest in H1 FY27?
Apsis Aerocom invested Rs 23.33 crore during H1 FY27, including capital advances, in capacity expansion at Unit II. The company said initial public offering, or IPO, proceeds were deployed in advanced computer numerical control, or CNC, machines and inspection equipment for Unit II, in line with the objects of the issue.
The cash-flow statement records an investing outflow of Rs 23.33 crore in H1 FY27, the largest movement in the period. Operating cash flow contributed Rs 2.78 crore and financing activity used Rs 0.94 crore, leaving neither sufficient to offset the investment outflow. Cash and cash equivalents therefore fell by Rs 21.49 crore, from opening cash of Rs 34.44 crore to closing cash of Rs 12.95 crore.
The Rs 23.33 crore investment figure is larger than gross fixed-asset additions of Rs 13.30 crore because the presentation says investment includes capital advances. The reported cash outlay and the accounting movement in property, plant and equipment, or PPE, should therefore not be treated as identical measures at 30 September 2026.
What did Apsis Aerocom's Unit II investment add?
Apsis Aerocom's Unit II expansion increased net PPE from Rs 12.30 crore in March 2026 to Rs 24.61 crore at 30 September 2026, which the presentation describes as 2.0 times the March level. Gross additions were Rs 13.30 crore in H1 FY27, with 5-axis machining centres, multitasking machines, turning and turn-mill machines, and inspection equipment identified as investment categories.
Unit II had 15 machines as of 30 September 2026, while Apsis Aerocom had 33 machines in total. The presentation also identifies 20 new Unit II machines as adding capacity for H2 FY27. That programme supports management's reiterated FY27 revenue target of about Rs 48 crore, compared with Rs 21.17 crore of revenue achieved in H1.
The capacity build-out occurred before Unit II reached full utilisation, which management linked to H1 FY27 operating costs. Earnings before interest, tax, depreciation and amortisation, or EBITDA, margin fell to 30.8% from 35.2% in H1 FY26. Material cost rose to 37.5% of revenue from 33.6%, while other expenses increased to 12.4% from 10.7%, with management citing higher material intensity and Unit II running costs.
Management expects Unit II utilisation to rise through H2 FY27 and said this should support margins. This is a management expectation rather than a reported result: depreciation rose to 4.7% of revenue in H1 FY27 from 3.4% in H1 FY26, while profit after tax margin declined to 18.7% from 23.9%.
Got a follow-up? Ask IRIS
Did Apsis Aerocom remain in a net-cash position?
Apsis Aerocom remained in a net-cash position of Rs 11.61 crore at 30 September 2026, based on cash and bank balances of Rs 15.07 crore, including fixed deposits, and total borrowings of Rs 3.46 crore. Debt to equity was 0.07 times and net worth was Rs 52.92 crore on that date.
The presentation uses two cash measures that are not interchangeable. Its H1 FY27 cash-flow statement closes with Rs 12.95 crore of cash and cash equivalents and excludes other bank balances. The balance-sheet amount of Rs 15.07 crore includes fixed deposits, making it Rs 2.12 crore higher than the closing cash-and-cash-equivalents figure.
Net worth rose by Rs 4.02 crore from Rs 48.90 crore in March 2026 to Rs 52.92 crore in September 2026. It was Rs 42.70 crore above the Rs 10.22 crore reported in March 2025. The reported borrowings and net-worth figures correspond with the presentation's debt-to-equity ratio of 0.07 times.
Can Apsis Aerocom convert new capacity into FY27 revenue?
Apsis Aerocom reported an order book of Rs 31.80 crore at 30 September 2026, equal to 1.5 times H1 FY27 revenue of Rs 21.17 crore and 1.19 times the approximately Rs 26.80 crore of revenue required in H2 to meet its FY27 target. Management reiterated its target of about Rs 48 crore for FY27, of which H1 represented 44% and H2 would need to provide 56%.
The order book was led by defence at Rs 16.83 crore, or 53%, followed by aerospace at Rs 9.94 crore, or 31%. Healthcare accounted for Rs 4.36 crore, or 14%, and others represented Rs 0.66 crore, or 2%. In H1 FY27 revenue, defence contributed Rs 12.86 crore, aerospace Rs 5.79 crore and healthcare Rs 2.24 crore.
Working-capital execution will also affect how quickly revenue becomes cash. Apsis Aerocom reported 45 receivable days, 56 inventory days and 38 payable days in H1 FY27, producing net working-capital days of 63. The company defines net working capital as receivable days plus inventory days minus payable days.
Management's roadmap calls for further Unit II machine additions through FY28 and plans about Rs 80 crore of FY28 revenue, when it expects Units I and II to be at full capacity. The FY27 target and FY28 plan are forward-looking statements that management says are subject to risks and uncertainties.
Conclusion
Apsis Aerocom used a substantial portion of its H1 FY27 cash resources for Unit II, with Rs 23.33 crore of investing outflow and Rs 13.30 crore of gross additions lifting PPE to Rs 24.61 crore. Cash and cash equivalents fell to Rs 12.95 crore, but cash and bank balances including fixed deposits remained above Rs 3.46 crore of borrowings, resulting in reported net cash of Rs 11.61 crore.
The next disclosed measure is H2 FY27 utilisation and revenue delivery. Management needs approximately Rs 26.80 crore of H2 revenue to meet its reiterated target of about Rs 48 crore for FY27, supported by a Rs 31.80 crore order book, 20 new Unit II machines and its expectation that higher utilisation will support margins.