










Arihant targets 20% FY27 revenue growth and EBITDA above 25%
Key highlights
- Arihant reported H1 FY27 operating revenue of Rs 265 crore, up about 9% year on year.
- Arihant’s H1 FY27 EBITDA was Rs 56 crore, with EBITDA margin of 20.97%.
- Management expects FY27 revenue growth of 20% and EBITDA margin above 25%.
- Arihant booked Rs 345.8 crore in H1 FY27 sales and collected Rs 316 crore.
powered by IRIS
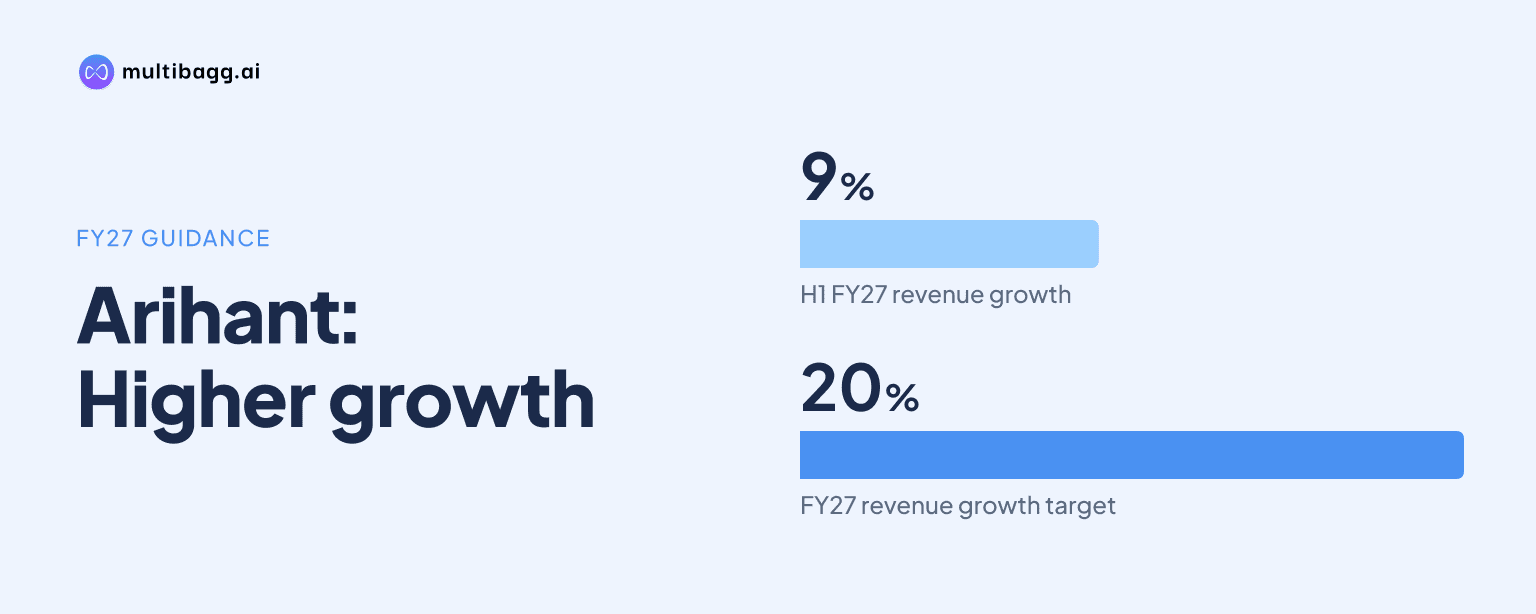
Arihant Superstructures Limited expects FY27 revenue to grow 20% and targets EBITDA margin above 25%, after reporting Rs 265 crore of operating revenue and a 20.97% EBITDA margin for the half year ended September 30, 2026. Management linked the outlook to project completions and planned occupancy certificates, or OCs.
Know Arihant Superstructures inside out
Results, valuation, peers and who's buying, in one view.
Can Arihant deliver its FY27 revenue growth target?
Arihant’s management expects 20% growth in FY27 revenue, supported by projects completed in the first quarter and further completions planned during the second half. Management specifically expects OCs for one tower at Arihant Aspire and Arihant Advika in Vashi by the end of FY27. It said these events should support both revenue recognition and sales collections in the coming two quarters.
The starting point is Rs 265 crore of H1 FY27 operating revenue, up about 9% year on year, including Rs 133 crore in Q2 FY27, also about 9% higher year on year. H1 FY27 EBITDA was Rs 56 crore, while Q2 FY27 EBITDA was Rs 28 crore. The quarterly EBITDA figure was 7% below the prior-year quarter but approximately 1.5% above Q1 FY27, showing a different quarterly trajectory from revenue growth.
Management said Arihant Advika has remaining inventory that can contribute to revenue for the next six to eight quarters, extending the relevance of that project beyond the FY27 completion target. Arihant reported H1 FY27 collections of Rs 316 crore, compared with Q2 collections of Rs 154.5 crore. The second-quarter figure was close to half of first-half collections.
Which projects are expected to support Arihant’s second-half revenue?
Arihant expects the OC-linked completion of the Arihant Aspire tower and Arihant Advika in Vashi to be the principal H2 FY27 revenue drivers. Management said the projects were near completion and that the anticipated certificates by year-end would help push revenue and collections. The guidance depends on these project milestones rather than an announced acquisition or commercial development.
Sales bookings were lower in Q2 FY27 because Arihant focused on inventory already available across projects with multiple phases, according to management. An analyst noted that presales had declined about 27% year on year, with units sold falling to 236 from 280. Management said it had more launches lined up in Panvel during Q3 and Q4 FY27 and expects the festive-season second half to perform better, based on the company’s experience over the preceding four to five years.
The Q2 FY27 booking data show 236 units, covering 2.2 lakh square feet, with booking value of Rs 173 crore. Average realisation was Rs 7,822 per square foot, up from Rs 7,500 per square foot in Q1 FY27, while average value per unit was Rs 73.15 lakh. For H1 FY27, Arihant booked 457 units spanning 4.52 lakh square feet for Rs 345.8 crore, at Rs 7,650 per square foot compared with Rs 7,500 per square foot in H1 FY26.
Got a follow-up? Ask IRIS
Why does Arihant expect EBITDA margin above 25%?
Arihant’s management is targeting EBITDA margin above 25% for the full FY27 year, despite reporting a 20.97% margin in H1 FY27. Management said quarterly margin movements reflect revenue mix and the timing of costs, and said annual performance should be assessed separately from individual quarters. The target is a management objective, not reported H1 performance.
The H1 comparison is 27.44% EBITDA margin in H1 FY26 against 20.97% in H1 FY27, a decline of 6.47 percentage points. Management said the reported profit-and-loss effects were primarily caused by project mix. It also said total construction costs had increased 4% to 5% over the preceding eight to nine months, while asserting that escalated costs had been incorporated into current and projected expenses.
Arihant’s pricing approach is to recover higher labour and input-material costs through pricing of unsold inventory rather than pursue volumes at the expense of margin. The company reported about 275 units of unsold ready inventory valued at Rs 53 crore. Whether pricing on that inventory and new Panvel launches offsets the cost increase will be relevant to the full-year margin target, especially as the Q2 FY27 margin was 21%.
How could financing and new projects affect Arihant’s outlook?
Arihant expects its average cost of debt to decline from about 13% to around 12.5% by the end of FY27. Management cited the replacement of an STCI loan priced at 11.75% with ICICI Bank funding at 8.6% as an example. It said reductions in financing cost from such transactions should appear in coming quarters, although the 25% EBITDA-margin target is an operating measure before interest costs.
At September 30, 2026, Arihant reported net worth of Rs 475 crore, net debt of Rs 827 crore and unsecured loans of Rs 435 crore. Management said operating cash flows from its other projects were expected to remain positive, but hotel and Gymkhana construction would require further financing because neither asset currently has sales. Hotel work was expected to begin in Q3 FY27, which management said would bring expenditure and construction progress.
At World Villas in Chowk, Arihant has launched the first phase of about 178 villas and sold about 60 villas to date. Management expects the remaining first-phase sales to occur over the next two years. Separately, Arihant signed an agreement with ITC Hotels Limited on September 24 for a 227-room hotel, including 44 suites, within the 90-acre World Villas development; construction is expected to take about three years and management expects hotel revenue from FY29.
Conclusion
Arihant’s FY27 outlook combines a 20% revenue-growth expectation with an EBITDA-margin target above 25%, against H1 performance of Rs 265 crore in revenue and a 20.97% margin. The central operating test is whether OCs for Arihant Aspire and Arihant Advika arrive by the end of FY27 and convert the near-completion pipeline and Vashi inventory into revenue and collections.
The next developments to watch are the planned Q3 and Q4 FY27 Panvel launches, the stated reduction in average debt cost toward 12.5%, and World Villas sales, where about 60 of 178 first-phase villas had been sold. Management also expects annuity income from the hotel and Club 10 Gymkhana to begin contributing to profit and loss from FY30 onwards.