










Ashok Leyland auditors disclaim consolidated Q2 conclusion
Key highlights
- Ashok Leyland’s consolidated auditor issued a disclaimer of conclusion for results ended September 30, 2026.
- HLFL had total assets of Rs 70,403.39 crore and net assets of Rs 9,263.85 crore at September 30, 2026.
- HLFL reported Rs 2,229.70 crore of quarterly revenue and Rs 174.54 crore of net profit after tax.
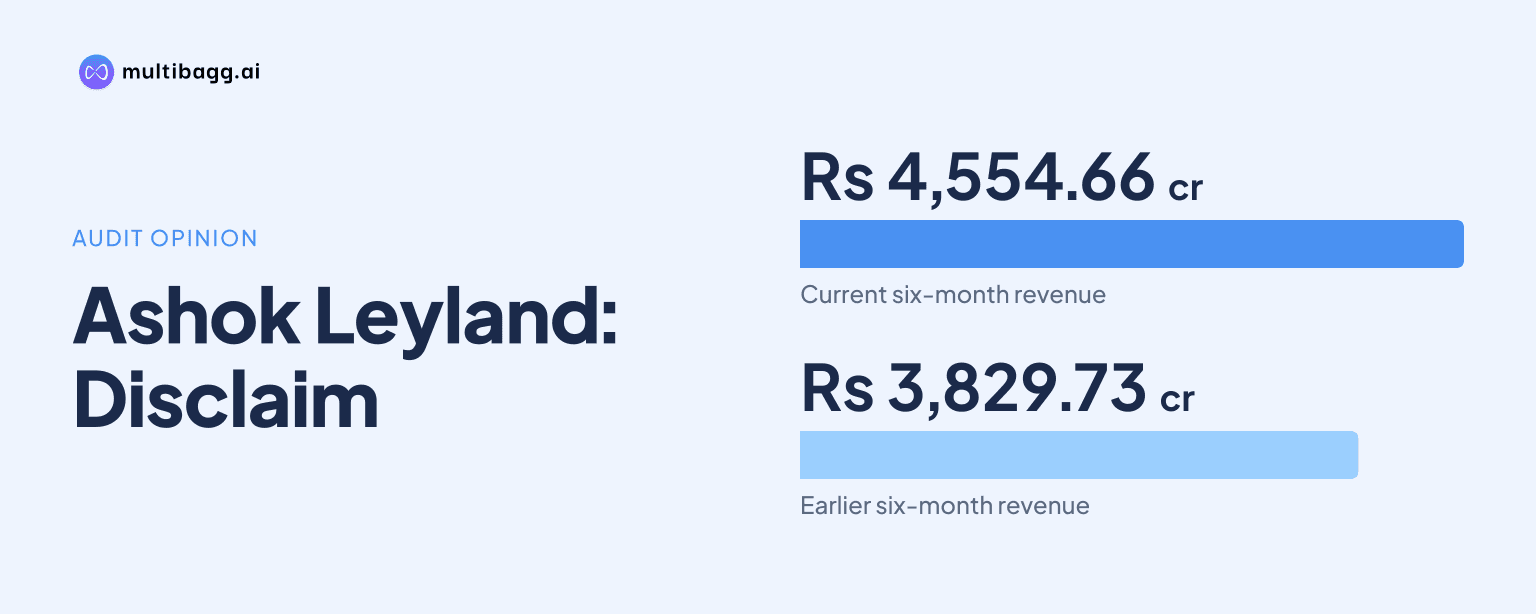
- Ashok Leyland reported six-month financial-services revenue of Rs 4,554.66 crore, up from Rs 3,829.73 crore a year earlier.
powered by IRIS
Ashok Leyland Limited’s consolidated results for the quarter ended September 30, 2026 received an auditor disclaimer because Hinduja Leyland Finance Limited is reconciling loan balances across systems, and the subsidiary had total assets of Rs 70,403.39 crore. Management said the differences were not expected to adversely affect HLFL’s financial health or debt-servicing ability.
Know Ashok Leyland inside out
Results, valuation, peers and who's buying, in one view.
Why did Ashok Leyland’s consolidated review receive a disclaimer?
Ashok Leyland’s consolidated review received a disclaimer because its auditor could not obtain sufficient appropriate evidence while HLFL’s review of loan-balance differences remains unfinished. HLFL is reconciling certain differences between underlying sub-systems, and the financial impact, if any, was not ascertainable when results for the quarter and six months ended September 30, 2026 were prepared. The group did not recognise a possible impact from those differences in its consolidated results.
Price Waterhouse & Co Chartered Accountants LLP said it could not determine whether adjustments were necessary to the consolidated statement, which incorporates HLFL’s special-purpose consolidated unaudited financial results. HLFL’s joint auditors had included the same matter as the basis for their disclaimer in a review report dated November 13, 2026. The group auditor, in its November 14, 2026 report, therefore said it did not express a conclusion on Ashok Leyland’s consolidated statement.
The limitation does not apply to Ashok Leyland’s standalone financial results for the same September 30, 2026 periods. In the standalone review report dated November 14, 2026, the auditor said nothing had come to its attention indicating that the statement was not prepared, in all material respects, under applicable accounting standards. The distinction is material because the disclaimer is tied to the financial information of HLFL, a group subsidiary, rather than the parent’s standalone accounts.
How material is HLFL to Ashok Leyland’s consolidated accounts?
HLFL is material to Ashok Leyland’s consolidated accounts, reporting Rs 70,403.39 crore of total assets and Rs 9,263.85 crore of net assets as at September 30, 2026. The auditor cited these balances when explaining why the unresolved systems review prevented it from concluding on the group statement. HLFL’s scale means that any adjustment emerging from the review could affect amounts included in the consolidated results.
HLFL reported quarterly revenue of Rs 2,229.70 crore and net profit after tax of Rs 174.54 crore for the quarter ended September 30, 2026. Its total comprehensive income was a loss of Rs 1,311.97 crore in that quarter, while the six-month figure was a loss of Rs 1,244.97 crore. Net cash flows for the April 1, 2026 to September 30, 2026 period were an outflow of Rs 1,630.40 crore, according to the auditor’s description of the subsidiary’s financial information.
What is HLFL doing to resolve the loan-balance differences?
HLFL has appointed an independent systems expert to conduct a comprehensive review of the relevant systems and processes. After that review is completed, HLFL says it will evaluate the findings and take action it considers necessary in accordance with accounting and regulatory requirements. The November 14, 2026 filing does not give a completion date, quantify the loan-balance differences, or identify the sub-systems involved.
Management’s view is that the differences are not likely to be significant enough to adversely affect HLFL’s financial health, including its ability to service debt obligations. That is management’s stated assessment, whereas the auditor’s disclaimer says sufficient appropriate evidence was unavailable to form a conclusion on the consolidated results. The separate positions remain relevant until the review produces findings and HLFL evaluates whether any adjustment is required.
Ashok Leyland also said its standalone investment in HLFL was carried at cost as at September 30, 2026. Based on HLFL’s financial position and business prospects, management said it expected no impairment in the carrying value of that investment. This too is a management assessment made while the systems review and reconciliation remain unresolved.
Got a follow-up? Ask IRIS
What did Ashok Leyland report in its operating segments?
Ashok Leyland reported consolidated revenue from operations of Rs 17,029.87 crore for the quarter ended September 30, 2026, comprising Rs 14,746.97 crore from commercial vehicles and Rs 2,283.74 crore from financial services. Financial-services revenue included interest income of Rs 1,964.19 crore. The group identifies commercial vehicles and financial services, mainly vehicle and housing financing, as its reportable segments.
Commercial-vehicle revenue increased to Rs 14,746.97 crore in the September 2026 quarter from Rs 10,799.31 crore in the June 2026 quarter, an increase of Rs 3,947.66 crore. Financial-services revenue changed by Rs 12.82 crore over the same comparison, rising from Rs 2,270.92 crore to Rs 2,283.74 crore. This shows that the reported sequential revenue increase was concentrated in the commercial-vehicle segment.
For the six months ended September 30, 2026, commercial-vehicle revenue rose to Rs 25,546.28 crore from Rs 20,456 crore in the comparable prior-year period. Financial-services revenue increased to Rs 4,554.66 crore from Rs 3,829.73 crore. Ashok Leyland’s board approved the unaudited results on November 14, 2026 and approved an interim dividend of rupees 1 per equity share of face value rupees 1 for the financial year ending March 31, 2027.
What other disclosed matters should readers track?
Ashok Leyland said the National Company Law Tribunal, Mumbai Bench sanctioned the merger of HLFL into NDL Ventures Limited on November 3, 2026, with a clarification order dated November 5, 2026. The appointed date is April 1, 2026, but the merger was not reflected in the September 30, 2026 standalone or consolidated financial statements because approvals and administrative formalities, including filings with the Registrar of Companies, remained pending.
Under the scheme, HLFL’s business, assets, liabilities and undertakings will transfer to NDL when it becomes effective, and every 10 HLFL shares will result in 25 NDL shares. Ashok Leyland said it would retain control over HLFL’s business before and after the merger, and management did not anticipate a material impact on consolidated results. The company said the main accounting effect would be a marginal increase in non-controlling interest in the merged entity.
A separate issue concerns Hinduja Housing Finance Limited, or HHFL, a step-down subsidiary. Its Principal Business Criteria ratio fell to 59.11% at September 30, 2026 from 62.91% at June 30, 2026 after loan exposures were reclassified from housing to non-housing. HHFL is preparing a corrective-action plan for board approval, with the stated objective of restoring the ratio above the prescribed regulatory threshold.
Conclusion
Ashok Leyland’s consolidated September-quarter results cannot receive an auditor conclusion until the review of HLFL’s loan-balance differences allows the auditor to assess whether adjustments are needed. The issue involves a subsidiary with Rs 70,403.39 crore of assets, while the group reported Rs 30,099.46 crore of revenue from operations for the six months ended September 30, 2026.
The next development to watch is completion of HLFL’s independent systems review and management’s subsequent accounting or regulatory response. Readers can also track the merger into NDL, which remains subject to administrative completion after the November 3, 2026 tribunal order, and HHFL’s plan to restore its 59.11% Principal Business Criteria ratio.