










Astral Limited sees Q3 plumbing margins improve after pass-through
Key highlights
- Astral's Q2 FY27 plumbing EBIDTA margin was 16.3%, versus 19.0% in Q2 FY26.
- Astral said it fully passed on Q2 PVC and CPVC price increases in Q3 FY27.
- Plumbing revenue rose 25.0% to Rs 1,398.3 crore and volume rose 19.1% to 72,934 MT in Q2 FY27.
- Astral's 40,000-MT CPVC resin plant is planned to be commercially ready in Q4 FY27, with full benefits expected from FY28.
powered by IRIS
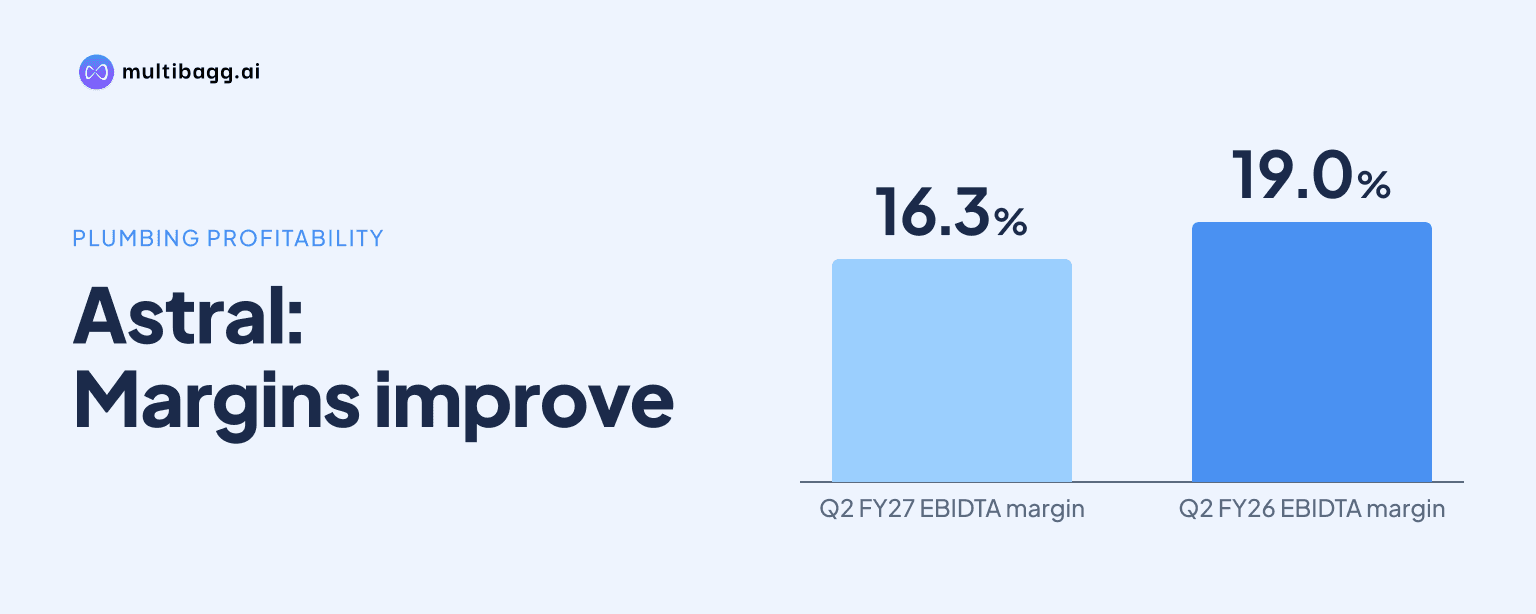
Astral Limited expects plumbing margins to improve in Q3 FY27 after it passed through Q2 increases in polyvinyl chloride (PVC) and chlorinated polyvinyl chloride (CPVC) prices, following a Q2 FY27 segment earnings before interest, depreciation, tax and amortisation (EBIDTA) margin of 16.3%. Astral said the delayed pass-through had put Q2 margins under pressure.
Know Astral inside out
Results, valuation, peers and who's buying, in one view.
Why were Astral's Q2 plumbing margins under pressure?
Astral's Q2 FY27 plumbing margin was under pressure because polymer prices rose during the quarter while the full PVC and CPVC price increase was passed on only in Q3 FY27. The plumbing segment reported an EBIDTA margin of 16.3% in Q2 FY27, down from 19.0% in Q2 FY26, despite revenue from operations rising 25.0% year on year to Rs 1,398.3 crore.
The timing difference between input costs and selling-price revisions explains why profitability did not rise at the pace of sales. Plumbing segment EBIDTA increased 6.9% to Rs 227.6 crore in Q2 FY27 from Rs 212.9 crore a year earlier, while sales volume rose 19.1% to 72,934 metric tonnes (MT), leaving the margin 2.7 percentage points below the prior-year quarter.
What has Astral changed for Q3 FY27?
Astral said it had already passed on the full Q2 FY27 price rise in PVC and CPVC during Q3 FY27, and therefore expects better margins and better realizations in the plumbing business. This is management's stated near-term margin trigger, rather than a reported Q3 financial result, because the announcement covers the quarter ended September 30, 2026.
The company also said polymer-price volatility was continuing, although it expected that volatility to be comparatively lower. In Q2 FY27, plumbing value growth of 25.0% exceeded volume growth of 19.1%, which Astral attributed to slightly better realization during the quarter; the completed Q3 price pass-through is expected to add to that realization improvement.
For the first half of FY27, plumbing revenue rose 18.2% to Rs 2,448.8 crore and segment EBIDTA rose 15.3% to Rs 425.9 crore. The first-half margin was 17.4%, compared with 17.8% in H1 FY26, showing a 0.4-percentage-point decline that was narrower than the 2.7-percentage-point Q2 decline.
How does plumbing growth compare with Astral's other business?
Astral's plumbing business delivered lower revenue growth than paints and adhesives in Q2 FY27, but it produced a higher segment margin. Plumbing revenue rose 25.0% to Rs 1,398.3 crore, while paints and adhesives revenue increased 28.6% to Rs 590 crore; their respective segment EBIDTA margins were 16.3% and 7.6%.
The paints and adhesives segment faced its own cost-pass-through lag. Its Q2 FY27 EBIDTA fell 19.2% year on year to Rs 44.7 crore from Rs 55.3 crore, and its margin declined from 12.1% to 7.6%, even as revenue increased by Rs 131.2 crore. Astral said continued higher raw-material prices linked to geopolitical pressure affected adhesives, while volatile raw-material prices affected paint margins.
At the consolidated level, revenue from operations grew 26.0% to Rs 1,988.3 crore in Q2 FY27, but EBIDTA increased only 1.5% to Rs 272.3 crore. Consequently, consolidated EBIDTA margin fell to 13.7% from 17.0%, while profit after tax before other comprehensive income declined 5.6% to Rs 127.3 crore.
Got a follow-up? Ask IRIS
Is Astral on track for its FY27 plumbing volume plan?
Astral said it remained in line with its guidance for double-digit plumbing-pipe volume growth in FY27 after delivering 10.0% growth in H1 FY27. First-half plumbing sales volume reached 129,080 MT, compared with 117,298 MT in H1 FY26, and management said it was confident of delivering the same double-digit growth in H2 FY27.
Management described Q2 pipe demand as robust, citing a weak Q1 FY27 comparison for the industry and light inventory in the system. Management also said Astral continued to seek market-share gains, and stated that its 17.4% H1 FY27 plumbing EBIDTA margin was the highest among industry players and within its full-year guided range of 16% to 18%.
Production capacity for pipes and fittings increased by 7,550 MT during H1 FY27, to 425,195 MT from 417,645 MT. That capacity addition comes alongside 19.1% Q2 volume growth and gives context for Astral's stated aim of continuing double-digit volume expansion through the second half.
What could support Astral's plumbing margins beyond Q3?
Astral expects its 40,000-MT Phase I CPVC resin backward-integration plant to support CPVC pipe-and-fitting market share and improve margins, with the full benefit expected from FY28 onwards. Machinery installation was under way as of the November 5, 2026 announcement, with trials and commercial readiness planned for Q4 FY27.
The company also planned to launch Pex, or aluminium Pex, in Q3 FY27. Separately, bathware sales grew 26.8% in Q2 FY27, making it another reported growth area within the plumbing vertical of pipes, fittings, water tanks and bathware, although Astral did not disclose separate bathware revenue or profitability.
The FY28 benefit from CPVC resin production is distinct from the immediate Q3 FY27 price-pass-through effect. The former depends on the scheduled Q4 FY27 commissioning and operation of the 40,000-MT plant, whereas the latter reflects prices Astral said it had already passed on for the Q2 increase in PVC and CPVC.
Conclusion
Astral's disclosed Q3 FY27 plumbing-margin outlook rests principally on the completion of PVC and CPVC price increases that lagged Q2 FY27 polymer-cost inflation. The segment's 16.3% Q2 margin was below 19.0% a year earlier even though revenue gained 25.0% and volume advanced 19.1%, while the 17.4% H1 margin remained within management's 16% to 18% full-year range.
The next points to watch are whether H2 FY27 plumbing volume maintains the double-digit growth management expects, whether Q3 realizations and margins improve after the pass-through, and whether the 40,000-MT CPVC resin plant completes trials and becomes commercially ready in Q4 FY27. Astral expects the full margin benefit from that backward integration only from FY28 onwards.