










Astral paints and adhesives sales rise 29%, EBITDA declines
Key highlights
- Astral’s paints and adhesives revenue increased 29.0% to Rs 1,117.5 crore in H1 FY27.
- Astral’s segment EBITDA declined 2.6% to Rs 90.4 crore and margin fell to 8.1% from 10.7%.
- Astral’s Q2 FY27 paints and adhesives revenue rose 28.6% to Rs 590 crore, while EBITDA fell 19.2% to Rs 44.7 crore.
- DSS contributed Rs 12.04 crore of standalone revenue and Rs 1.66 crore of EBITDA in H1 FY27.
powered by IRIS
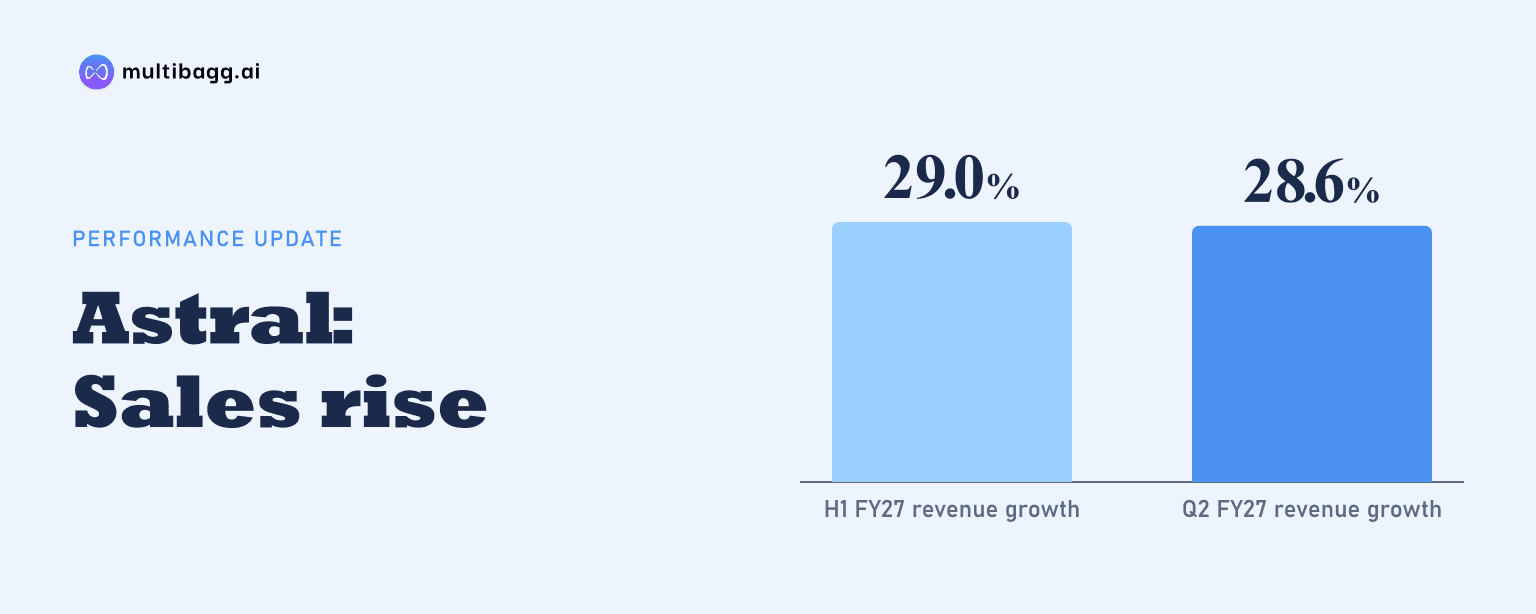
Astral Limited reported 29.0% growth in paints and adhesives revenue to Rs 1,117.5 crore in H1 FY27 ended September 30, 2026, while segment EBITDA declined 2.6% to Rs 90.4 crore and the margin fell to 8.1% from 10.7% a year earlier.
Know Astral inside out
Results, valuation, peers and who's buying, in one view.
How did Astral’s paints and adhesives segment perform in H1 FY27?
Astral’s paints and adhesives segment grew revenue by 29.0% year on year to Rs 1,117.5 crore in H1 2026-27, from Rs 866.1 crore in H1 2025-26. This growth exceeded Astral’s consolidated revenue increase of 21.4%, which took group revenue from operations to Rs 3,566.3 crore during the six-month period.
Segment EBITDA, or earnings before interest, depreciation, tax and amortisation, moved in the opposite direction. It declined by 2.6% to Rs 90.4 crore from Rs 92.8 crore, while the EBITDA margin fell by 2.6 percentage points to 8.1% from 10.7%. The reported figures show that the Rs 251.4 crore increase in segment sales did not result in higher EBITDA.
The second quarter showed a steeper earnings decline than the half-year result. Q2 2026-27 segment revenue rose 28.6% to Rs 590 crore from Rs 458.8 crore, but EBITDA fell 19.2% to Rs 44.7 crore from Rs 55.3 crore and the margin declined to 7.6% from 12.1%.
Why did Astral’s paints and adhesives margin decline?
Astral attributed the margin decline to higher and volatile raw-material costs, combined with a lag in passing those costs through to customers. The company said geopolitical pressure kept adhesive raw-material prices elevated in Q2 FY27, while price pass-through occurred after a gap.
The timing issue coincided with a Rs 10.6 crore decline in Q2 segment EBITDA despite a Rs 131.2 crore increase in quarterly revenue. This comparison indicates that higher sales in the reported quarter did not fully offset input-cost pressure before pricing actions took effect.
Paints also faced volatile raw-material prices and delayed recovery of higher costs. Astral said paint sales increased 39.9% in Q2 FY27 and 44% in H1 FY27, but margins remained under pressure; management expects improved paint margins in the coming quarter, which is an outlook rather than a reported result.
Consolidated results showed a smaller margin contraction. Astral’s H1 FY27 consolidated EBITDA rose 11.7% to Rs 516.3 crore from Rs 462.2 crore, but the consolidated EBITDA margin declined to 14.5% from 15.7%; in Q2, revenue increased 26.0% while EBITDA rose 1.5% and margin fell to 13.7% from 17.0%.
Which businesses supported Astral’s paints and adhesives sales growth?
Astral said its India adhesive business grew sales by 25.3% in Q2 FY27 and recorded an EBITDA margin of 10.9%. The company attributed growth to volume momentum in Maintenance and New Bharat, alongside additions of dealers and distribution.
Joinery recorded quarter-on-quarter growth through distribution expansion and a wider product portfolio, according to Astral. Its construction division was supported by backward integration and range expansion in epoxy grouts, tile adhesives and other advanced chemistries, although the release gave no separate revenue or EBITDA figures for those product lines.
The overseas adhesive business grew sales by 30.1% in Q2 FY27 and reported a positive EBITDA margin of 6.3%. In H1 FY27, overseas adhesive revenue grew 28.1%, compared with Astral’s stated guidance of more than 10% revenue growth, but the company did not disclose the business’s absolute H1 revenue.
The segment includes the former Resinova business, Seal IT, Astral Chemie Limited and Differentiated & Sustainable Solutions LLP, or DSS. Therefore, the reported H1 revenue of Rs 1,117.5 crore and EBITDA of Rs 90.4 crore combine paints, domestic and overseas adhesives, and specialty chemicals rather than representing the paints business alone.
Got a follow-up? Ask IRIS
What did specialty chemicals and new products add to Astral’s segment?
Astral Chemie, Astral’s wholly owned subsidiary, entered definitive agreements dated June 11, 2026 to acquire a 60% partnership interest in DSS with effect from April 1, 2026. Astral said the Q1 FY27 transaction expanded its portfolio into specialty chemicals.
DSS contributed standalone H1 FY27 revenue of Rs 12.04 crore and EBITDA of Rs 1.66 crore. Astral said infrastructure upgrades and capacity enhancement were under way to support volume and portfolio expansion in FY28, without disclosing a spending amount or revised capacity.
In paints, Astral launched Extura Vivid, an exterior emulsion, in Q1 FY27. The company said dealer, contractor and consumer initiatives continued in Q2 FY27 and that the product was gaining acceptance across its network, but it did not disclose Extura Vivid revenue.
The 44% H1 FY27 paint-sales growth was above the segment’s 29.0% revenue growth rate, while India adhesive sales grew 25.3% in Q2 and overseas adhesive sales grew 30.1%. Astral did not provide separate H1 revenue values for paints, India adhesives and overseas adhesives, so the contribution of each business to the Rs 251.4 crore segment revenue increase cannot be calculated from the release.
How does Astral’s paints and adhesives segment compare with plumbing?
Astral’s plumbing segment reported H1 FY27 revenue of Rs 2,448.8 crore, up 18.2% from Rs 2,072.5 crore, and EBITDA of Rs 425.9 crore, up 15.3% from Rs 369.4 crore. Its EBITDA margin was 17.4%, compared with 8.1% for paints and adhesives, a difference of 9.3 percentage points.
The segments also differed in their earnings direction. Paints and adhesives added Rs 251.4 crore of H1 revenue while EBITDA declined by Rs 2.4 crore, whereas plumbing added Rs 376.3 crore of revenue and Rs 56.5 crore of EBITDA; plumbing sales volume rose 10.0% to 129,080 metric tonnes.
Astral said it had fully passed through Q2 FY27 price increases for PVC and CPVC, or polyvinyl chloride and chlorinated polyvinyl chloride, in plumbing during Q3 FY27. That action relates to plumbing, while the company separately said adhesive raw-material costs and delayed pass-through pressured Q2 margins.
At September 30, 2026, Astral had consolidated cash, including cash equivalents, and bank balances of Rs 459 crore. Its board approved an interim dividend of Rs 1.50 per share, with a face value of Re 1, but the release did not allocate cash or dividend funding between plumbing and paints and adhesives.
Conclusion
Astral’s H1 FY27 paints and adhesives result combines rapid revenue growth with lower EBITDA and a 2.6-percentage-point margin decline. Paint growth of 44% in H1 and Q2 sales growth in both India and overseas adhesives supported revenue, but higher raw-material costs and delayed pricing recovery affected segment profitability.
The next reported quarter will show whether management’s expectation of improved paint and adhesive margins is reflected in EBITDA. Investors can also watch progress on DSS infrastructure and capacity work intended to support FY28 volume and product-portfolio expansion, as Astral has not disclosed a numerical margin target for the segment.