










Banka BioLoo Receivables Hold Near Rs 26 Crore in H1
Key highlights
- Banka BioLoo reported H1 FY26-27 receivables of Rs 26 crore, versus Rs 25.67 crore at March 2026.
- Banka BioLoo generated Rs 1.88 crore of standalone operating cash flow in H1 FY26-27, up from Rs 1.06 crore a year earlier.
- Banka BioLoo’s consolidated net debt-to-equity was 0.82x in Q2 FY26-27, compared with 0.74x at March 31, 2026.
- Banka BioLoo’s Megaliter portfolio had 16 contracted projects and more than Rs 140 crore of contracted LTV in H1 FY26-27.
powered by IRIS
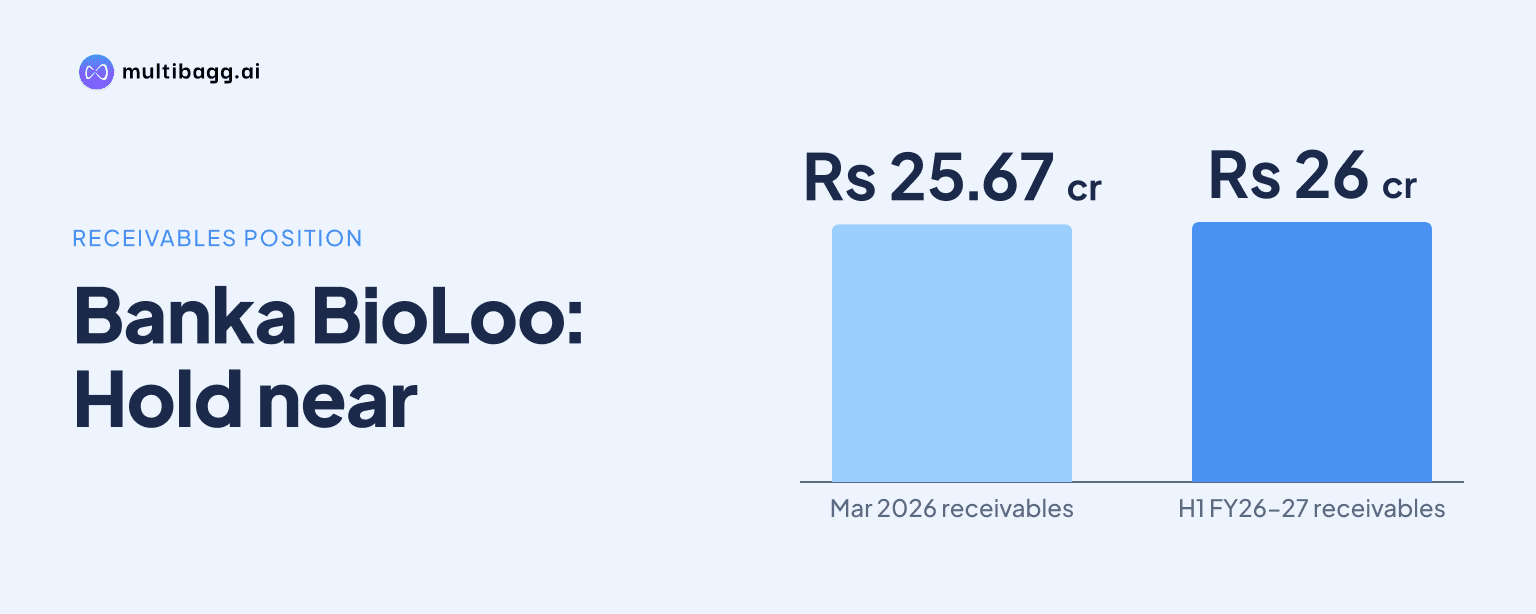
Banka BioLoo Limited reported H1 FY26-27 receivables of Rs 26 crore, slightly above Rs 25.67 crore at March 2026, while standalone operating cash flow reached Rs 1.88 crore and consolidated net debt-to-equity rose to 0.82x. Its FY27 scorecard makes commissioning, collection and sustainable profit before tax central execution priorities.
Know Banka Bioloo inside out
Results, valuation, peers and who's buying, in one view.
Why did Banka BioLoo receivables remain near Rs 26 crore?
Banka BioLoo’s receivables remained near Rs 26 crore in H1 FY26-27, compared with Rs 25.67 crore at March 2026. The scorecard identifies “Collect” as one of five FY27 priorities and sets out a sequence of commissioning projects, billing customers, collecting cash and delivering sustainable profit before tax, or PBT.
The presentation does not provide a receivables ageing profile, customer concentration or a stated collection target. It reports standalone operating cash flow of Rs 1.88 crore for H1 FY26-27, up from Rs 1.06 crore in H1 FY25-26, indicating higher cash generation while the reported receivables balance remained close to its March 2026 level.
Standalone total income increased 22.5% year on year to Rs 32.96 crore in H1 FY26-27 from Rs 26.91 crore in H1 FY25-26. The presentation attributes the improvement in cash-flow management to a shift from long-cash-cycle government orders to Category A+ private clients, but does not provide customer-level collection data supporting that explanation.
How did Banka BioLoo’s profit and cash flow change in H1?
Banka BioLoo returned to standalone profit in H1 FY26-27, reporting PBT of Rs 91.6 lakh against a PBT loss of Rs 1.49 crore in H1 FY25-26. Standalone earnings before interest, tax, depreciation and amortisation, or EBITDA, excluding other income were Rs 3 crore, while operating cash flow was Rs 1.88 crore for the April-to-September period.
Standalone EBITDA rose to Rs 3.08 crore in H1 FY26-27 from Rs 64 lakh a year earlier, while profit after tax, or PAT, moved to Rs 79 lakh from a Rs 97 lakh loss. In Q2 FY26-27, standalone income was Rs 16.56 crore, EBITDA was Rs 1.57 crore and PAT was Rs 41.6 lakh.
The presentation says the move towards Category A+ private clients supported the turnaround from the prior-year loss. Although H1 operating cash flow increased by Rs 82 lakh from the prior-year level, receivables at Rs 26 crore were still above the Rs 25.67 crore disclosed for March 2026.
On a consolidated basis, H1 PAT was Rs 9.2 lakh, compared with a Rs 1.09 crore loss in H1 FY25-26. The deck links the difference between standalone and consolidated outcomes to Megaliter Varunaa’s owned-plant model, under which finance cost and depreciation form part of building the recurring-revenue asset base.
Got a follow-up? Ask IRIS
What must Banka BioLoo commission during FY27?
Banka BioLoo reported completion of five sewage treatment plants, or STPs, and multiple smaller projects in Q2 FY26-27, with four projects commissioned and four under commissioning across engineering, procurement and construction, or EPC, and Megaliter work. The scorecard makes commissioning the first step before billing and collection.
Megaliter had 16 contracted projects in H1 FY26-27, of which 13 had been commissioned through Q2 and three were work in progress. The portfolio had contracted treatment capacity of 11 million litres per day, or MLD, and contracted lifetime value, or LTV, of more than Rs 140 crore, with about 80% yet to be recognised according to the presentation.
The portfolio expanded from six plants, 5.3 MLD and Rs 49.43 crore of contracted LTV in 2025-26 to 16 plants, 11 MLD and more than Rs 140 crore in H1 FY26-27. Banka BioLoo describes Megaliter as an annuity platform that owns the plants it builds and earns contracted revenue over years, rather than relying only on one-off EPC revenue.
Digitisation is another FY27 scorecard item connected to asset execution. Banka BioLoo reported that more than 10 assets were online and monitored in H1 FY26-27, and said all 25-plus STP sites would be online in Q3; the deck does not quantify any related reduction in operating cost or improvement in collections.
How is Megaliter capex affecting Banka BioLoo’s leverage?
Banka BioLoo’s consolidated net debt-to-equity rose to 0.82x in Q2 FY26-27 from 0.74x at March 31, 2026. The company reported H1 Megaliter capital expenditure of Rs 12.43 crore, funded by Rs 5 crore of outside equity and Rs 4.11 crore of net borrowings.
The expansion also affected the reported comparison between standalone and consolidated income. Q2 consolidated income was Rs 11.87 crore, down 9.2% year on year, while standalone income increased 24.5% to Rs 16.56 crore; the presentation says Rs 6.83 crore of intercompany EPC work was eliminated on consolidation, versus about Rs 1.23 crore a year earlier.
Megaliter contributed Rs 2.13 crore of Q2 income and Rs 1.17 crore of EBITDA before intercompany adjustments, with an EBITDA margin of about 55%. After a Rs 35 lakh adjustment, consolidated EBITDA was Rs 2.38 crore and the consolidated EBITDA margin was 20.1%, compared with about 0.5% a year earlier.
The presentation frames the 0.82x net debt-to-equity ratio in the context of funding Megaliter’s owned infrastructure base, but gives no leverage ceiling or debt-reduction timetable. Banka BioLoo also states a 2030 operating ambition to recycle more than 15 billion litres of water annually, while explicitly distinguishing that ambition from FY27 guidance.
Conclusion
Banka BioLoo’s FY27 scorecard shows improved standalone income, EBITDA, PBT and operating cash flow alongside receivables that remained close to Rs 26 crore. Megaliter’s 16 contracted projects and more than Rs 140 crore of contracted LTV support the company’s recurring-revenue plan, while capex funding contributed to net debt-to-equity rising to 0.82x.
The next disclosed milestones are the four projects under commissioning and the plan to bring all 25-plus STP sites online in Q3. Subsequent quarterly scorecards will also show whether receivables move below the Rs 25.67 crore March 2026 level and whether leverage changes after the Rs 12.43 crore of H1 Megaliter capex.