










Cohance H1 margin falls to 6.1% as revenue drops 18.6% YoY
Key highlights
- Cohance’s H1FY27 adjusted EBITDA margin fell to 6.1% from 23.8% in H1FY26.
- H1FY27 revenue declined 18.6% year on year to Rs 898.9 crore.
- Pharma CDMO revenue fell 32.7% to Rs 292.6 crore, while Specialty Chemicals fell 38.1% to Rs 74.7 crore.
- Q2FY27 adjusted EBITDA margin improved to 9.6% from 2.2% in Q1FY27.
powered by IRIS
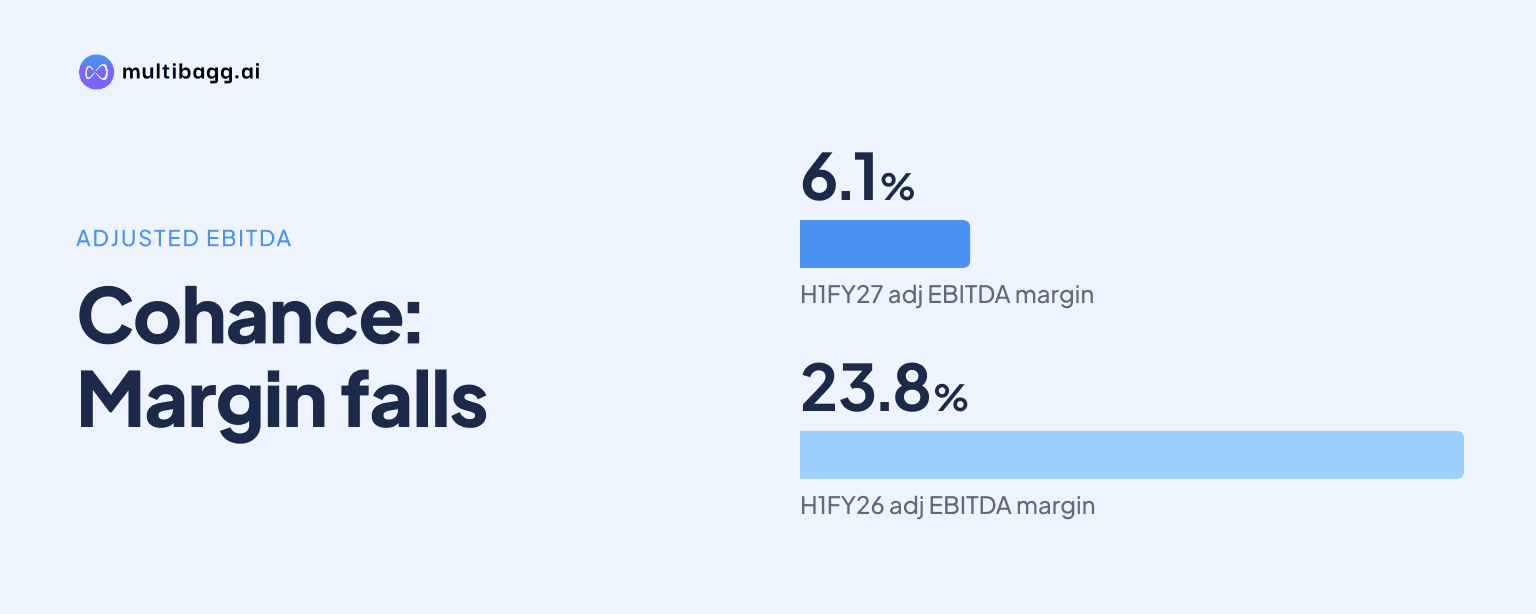
Cohance Lifesciences’ adjusted EBITDA margin fell to 6.1% in H1FY27 from 23.8% in H1FY26 as revenue declined 18.6% to Rs 898.9 crore and adjusted EBITDA dropped 79.0% to Rs 55.1 crore. The first-half result reflected lower Pharma CDMO and Specialty Chemicals revenue, while Q2FY27 showed a sequential improvement.
Know Cohance Lifesciences inside out
Results, valuation, peers and who's buying, in one view.
How did Cohance’s H1FY27 profitability change?
Cohance reported adjusted earnings before interest, tax, depreciation and amortisation (EBITDA) of Rs 55.1 crore in H1FY27, down from Rs 263 crore in H1FY26, taking the adjusted EBITDA margin down 17.7 percentage points to 6.1%. Reported EBITDA fell 84.4% to Rs 36.7 crore and its margin was 4.1%, versus 21.3% a year earlier. Adjusted EBITDA reflected a Rs 9 crore foreign-exchange mark-to-market gain and Rs 9.4 crore of one-time ESOP, merger and acquisition costs in H1FY27, compared with Rs 5.6 crore and Rs 22.5 crore respectively in H1FY26.
Cohance recorded an adjusted loss after tax of Rs 35.4 crore in H1FY27, compared with adjusted profit after tax (PAT) of Rs 130.2 crore in H1FY26. Adjusted loss before tax was Rs 44 crore, after depreciation and amortisation of Rs 99.7 crore, finance costs of Rs 15.1 crore and other income of Rs 15.7 crore. Reported PAT was a loss of Rs 8.9 crore, against a profit of Rs 122.9 crore a year earlier.
Why did Cohance’s revenue and margin decline in H1FY27?
Cohance’s revenue decline was concentrated in the Pharma CDMO and Specialty Chemicals businesses, while all reported segments declined in H1FY27. Material margin, calculated as revenue less material costs or cost of goods sold, fell 21.6% to Rs 639.5 crore from Rs 815.6 crore. Its margin narrowed to 71.1% from 73.8%, before manufacturing, employee and other operating costs.
Management attributed the Q2FY27 gross-margin contraction of 378 basis points year on year to an unfavourable product mix, lower AgChem contribution, weaker Small Molecule revenue conversion and API+ raw-material inflation. It said Sapala and Formulations partly offset these pressures. Across H1FY27, employee cost increased to Rs 286.5 crore from Rs 260 crore even as revenue fell, while total expenses rose to Rs 602.8 crore from Rs 580.7 crore.
The reported mix also shifted. Pharma CDMO and Specialty Chemicals together, described by Cohance as CDMO, represented 41% of H1FY27 revenue, while niche technology contributed 14.4%. The presentation cautioned that quarterly comparisons in the CDMO industry may not reflect consistent performance because of its lumpy nature, making programme timing relevant to the first-half revenue decline.
Which Cohance segments accounted for the revenue movement?
Pharma CDMO was the largest source of the decline in absolute terms, with H1FY27 revenue falling 32.7% year on year to Rs 292.6 crore from Rs 434.5 crore. Specialty Chemicals fell 38.1% to Rs 74.7 crore from Rs 120.8 crore, while the API+ segment declined a smaller 3.3% to Rs 531.6 crore from Rs 549.6 crore.
Within the period, Sapala’s nucleic-acid revenue rose 83% year on year, contrasting with the aggregate segment declines. In Q2FY27, Sapala revenue grew 33.6% year on year on demand for specialised nucleic-acid building blocks, with no early Phase III supplies contribution. Management said API+ revenue grew 5% in Q2 on selective pricing actions, but lower volumes, shipment phasing and higher raw-material costs affected that segment’s margins.
Got a follow-up? Ask IRIS
Did Cohance recover in Q2FY27?
Cohance showed sequential recovery in Q2FY27, as revenue rose 12.9% quarter on quarter to Rs 476.7 crore from Rs 422.3 crore in Q1FY27 and adjusted EBITDA rose to Rs 45.8 crore from Rs 9.2 crore. Adjusted EBITDA margin improved to 9.6% from 2.2%, although Q2 revenue remained 14.2% below the Rs 555.6 crore reported in Q2FY26 and the margin remained below 23.2% a year earlier.
Adjusted PAT returned to a profit of Rs 7.5 crore in Q2FY27 after an adjusted loss of Rs 43 crore in Q1FY27. The sequential gain occurred despite Q2 Pharma CDMO revenue being down 27.4% year on year at Rs 167.8 crore and Specialty Chemicals down 40.6% at Rs 41.7 crore. API+ revenue increased 5.0% to Rs 267.1 crore, representing 56% of Q2 revenue, while Pharma CDMO accounted for 35% and Specialty Chemicals 9%.
Cohance generated free cash flow of Rs 88.5 crore during Q2FY27 and had cash and cash equivalents, including liquid investments, of Rs 294.3 crore at 30 September 2026. Gross borrowings were Rs 227.7 crore, leaving net cash of Rs 66.6 crore. The company deployed Rs 108 crore of capital expenditure in H1FY27, equal to 12.0% of revenue for the period.
What does Cohance expect for H2FY27?
Management expects H2FY27 revenue and EBITDA to grow year on year and describes the second half as likely to be stronger than H1FY27. Its stated drivers are Small Molecule deliveries, resilience in API+, Sapala growth, better revenue mix and improved utilisation. In Small Molecules, management said the Q3 and Q4 order and reload position had improved materially, and Cohance had secured two new commercial programmes and one late-stage programme with large global pharmaceutical customers.
Management’s plan is to expand customer participation across the value chain through integrated development-to-manufacturing capabilities, including bioconjugation, antibody-drug conjugate payload-linkers and research-and-development infrastructure. It also said capital investments in adjacent capabilities and research and development would be announced, with spending phased according to customer visibility, project readiness and expected returns. No capex amount or announcement date was disclosed in the presentation.
Conclusion
Cohance’s H1FY27 result shows a substantial earnings deterioration, with revenue down Rs 206 crore year on year, adjusted EBITDA down Rs 207.9 crore and the adjusted margin falling from 23.8% to 6.1%. Pharma CDMO and Specialty Chemicals drove most of the revenue pressure, while API+ had the smallest first-half decline and Sapala’s revenue increased 83%.
The next result will show whether Q2FY27’s recovery, including a 9.6% adjusted EBITDA margin and Rs 7.5 crore adjusted PAT, extends through H2FY27. Management has identified Small Molecule deliveries, API+ resilience, Sapala growth, revenue mix and utilisation as recovery mechanisms, while its proposed capex announcements have no disclosed amount or timetable.