










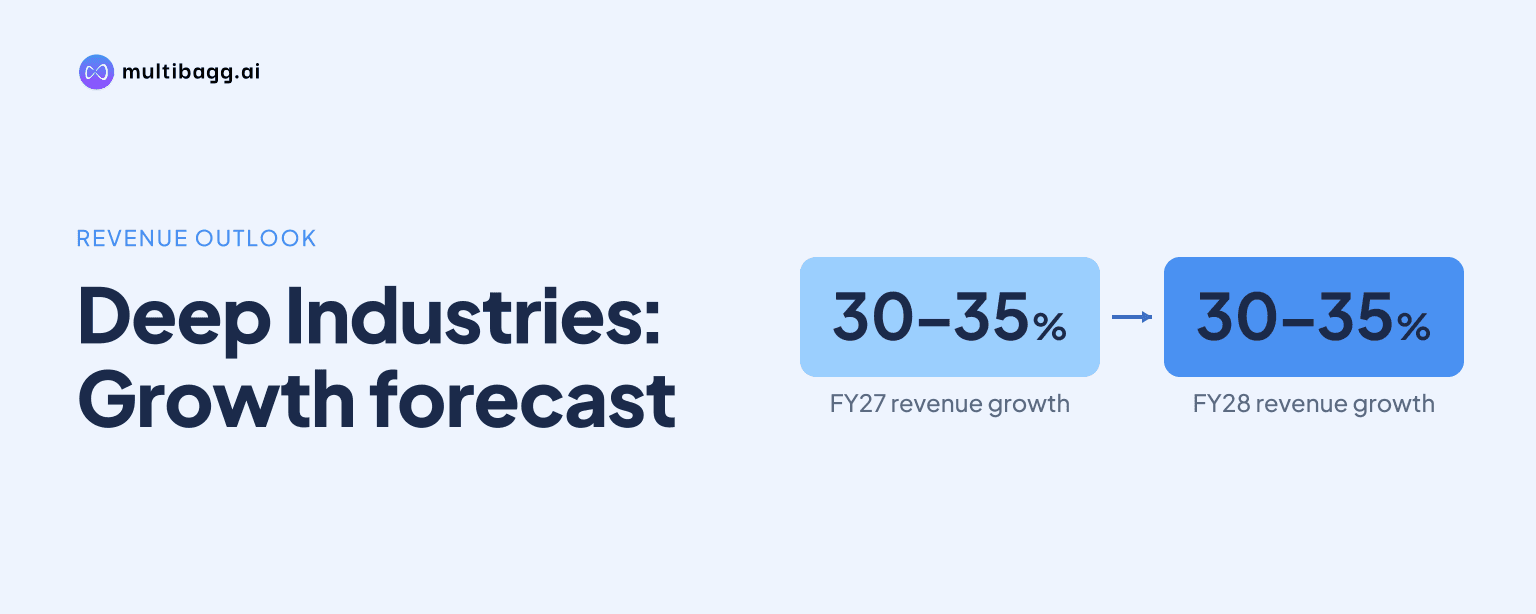
Deep Industries forecasts 30%-35% revenue growth in FY27 and FY28
Key highlights
- Deep Industries guides for 30%-35% operating-revenue growth in FY27 and again in FY28.
- Deep Industries expects FY27 PAT of Rs 350 crore to Rs 370 crore and FY28 PAT of Rs 470 crore to Rs 500 crore.
- Deep Industries' Rs 1,402 crore ONGC contract runs for 15 years, with incremental revenue expected from Q3 FY27.
- H1 FY27 revenue rose 36.6% to Rs 574.34 crore, while EBITDA margin was 41.6% versus 45.7% a year earlier.
powered by IRIS
DEEP Industries Limited expects operating revenue to grow 30%-35% in FY27 and again in FY28, with incremental revenue from its Rs 1,402 crore ONGC production-enhancement contract expected from Q3 FY27. Deep Industries bases FY27 guidance on an approximately Rs 3,089 crore order book and plans about Rs 150 crore of related capital expenditure over the next 12 months.
Know Deep Industries inside out
Results, valuation, peers and who's buying, in one view.
What is Deep Industries guiding for FY27 and FY28?
Deep Industries is guiding for 30%-35% operating-revenue growth in FY27 and a further 30%-35% increase in FY28 over FY27. Management says the FY27 projection is based on its existing Rs 3,089 crore order book, while the FY28 projection draws on the order book and a bidding pipeline of Rs 700 crore to Rs 800 crore.
Deep Industries also expects profit after tax, or PAT, of Rs 350 crore to Rs 370 crore in FY27 and Rs 470 crore to Rs 500 crore in FY28. The midpoint of the stated PAT range rises by Rs 125 crore, from Rs 360 crore for FY27 to Rs 485 crore for FY28, but these are management expectations rather than reported results.
The presentation cautions that forward-looking statements can differ materially from actual outcomes. It identifies factors including earnings fluctuations, the ability to manage growth, domestic and international competition, contract time and cost overruns, regulation, government actions and fiscal costs.
When will the ONGC project contribute to Deep Industries revenue?
Deep Industries expects incremental production under its ONGC production-enhancement contract to begin contributing revenue in Q3 FY27. The contract has a value of Rs 1,402 crore and a 15-year term, and covers comprehensive services intended to boost output from one of ONGC's mature fields.
Under the contract mechanism, Deep Industries expects to enhance hydrocarbon production and extend the life of the mature oil and gas field through advanced techniques, safe operating practices and specialised field equipment. The presentation does not disclose a quarterly revenue value, production target or contract revenue recognition schedule for Q3 FY27.
Deep Industries plans about Rs 150 crore of capital expenditure in the next 12 months to support the production-enhancement project. It also says opportunities to bid for new production-enhancement tenders may arise in H2 FY27, although these opportunities are not disclosed as secured orders.
How does H1 FY27 performance compare with H1 FY26?
Deep Industries reported H1 FY27 revenue of Rs 574.34 crore, up 36.6% from Rs 420.51 crore in H1 FY26. PAT increased 28.2% to Rs 170.37 crore from Rs 132.93 crore, while total income rose 35.2% to Rs 615.62 crore.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 23.1% to Rs 255.83 crore in H1 FY27. The presentation states that EBITDA includes other income, which rose 19.0% to Rs 41.28 crore during the half year.
Operating expenses increased 45.5% to Rs 359.80 crore in H1 FY27, exceeding the 36.6% revenue increase. EBITDA margin was 41.6%, compared with 45.7% in H1 FY26, while PAT margin was 27.7%, compared with 29.2% a year earlier.
Got a follow-up? Ask IRIS
What do Q2 FY27 margins show for Deep Industries?
Deep Industries reported Q2 FY27 revenue of Rs 295.43 crore, a 33.7% increase from Rs 221.01 crore in Q2 FY26. Q2 PAT rose 14.0% to Rs 81.22 crore, compared with Rs 71.23 crore a year earlier.
Q2 FY27 EBITDA increased 9.9% to Rs 124.00 crore, but EBITDA margin declined to 39.6% from 46.6% in Q2 FY26. Operating expenses increased 46.1% to Rs 189.03 crore, while other income declined 17.2% to Rs 17.60 crore.
Finance cost fell 37.9% to Rs 4.04 crore in Q2 FY27 from Rs 6.51 crore in Q2 FY26. Depreciation increased 9.5% to Rs 16.31 crore, and the reported basic and diluted earnings per share rose 13.5% to Rs 11.95.
What order book and operating assets support execution?
Deep Industries reports an approximately Rs 3,089 crore order book and a Rs 700 crore to Rs 800 crore bidding pipeline. Elsewhere, the presentation refers to a revolving order book of more than Rs 3,000 crore, while the Rs 3,089 crore figure is the specific amount management cites in its FY27 guidance.
The presentation does not provide contract-by-contract execution dates, conversion rates for the bidding pipeline or the portion of the order book expected to be recognised in FY27. Deep Industries says it is exploring higher-capacity onshore drilling-rig opportunities through integrated project management services, rather than reporting these opportunities as order wins.
Deep Industries operates 14 workover rigs with capacities ranging from 30 tonnes to 150 tonnes, six drilling rigs with 1,000 horsepower capacity and more than 80 gas compressors. Its integrated project management services cover surface-hole drilling, air drilling, cementing, geophysical logging, hydro fracturing, coiled tubing, well completion and workover operations.
How have Deep Industries' balance sheet and cash metrics changed?
Deep Industries' consolidated total assets were Rs 2,843.94 crore at 30 September 2026, compared with Rs 2,594.99 crore at 31 March 2026. Current assets increased to Rs 1,117.94 crore from Rs 841.38 crore, while current liabilities increased to Rs 391.99 crore from Rs 312.92 crore.
Consolidated equity increased to Rs 2,148.76 crore at 30 September 2026 from Rs 1,999.16 crore at 31 March 2026. Non-current liabilities were Rs 181.54 crore, compared with Rs 169.78 crore six months earlier.
The presentation reports free cash flow of Rs 154.72 crore in FY27, compared with Rs 114.29 crore in FY26. It also shows receivables days at 99 in FY27 versus 131 in FY26, excluding legacy receivables from the Dolphin group, and debt to EBITDA of 0.46 versus 0.48.
Conclusion
Deep Industries has set a two-year operating-revenue growth target of 30%-35%, supported by a Rs 3,089 crore order book and reported H1 FY27 revenue growth of 36.6%. The company reported H1 FY27 PAT growth of 28.2%, while its EBITDA margin declined by 4.1 percentage points to 41.6% as operating expenses increased faster than revenue.
The next disclosed points to watch are the expected Q3 FY27 start of incremental ONGC project revenue, about Rs 150 crore of planned capital expenditure over 12 months and possible production-enhancement tenders in H2 FY27. Management's FY27 PAT expectation of Rs 350 crore to Rs 370 crore and FY28 expectation of Rs 470 crore to Rs 500 crore remain forward-looking targets subject to the risks stated in the presentation.