










Ducol acquisitions expand platform beyond pigment dispersions
Key highlights
- Ducol acquired 100% of Bitumag Industries for Rs 39.7 crore, effective April 15, 2025.
- Bitumag capacity doubled to 10 million square metres per annum after a second manufacturing line was commissioned.
- Ducol's XChem transaction began with Rs 38 crore in cash for a 50.67% stake and includes Rs 30 crore through a share swap.
- Ducol reported H1 FY27 consolidated revenue of Rs 112.26 crore and EBITDA of Rs 12.79 crore.
powered by IRIS
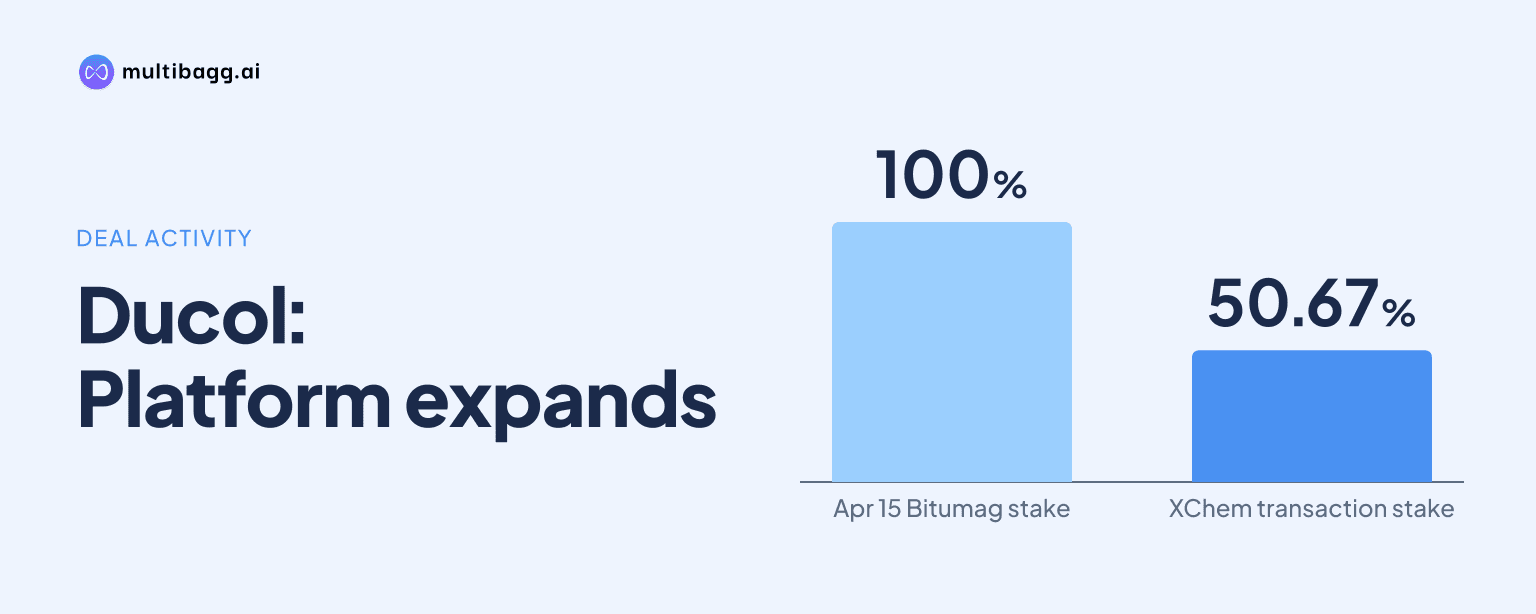
Ducol Organics and Colours Limited expanded beyond pigment dispersions through the April 2025 acquisition of Bitumag Industries and the March 2026 XChem Polymers transaction, adding waterproofing, construction chemicals and industrial adhesives to a business that reported Rs 136 crore of consolidated revenue in FY26.
Know Ducol Organics & Colours inside out
Results, valuation, peers and who's buying, in one view.
How did the acquisitions change Ducol's product platform?
Ducol changed from a pigment-dispersions-only business with Rs 77 crore of standalone FY25 revenue to a multi-vertical specialty-chemicals platform reporting Rs 136 crore of consolidated FY26 revenue. Its current offering combines pigment dispersions with waterproofing, construction chemicals and adhesives, extending its applications from paints, inks, plastics and textiles into concrete, roofing, basements and infrastructure.
The reported revenue change is not a like-for-like growth comparison because FY25 is standalone while FY26 is consolidated. Ducol describes the transition as acquisition-led: Bitumag was acquired in 2025 to establish the non-pigment dispersion business, and XChem was added in 2026 to broaden construction chemicals and industrial adhesives.
Ducol's pigment range includes water-based and solvent-based dispersions, dry dispersions and masterbatches for coatings, detergents, paper and rubber. The acquired portfolio adds Bitumag sheet membranes, liquid-applied waterproofing and elastomeric compounds, alongside XChem admixtures, tile adhesives, sealants and construction additives.
What did Ducol gain from the Bitumag acquisition?
Ducol acquired 100% of Bitumag Industries for Rs 39.7 crore, effective April 15, 2025, giving it a waterproofing platform serving roofing, basements, bathrooms and infrastructure projects. Bitumag's products include membranes and elastomeric compounds, which marked Ducol's stated entry into non-pigment dispersions.
Following the acquisition, Ducol commissioned a second Bitumag manufacturing line and doubled capacity to 10 million square metres per annum. The presentation reports utilisation of 30% to 35% after the expansion and identifies utilisation above 50% as a target, distinguishing the current operating level from management's intended level.
Ducol has allocated 20% of Bitumag capacity to the Southeast Asian market through its Qualibit Chemicals & Industries partnership in Malaysia. The presentation says Polybit, Qualibit's trading and distribution arm, had a sourcing relationship with Bitumag for more than five years before the memorandum of understanding, providing an existing route for the added capacity.
How is Ducol structured to acquire XChem?
Ducol signed a share purchase agreement for XChem Polymers on March 26, 2026, with phase one comprising Rs 38 crore in cash for a 50.67% stake. XChem operates in construction chemicals and industrial adhesives from Pardi, Valsad, Gujarat, and its listed segments include sealants, adhesives, waterproofing chemicals, industrial chemicals and performance adhesives.
Phase two provides for Rs 30 crore through a share swap, while the undisclosed balance of the proposed transaction is to be retained and paid within two years to reach 100% ownership. XChem promoters acquired about 17.65 lakh Ducol shares at Rs 170 per share through the share-swap arrangement, so the disclosed consideration includes cash, equity and a deferred component.
Management said in its H1 FY27 result commentary that XChem was consolidated with Ducol effective May 1, 2026, giving Ducol a 100% controlling stake. The presentation also states that the remaining steps toward 100% ownership are intended to be completed within two years; it does not specify the final balance consideration.
Bitumag and XChem are presented as complementary parts of a waterproofing and construction-chemicals ecosystem. Bitumag supplies waterproofing membranes and elastomeric compounds, while XChem adds adhesives, sealants and construction additives, broadening the categories Ducol can offer to construction and industrial customers.
Got a follow-up? Ask IRIS
Where does Ducol expect commercial synergies?
Ducol expects synergies from cross-selling a wider product range to its combined customer base, using shared capabilities and improving resource utilisation. In H1 FY27, management reported consolidated revenue from operations of Rs 112.26 crore, earnings before interest, tax, depreciation and amortisation (EBITDA) of Rs 12.79 crore, and an EBITDA margin of 11.39%.
The proposed commercial mechanism is to offer Bitumag waterproofing products and XChem construction chemicals to customers that already buy pigment dispersions. Management says this can increase wallet share and generate incremental revenue, but the presentation does not disclose a cross-selling revenue target, customer conversion rate or quantified contribution from the combined product offering.
Operational integration is another stated source of expected benefits. Management cited operational efficiencies and economies of scale, while Bitumag's 10 million-square-metre annual capacity and its more-than-50% utilisation target provide disclosed measures against which that part of the plan can be assessed.
Ducol also links the acquired product range to international expansion. The 20% Bitumag capacity allocation to Southeast Asia is tied to the Malaysia partnership, while XChem's developing Southeast Asia export footprint is described as extending Ducol's geographic reach; no export revenue figure or XChem export target is provided.
What does the acquisition strategy leave to be delivered?
Ducol has established a broader product platform, but its financial outcome depends on completing XChem's ownership path, raising Bitumag utilisation and delivering the cross-selling and efficiency benefits management has identified. The move from Rs 77 crore of standalone FY25 revenue to Rs 136 crore of consolidated FY26 revenue captures the changed reporting perimeter as well as the expanded business scope.
Management says its priorities are strengthening the pigment-dispersion core, realising integration synergies and improving economies of scale. It also says it will explore selective inorganic expansion and strategic partnerships, with profitability as a focus, but the presentation does not provide financial targets for the acquired businesses individually.
Conclusion
Ducol's acquisitions have changed its operating scope from a single pigment-dispersion vertical to a platform spanning pigment products, waterproofing, construction chemicals and industrial adhesives. Bitumag brought a wholly owned waterproofing operation with 10 million square metres of annual capacity, while XChem added complementary products through a staged structure involving Rs 38 crore in cash, Rs 30 crore in share-swap consideration and an undisclosed deferred balance.
The next disclosed milestones are XChem's planned route to 100% ownership within two years and Bitumag's utilisation target of more than 50%, compared with the reported 30% to 35% post-expansion level. Management's planned integration, cross-selling, international partnerships and selective inorganic expansion will determine how the enlarged platform develops.