










Duropack H1 operating EBITDA rises 61% as margin reaches 11.71%
Key highlights
- H1 FY27 revenue from operations increased 36.48% to Rs 25.7279 crore.
- H1 FY27 operating EBITDA excluding other income rose 60.87% to Rs 3.0135 crore.
- Operating EBITDA margin increased 177 basis points year on year to 11.71% in H1 FY27.
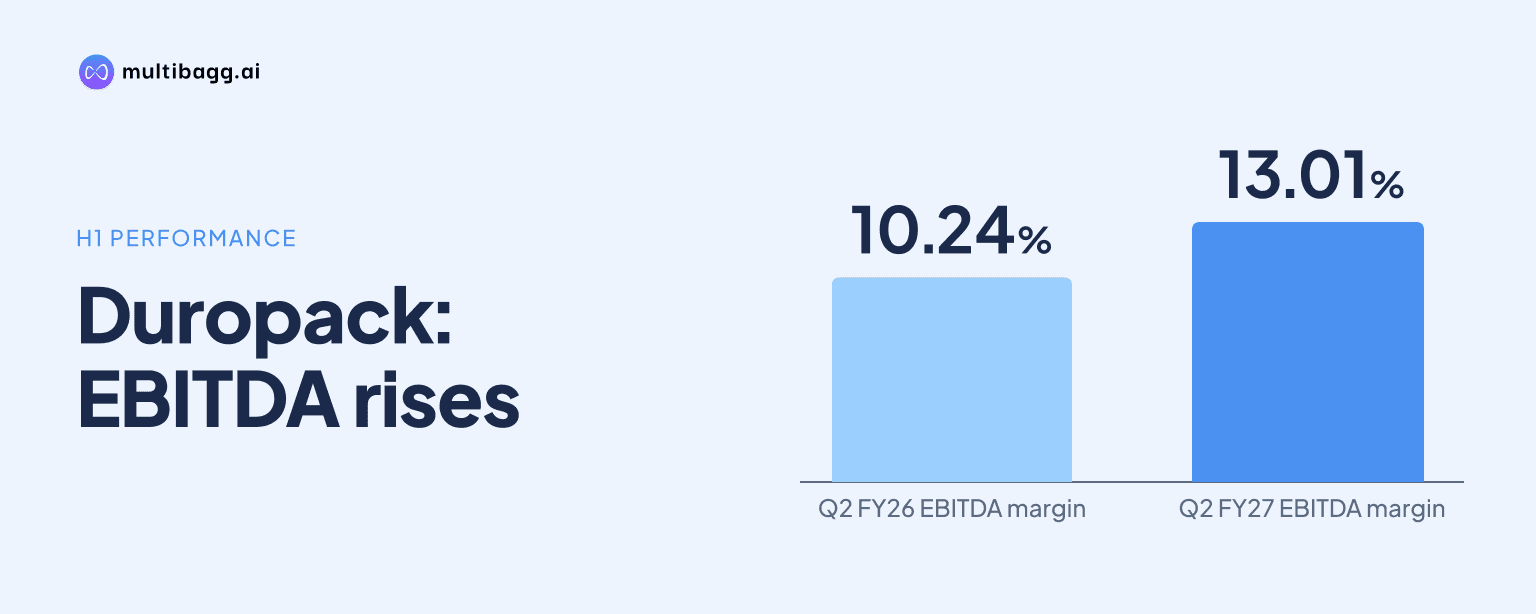
- Q2 FY27 operating EBITDA margin reached 13.01%, versus 10.24% in Q2 FY26.
powered by IRIS
Duropack Limited raised operating EBITDA, excluding other income, 60.87% year on year to Rs 3.0135 crore in H1 FY27, while operating EBITDA margin rose to 11.71% from 9.94% during the six months ended 30 September 2026; revenue from operations grew 36.48% to Rs 25.7279 crore.
Know Duropack inside out
Results, valuation, peers and who's buying, in one view.
How did Duropack perform in H1 FY27?
Duropack reported faster growth in operating EBITDA than in revenue during H1 FY27. Revenue from operations rose from Rs 18.8507 crore in H1 FY26 to Rs 25.7279 crore in H1 FY27, an increase of Rs 6.8772 crore. Operating EBITDA increased from Rs 1.8732 crore to Rs 3.0135 crore, or by Rs 1.1403 crore, representing a 60.87% year-on-year increase.
The operating EBITDA margin increased by 177 basis points, with 100 basis points equal to one percentage point, from 9.94% in H1 FY26 to 11.71% in H1 FY27. Reported profit before tax rose 84.89% to Rs 2.3174 crore from Rs 1.2534 crore. Reported profit after tax increased 85.13% to Rs 1.6584 crore from Rs 89.58 lakh, while basic earnings per share rose to Rs 3.15 from Rs 1.70.
Duropack’s reported H1 FY27 profit before tax of Rs 2.3174 crore reflected Rs 3.0135 crore of operating EBITDA, Rs 6.60 lakh of other income and Rs 76.21 lakh of depreciation and amortisation; finance costs were reported as zero. The presentation defines operating EBITDA as excluding other income, whereas profit before tax and profit after tax are reported figures.
What changed in Duropack’s cost structure?
Duropack’s H1 FY27 EBITDA increase occurred alongside a rise in material costs, its largest listed expense line. Cost of materials consumed increased to Rs 17.6289 crore from Rs 12.3023 crore in H1 FY26, while revenue increased by Rs 6.8772 crore. The presentation identifies polymer resins, packaging films, aluminium foil, printing inks and adhesives as principal material costs in flexible-packaging manufacturing.
Other operating expenses declined to Rs 2.4534 crore in H1 FY27 from Rs 2.8351 crore in H1 FY26, while employee benefit expenses rose to Rs 2.3836 crore from Rs 2.1448 crore. Changes in inventories moved from a negative Rs 30.47 lakh in H1 FY26 to a positive Rs 24.85 lakh in H1 FY27. These movements accompanied the Rs 1.1403 crore increase in operating EBITDA.
Duropack’s disclosed industry cost framework places raw materials at 65% to 70% of flexible-packaging costs, manufacturing and conversion at 10% to 15%, and selling, distribution and administration at 5% to 10%. The stated operating balance is 10% to 20%. This framework identifies input costs and the timing of customer price pass-through as mechanisms that can affect margins.
Crude oil and petrochemical movements can affect the cost of polyethylene, polypropylene, biaxially oriented polypropylene, biaxially oriented polyamide and polyethylene terephthalate, according to Duropack. The company says higher costs of films, resins and other materials can pressure margins when they cannot be fully or immediately passed on to customers.
Got a follow-up? Ask IRIS
How did the second quarter compare with H1 performance?
Duropack’s Q2 FY27 operating EBITDA margin was 13.01%, above both the H1 FY27 margin of 11.71% and the Q2 FY26 margin of 10.24%. Quarterly operating EBITDA rose to Rs 1.8680 crore from Rs 1.0828 crore, an increase of Rs 78.52 lakh. Q2 revenue from operations increased to Rs 14.3560 crore from Rs 10.5768 crore.
The quarterly margin was 277 basis points higher year on year and 130 basis points above the H1 FY27 margin. Reported Q2 profit before tax rose to Rs 1.5296 crore from Rs 74.47 lakh, and reported profit after tax increased to Rs 1.0131 crore from Rs 50.05 lakh. Basic earnings per share for Q2 FY27 was Rs 1.92, compared with Rs 0.95 in Q2 FY26.
Q2 FY27 profit before tax of Rs 1.5296 crore included Rs 1.8680 crore of operating EBITDA, Rs 4.74 lakh of other income and Rs 38.58 lakh of depreciation and amortisation. Finance costs were zero in Q2 FY27, compared with Rs 17,000 in Q2 FY26, according to the quarterly profit and loss statement.
Q2 cost lines show materials consumed at Rs 10.0112 crore, compared with Rs 6.9009 crore a year earlier, while other operating expenses declined to Rs 1.4353 crore from Rs 1.5792 crore. Employee benefit expenses increased to Rs 1.2131 crore from Rs 1.1167 crore. Changes in inventories were negative Rs 17.16 lakh in Q2 FY27, compared with negative Rs 10.28 lakh in Q2 FY26.
How does H1 FY27 fit Duropack’s five-year record?
Duropack reported a 13.4% compound annual growth rate in revenue from operations between FY22 and FY26. Revenue increased from Rs 24.0999 crore in FY22 to Rs 39.8633 crore in FY26. Over the same period, operating EBITDA excluding other income rose from Rs 1.8285 crore to Rs 3.8609 crore, representing the company’s stated 20.5% five-year compound annual growth rate.
Operating EBITDA margin increased from 7.59% in FY22 to 9.69% in FY26, a 210-basis-point expansion, before reaching 11.71% in H1 FY27. The FY26 full-year margin was unchanged from FY25’s 9.69%, whereas the H1 FY27 result was 202 basis points above FY26. This compares a six-month margin with full-year periods and does not establish the FY27 full-year outcome.
Reported profit after tax was Rs 1.8480 crore in FY26, down from Rs 2.3955 crore in FY25, despite revenue increasing from Rs 32.8251 crore to Rs 39.8633 crore. The presentation separately reports adjusted profit after tax excluding other income of Rs 1.7978 crore for FY26, compared with Rs 1.4506 crore in FY25. It states that reported profit after tax includes other income and applicable taxes.
The five-year record also shows operating EBITDA rising in each listed year, from Rs 1.8285 crore in FY22 to Rs 2.8469 crore in FY23, Rs 2.9303 crore in FY24, Rs 3.1800 crore in FY25 and Rs 3.8609 crore in FY26. Revenue also increased in each of those financial years, while the operating EBITDA margin rose from 7.59% to 9.69% and then remained unchanged between FY25 and FY26.
Conclusion
Duropack’s H1 FY27 result showed operating EBITDA growth of 60.87% exceeding revenue growth of 36.48%, lifting the operating EBITDA margin to 11.71%. The Q2 FY27 margin of 13.01% was above both the half-year result and the prior-year quarter, while reported H1 profit after tax rose 85.13% to Rs 1.6584 crore.
The key matter to watch is whether margins remain resilient as crude oil and petrochemical prices affect polymers, films and other materials that Duropack identifies as core flexible-packaging inputs. The company says margins may decline when higher costs cannot be fully or immediately passed through to customers, while its disclosed industry cost framework assigns raw materials 65% to 70% of costs.