










Duroply Industries Limited Reports Record ₹122.2 Crore Q2 Revenue
Key highlights
- Duroply reported record Q2 FY27 revenue of ₹122.2 crore, up 17% year-on-year and 22.7% quarter-on-quarter.
- Q2 FY27 EBITDA rose 33.4% year-on-year to ₹8.62 crore, with margin improving to 7.1% from 6.2%.
- Profit before tax increased 82% year-on-year to ₹4.86 crore, while profit after tax was ₹4.38 crore.
- First-half FY27 revenue was ₹221.9 crore, up 12%, and EBITDA was ₹13.44 crore, up 13.4%.
powered by IRIS
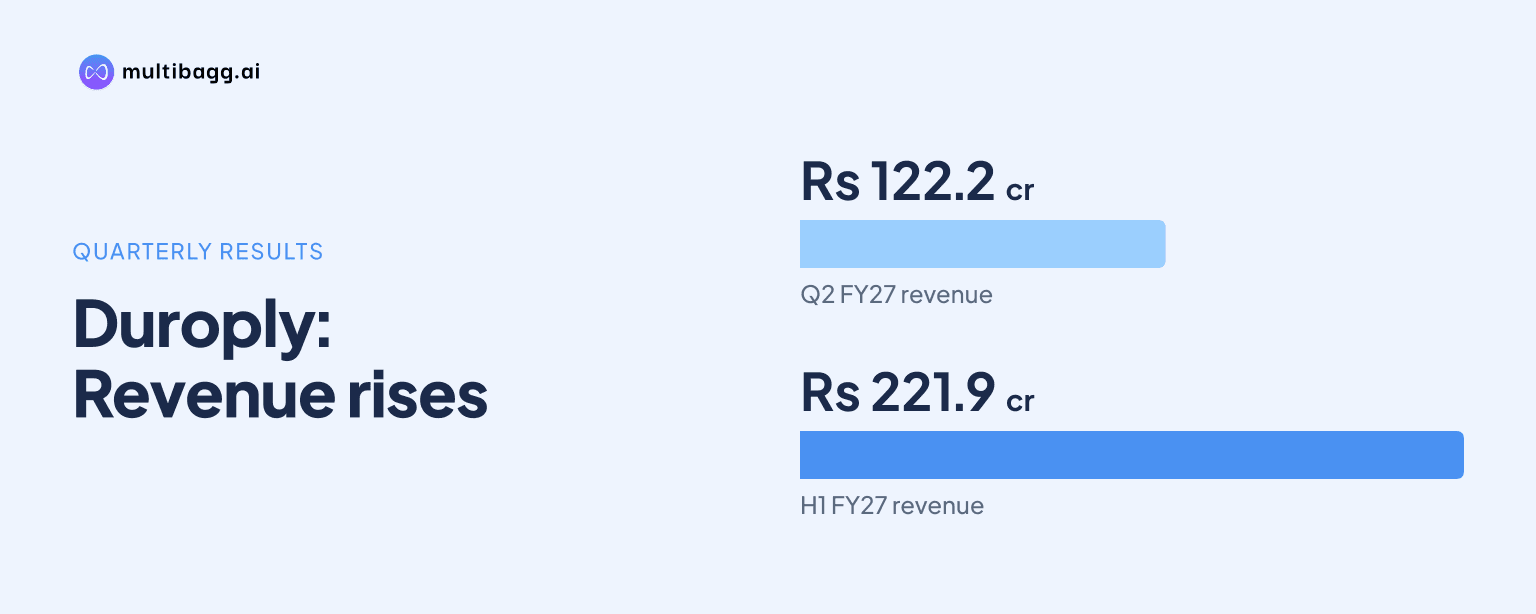
Duroply Industries Limited reported its highest quarterly revenue of ₹122.2 crore in Q2 FY27, up 17% year-on-year and 22.7% sequentially, while EBITDA increased 33.4% to ₹8.62 crore and profit after tax reached ₹4.38 crore.
Know Duroply Industries inside out
Results, valuation, peers and who's buying, in one view.
What did Duroply report for Q2 FY27?
Duroply Industries Limited, referred to hereafter as Duroply, described Q2 FY27 as its strongest quarter so far during its earnings webinar held on November 16, 2026. Revenue reached ₹122.2 crore, exceeding the company’s previous quarterly high of ₹111.6 crore reported in Q4 FY26. The quarter ended September 30, 2026.
The revenue performance represented a recovery from Q1 FY27, when sales were lower. Management said Q2 revenue was 22.7% higher quarter-on-quarter. For the first half of FY27, revenue stood at ₹221.9 crore, up 12% from the corresponding period a year earlier.
Profitability also improved. Profit before tax rose 82% year-on-year to ₹4.86 crore, compared with ₹2.67 crore in Q2 FY26. Profit after tax was ₹4.38 crore. Duroply said the quarter was its most profitable so far, with improved operating leverage contributing to the result.
How did margins and operating costs change?
Duroply’s Q2 FY27 EBITDA rose 33.4% year-on-year to ₹8.62 crore, while the EBITDA margin improved to 7.1% from 6.2% in Q2 FY26 and 4.8% in Q1 FY27. The increase in profitability was faster than the rise in revenue during the quarter.
Gross margin was 34.6%, compared with 34.8% a year earlier and 35.5% in the preceding quarter. While gross margin was marginally below the prior-year level, operating expenses increased 11.3%, lower than the 17% increase in revenue. Operating expenses consequently declined to 27.5% of revenue from 28.9% in the comparable quarter.
For the first half, gross margin improved to 35% from 34.5% a year earlier. Half-year EBITDA was ₹13.44 crore, up 13.4%, with an EBITDA margin of 6.1%. Half-year profit before tax rose 29.5% to ₹5.9 crore.
Why is Duroply adding MDF and HDFMR products?
Duroply said it identified a gap in its offering for home construction and project customers in northern India, where MDF and HDFMR materials are used at many sites. Management said it introduced only its high-density Zero HD MMR HDFMR line to address that product requirement.
The company said it is using a partner’s existing manufacturing capacity for the MDF and HDFMR offering. This approach allows Duroply to add the category without undertaking the associated manufacturing cost, at a time when management noted industry overcapacity.
Management linked the product addition to Duroply’s established retail-brand presence in northern India. The strategy is intended to complement the company’s existing portfolio and serve customers who require these materials alongside other wood-panel products. The call did not provide sales contribution, capacity, pricing, or volume details for the new line.
Got a follow-up? Ask IRIS
What cost risks did management identify?
Management’s outlook was positive on the second-half demand trend, stating that it expects H2 FY27 to be stronger than H1 FY27. However, it also identified raw-material, chemical, and shipping costs as areas of uncertainty.
The company said it was not certain how much of these higher costs could be passed on to customers. This matters because the Q2 improvement was supported by higher sales volumes and overheads that remained comparatively contained. Any material change in input costs or pricing could affect future margins, although no financial guidance was provided on the call.
Duroply’s national distribution reach is also relevant to this assessment. As of March 31, 2026, it reported operations across more than 26 states and union territories through over 20 offices. This network supports market access but can also expose operations to changes in freight and logistics costs.
How does the Q2 result matter for investors and the wood-panel sector?
The Q2 result shows that Duroply achieved stronger operating leverage as revenue rose faster than operating expenses. EBITDA growth of 33.4% outpaced the 17% increase in revenue, lifting the EBITDA margin by 0.9 percentage points from the year-earlier quarter.
For investors, the key reported figures are the record ₹122.2 crore revenue, the ₹8.62 crore EBITDA, and the ₹4.38 crore profit after tax. The result also follows a weaker Q1, making the sequential 22.7% growth in revenue and 79% rise in EBITDA significant in the context of the first half.
The MDF and HDFMR initiative indicates Duroply is broadening its product portfolio through partner capacity rather than a stated manufacturing investment. Its ability to sustain profitability will depend on demand, input-cost movements, and the extent to which any cost increases can be reflected in selling prices.
Conclusion
Duroply’s Q2 FY27 performance combined record quarterly revenue with faster growth in EBITDA and profit before tax. Revenue of ₹122.2 crore, EBITDA of ₹8.62 crore, and a 7.1% EBITDA margin reflect the benefits of higher volumes and operating-cost discipline, despite gross margin being below the prior-year level.
The next area to watch is Duroply’s H2 FY27 performance, which management expects to be stronger than H1. Investors will also monitor the impact of rising raw-material, chemical, and shipping costs, the company’s ability to pass these costs to customers, and the progress of its MDF and HDFMR product offering.