










Embassy REIT expects cash tax near 5% of revenue for two years
Key highlights
- Embassy REIT expects cash tax of about 5% of revenue for the next one to two years, versus an earlier estimate of around 6%.
- The lower outlook follows Rs 601.5 crore of recognised MAT credits and lower MAT incidence.
- Embassy REIT has about Rs 4,000 crore of refinancing due in FY2027, with Rs 1,100 crore already refinanced.
- Management targets 92%-93% occupancy by area by the financial year-end, compared with 90% currently.
powered by IRIS
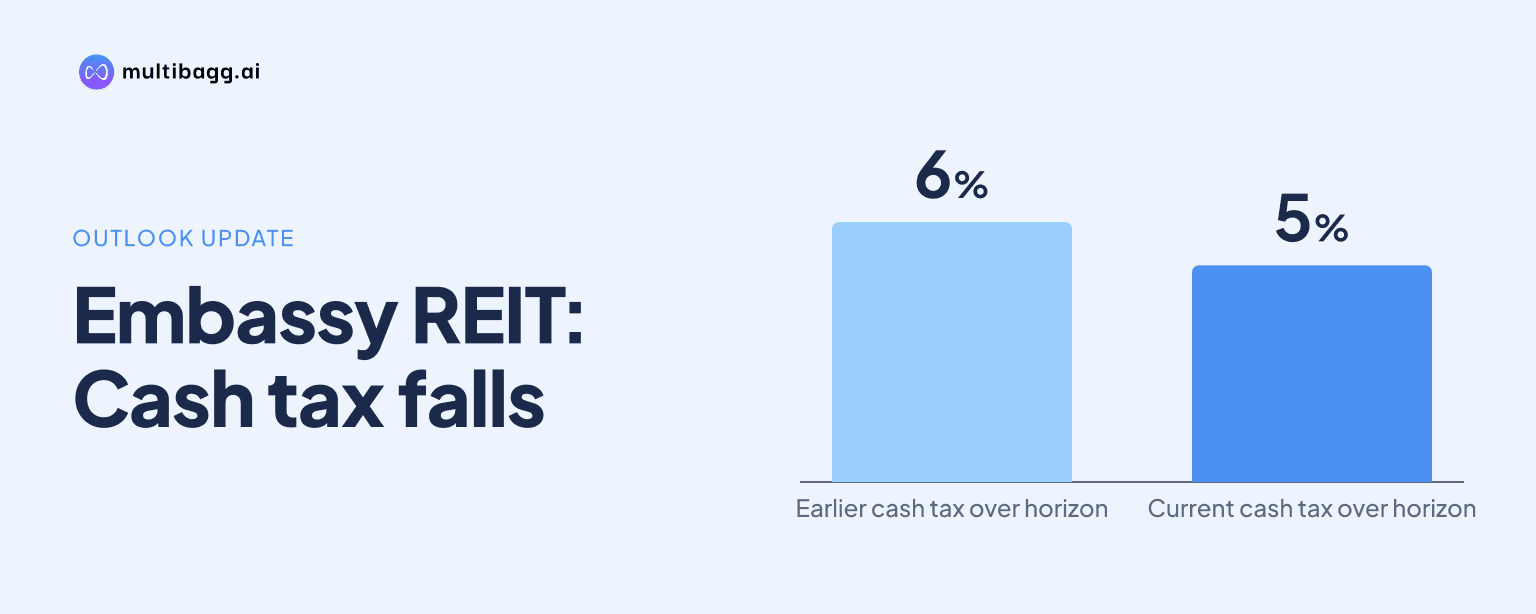
Embassy REIT expects cash tax to equal about 5% of revenue for the next one or two years, versus its earlier estimate of about 6%, management said during the earnings-call question session. The lower forecast follows tax-law changes, including recognition of Rs 601.5 crore in minimum alternate tax, or MAT, credits and lower MAT incidence.
Know Embassy Office Parks REIT inside out
Results, valuation, peers and who's buying, in one view.
What cash-tax rate does Embassy REIT expect?
Embassy REIT expects cash tax to be about 5% of revenue for the next one or two years. Abhishek Agrawal said the revised estimate was lower than the earlier expectation of around 6% of revenue when answering an analyst's question on whether the tax burden would fall after recent tax changes.
The update reduces the expected cash-tax rate by about 1 percentage point, from around 6% to around 5% of revenue. Management did not provide a quarterly cash-tax forecast, a revenue assumption behind the 5% estimate or a separate outlook beyond the next one or two years, so the disclosed forecast is a revenue ratio rather than a fixed rupee outflow.
How do tax-law changes alter Embassy REIT's cash tax?
Embassy REIT linked its lower cash-tax outlook to Rs 601.5 crore of recognised MAT credits and lower MAT incidence. MAT is the minimum alternate tax mechanism referred to in the material, but management did not detail the tax-law provisions, the timing of credit utilisation or a year-by-year schedule for the credits.
An analyst cited potential annual cash-tax savings of Rs 120 crore to Rs 130 crore while asking whether the previous 5%-6% tax-rate range would change. Management answered that cash taxes should be closer to 5% of revenue, but did not separately confirm the Rs 120 crore to Rs 130 crore figure or provide a bridge from the Rs 601.5 crore MAT-credit recognition to annual savings.
That distinction separates the reported accounting recognition from future cash-tax expectations. The clearest management forecast is the roughly 5% share of revenue for the next one or two years, while the actual rupee outflow will depend on revenue during those periods and the use of available tax credits.
What other cash demands could affect Embassy REIT's outlook?
Embassy REIT said capital expenditure on 5.6 million square feet, or msf, under development should keep leverage at around 30% for the next couple of quarters. Management expects leverage to decline to around 28%-29% during financial year 2029, or FY2029, after that development spending, while seeking to keep leverage below 30%.
Debt refinancing is another cash-flow variable. Embassy REIT said about Rs 4,000 crore of refinancing was due in FY2027, of which Rs 1,100 crore had already been refinanced and about Rs 1,450 crore had been tied up. Management said the remaining refinancing was due toward March 2027.
For the following year, Embassy REIT cited around Rs 4,200 crore of maturing debt, most of it fixed-rate debt with an average interest rate of about 7.5%. Management's guidance was that this year's interest cost could be about 11%-13% higher than the previous year, even if there were one or two interest-rate increases of 25 basis points each.
Management estimated that a 25-basis-point increase in floating-rate borrowing costs would raise annual interest cost by around Rs 20 crore. A basis point is one-hundredth of a percentage point. For the Rs 4,200 crore of fixed-rate debt maturing next year, management estimated that refinancing at a 25-basis-point higher rate would add about Rs 8 crore annually.
Got a follow-up? Ask IRIS
How does leasing performance frame Embassy REIT's cash-tax forecast?
Embassy REIT reported 90% occupancy by area and is targeting 92%-93% by the financial year-end, including its Pune portfolio. Revenue and cash collections can be affected by the timing of occupancy gains, while management said cash rent at the newly delivered 0.6 msf block at Embassy Splendid TechZone in Chennai should begin sometime next year.
Management said Embassy REIT has a leasing pipeline of about 1.4 msf across the country. It also disclosed a 0.5 msf pre-leasing transaction with an existing tenant that was agreed at a 15% premium to current market rents, indicating that lease economics and occupancy are separate factors from the revised tax-rate assumption.
Rental rates were firming by 5%-10% across the country, according to management, with key active micro-markets recording growth of about 10%. Management highlighted Hyderabad's HITEC City, where rentals had almost doubled over the past two years, and said Bengaluru's Outer Ring Road and Whitefield markets had shown similar trends.
At Embassy Manyata, management said it was adopting a rate strategy as occupancy increased, rather than prioritising volume alone. It cited a pipeline containing demand from existing occupiers and new tenants, while noting that national gross leasing absorption was about 66 msf in the first nine months, including about 21 msf in the quarter.
What could determine whether Embassy REIT reaches its outlook?
Embassy REIT's 5% cash-tax expectation depends on the next one or two years rather than a single quarter, so reported revenue and tax payments will show how the forecast develops. The company did not disclose a fixed revenue target against which investors could calculate the cash-tax amount, making the percentage of revenue the relevant management measure.
The development programme adds a timing consideration. Management expects leverage to remain around 30% over the next couple of quarters because of spending on 5.6 msf, before moving toward 28%-29% in FY2029. This means lower cash-tax incidence would operate alongside development expenditure and refinancing requirements.
Occupancy progress also remains relevant because management is aiming for 92%-93% by the financial year-end from 90% currently. The expected start of cash rent next year at the 0.6 msf Chennai block and the 1.4 msf leasing pipeline could affect revenue timing, which in turn affects the rupee value of a tax charge set at about 5% of revenue.
Conclusion
Embassy REIT has reduced its expected cash-tax rate to about 5% of revenue from around 6% for the next one or two years. The stated change follows Rs 601.5 crore of recognised MAT credits and lower MAT incidence, although management did not provide a detailed reconciliation to the Rs 120 crore to Rs 130 crore annual savings cited by an analyst.
The next disclosures to watch are cash-tax payments against the 5% outlook, progress on 5.6 msf of development spending and refinancing of Rs 4,000 crore due in FY2027. Management also targets 92%-93% occupancy by the financial year-end and expects leverage to remain near 30% for the next couple of quarters before declining toward 28%-29% in FY2029.