










Embassy REIT says FY27 interest guidance withstands two hikes
Key highlights
- Embassy REIT said FY2027 interest-cost growth can remain within 11% to 13% after up to two further 25-basis-point RBI hikes.
- About Rs 4,000 crore requires refinancing in the balance of FY2027, including Rs 1,100 crore completed and nearly Rs 1,450 crore tied up.
- Embassy REIT had Rs 22,389 crore of net debt at September 2026, with 57% fixed-rate debt and a 7.33% in-place cost.
- Embassy REIT raised Rs 2,050 crore in Q2 FY2027 at a 7.14% blended annual interest rate.
powered by IRIS
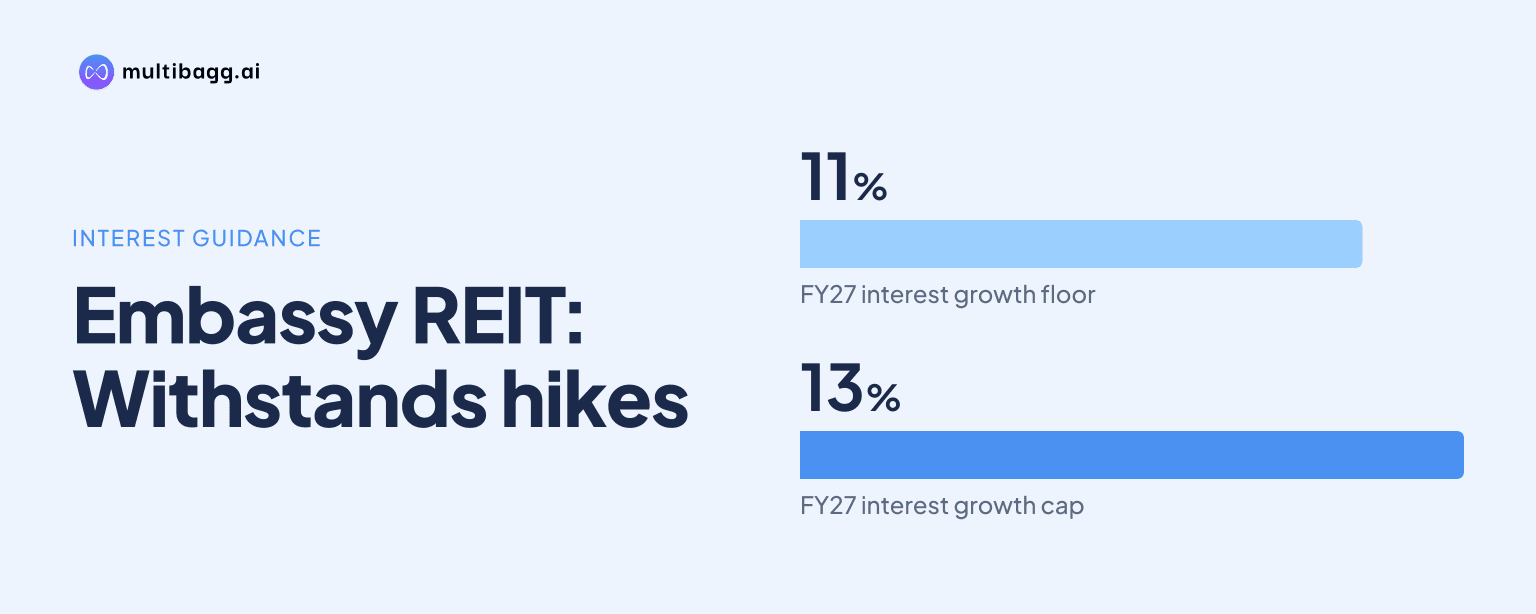
Embassy REIT said on its Q2 FY2027 call that FY2027 interest-cost growth should remain within 11% to 13% year on year even if the Reserve Bank of India raises rates once or twice more by 25 basis points, because much of its remaining Rs 4,000 crore FY2027 refinancing had been completed or tied up.
Know Embassy Office Parks REIT inside out
Results, valuation, peers and who's buying, in one view.
Can Embassy REIT absorb two further RBI rate hikes?
Yes. Embassy REIT Chief Financial Officer Abhishek Agrawal said the REIT should remain within its FY2027 interest-cost guidance of 11% to 13% growth over the previous year if there are one or two additional 25-basis-point rate hikes. The guidance concerns annual interest-cost growth, not an absolute borrowing-cost target.
Management based that view on the maturity schedule from Q2 FY2027 onward. About Rs 4,000 crore required refinancing during the remainder of FY2027, of which Rs 1,100 crore had already been refinanced. Nearly Rs 1,450 crore more had been tied up and was expected to be available within a week, according to Agrawal.
The remaining portion of the roughly Rs 4,000 crore requirement matures at the end of the financial year, in March 2027. Agrawal said that timing would limit the impact of a further repo-rate increase on FY2027 interest costs. This is management guidance based on its stated assumptions, rather than an assurance of the eventual expense.
What debt has Embassy REIT raised and tied up?
Embassy REIT raised Rs 2,050 crore of debt in Q2 FY2027 at a blended annual interest rate of 7.14%, which management said was 18 basis points below the Q1 in-place debt cost. One basis point equals one-hundredth of a percentage point, making the stated difference 0.18 percentage points.
The Q2 borrowing included a Rs 1,000 crore, three-year floating-rate non-convertible debenture, or NCD, with an initial coupon of 6.97%. A leading multinational bank fully subscribed to the NCD. Management said it was the first financing by a scheduled commercial bank to an Indian real estate investment trust, or REIT, at the trust level under the Reserve Bank of India’s new framework.
The Rs 1,100 crore already refinanced and the nearly Rs 1,450 crore tied up total roughly Rs 2,550 crore. That represents about 64% of the approximately Rs 4,000 crore refinancing requirement management identified for the balance of FY2027. Management expected the tied-up Rs 1,450 crore to be deployed for refinancing after receipt.
How much fixed-rate debt does Embassy REIT have?
Embassy REIT had 57% of its debt locked at fixed rates as of September 2026. Net debt was Rs 22,389 crore at September-end, with a 30% leverage ratio and an in-place cost of 7.33%.
The 7.14% blended rate on Rs 2,050 crore raised in Q2 FY2027 was below the 7.33% in-place debt cost at September-end. However, the Rs 1,000 crore NCD within that fundraising was floating-rate and its 6.97% coupon was specified as an initial rate, leaving that portion exposed to changes in benchmark rates.
Management also identified about Rs 4,200 crore of maturities in the following year. Most of that debt is fixed-cost, with an average interest rate of around 7.5%, according to Agrawal. The transcript does not quantify the annual interest-expense effect of each 25-basis-point policy-rate move, limiting the disclosed sensitivity analysis to FY2027 guidance.
Got a follow-up? Ask IRIS
What does the interest-cost outlook mean for distributions?
Higher interest expense partly offset operating growth in Q2 FY2027, when Embassy REIT declared Rs 670 crore of distributions, or Rs 7.07 per unit, up 9% year on year. Net operating income, or NOI, rose 15% to Rs 1,069 crore during the same quarter.
Revenue increased 16% year on year to Rs 1,303 crore in Q2 FY2027, driven by leasing momentum, rent growth and additions of office and hotel buildings to the operating portfolio. Management said the distribution increase was lower than NOI growth because higher interest expenses partly offset the property-level income increase.
For FY2027, Embassy REIT retained NOI guidance of Rs 4,150 crore to Rs 4,350 crore and distribution per unit, or DPU, guidance of Rs 27.00 to Rs 28.60. At the midpoint, management said this implies 13% year-on-year NOI growth and 10% DPU growth. Its stated interest-cost assumption, including up to two further 25-basis-point hikes, is embedded in those retained ranges.
What operating factors could support Embassy REIT’s guidance?
Embassy REIT reported 90% portfolio occupancy as of September 2026 and retained its target to end FY2027 with occupancy of 92% to 93% by area, including Pune. New leases signed in Q2 FY2027 were at an average 9% premium to market rents, while portfolio market rents rose 8% year on year to Rs 106 per square foot.
The REIT leased 1.5 million square feet in Q2 FY2027, comprising 0.9 million square feet of new leases, 0.1 million square feet of renewals and 0.5 million square feet of pre-leasing. The Embassy TechVillage full-building pre-lease was signed at a 15% premium to current market rents.
Embassy REIT’s development pipeline stood at 5.6 million square feet across Bengaluru and Chennai, with 2.3 million square feet scheduled for delivery over the next two years and 67% already pre-leased, including expansion options. Management said leverage would hover around 30% over the next couple of quarters because of capital expenditure on this development pipeline.
Management expects leverage to decline to around 28% to 29% sometime in FY2029, while maintaining it below 30%. It also expects annual cash-tax savings of around Rs 120 crore to Rs 130 crore after an income-tax-law amendment, with cash taxes closer to 5% of revenue versus its previous estimate of around 6%.
Conclusion
Embassy REIT’s FY2027 interest-cost position rests primarily on refinancing execution and maturity timing. Management has already refinanced Rs 1,100 crore, tied up nearly Rs 1,450 crore more, and said the residual FY2027 maturity falls in March 2027. That schedule underpins its view that interest-cost growth can stay within 11% to 13% even after up to two further 25-basis-point rate increases.
The next points to watch are the receipt and deployment of the nearly Rs 1,450 crore tied-up refinancing, terms achieved on the March 2027 balance, and the subsequent Rs 4,200 crore maturity, most of which is fixed-rate at around 7.5%. Embassy REIT’s retained FY2027 NOI guidance of Rs 4,150 crore to Rs 4,350 crore and DPU guidance of Rs 27.00 to Rs 28.60 are the disclosed operating benchmarks for the year.