










Endurance H1FY27 income climbs 38% as margin drops to 10.8%
Key highlights
- Endurance standalone H1FY27 total income rose 38% to Rs 6,955 crore.
- Endurance standalone H1FY27 EBITDA margin declined to 10.8% from 12.7%.
- Endurance said last year’s metal prices would have lifted H1FY27 EBITDA margin by 120 basis points.
- Endurance reported 78% associated income growth in scooters, versus 31.1% industry scooter-volume growth.
powered by IRIS
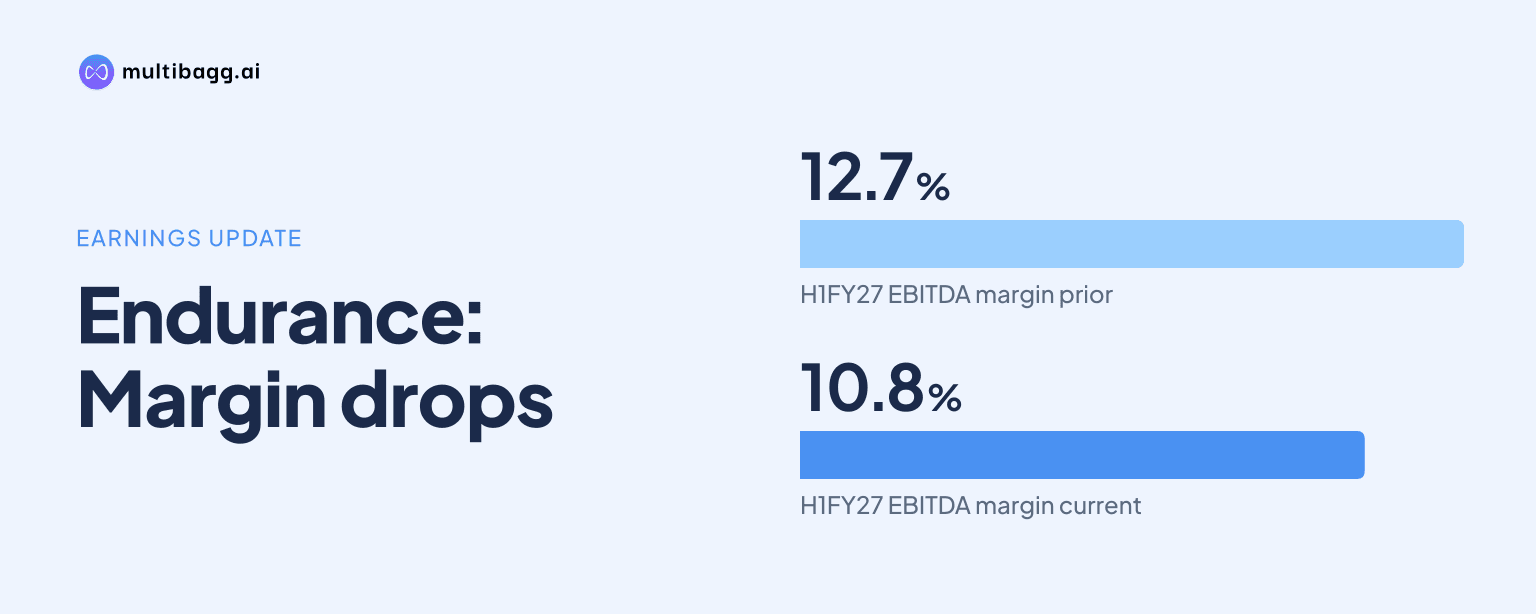
In H1FY27, Endurance reported 38% year-on-year standalone total-income growth to Rs 6,955 crore, while earnings before interest, tax, depreciation and amortisation (EBITDA) margin fell 190 basis points to 10.8%; management said last year’s metal prices would have added 120 basis points.
Know Endurance Technologies inside out
Results, valuation, peers and who's buying, in one view.
Why did Endurance’s H1FY27 standalone income increase 38%?
Endurance’s standalone total income increased by Rs 1,912 crore, from Rs 5,043 crore in H1FY26 to Rs 6,955 crore in H1FY27. The 38% increase exceeded the 21.8% growth in total Indian vehicle sales, which rose to 19.81 million units from 16.32 million units, according to Society of Indian Automobile Manufacturers data presented by Endurance.
The H1FY27 total-income figure included Rs 75 crore of incentive booked during the period. EBITDA increased by Rs 110 crore to Rs 752 crore from Rs 642 crore, a 17% rise that was below income growth, while profit after tax (PAT) rose 16%, or Rs 55 crore, to Rs 408 crore and its margin fell to 5.9% from 7.0%.
What explains Endurance’s H1FY27 EBITDA margin decline?
Endurance’s H1FY27 standalone EBITDA margin was 10.8%, down from 12.7% in H1FY26, and management said the margin would have been 120 basis points higher if metal prices had remained at last year’s levels. A basis point is one-hundredth of a percentage point, making the disclosed metal-price sensitivity equivalent to 1.2 percentage points of margin.
The period comparison shows that operating profit did not rise at the same rate as income: EBITDA rose 17% while total income rose 38% in H1FY27. The same pattern appeared in Q2FY27, when standalone total income grew 40% to Rs 3,761 crore and EBITDA increased 18% to Rs 395 crore, with the EBITDA margin declining to 10.5% from 12.5% in Q2FY26.
Endurance booked Rs 40 crore of incentive in Q2FY27, compared with the Rs 75 crore booked over H1FY27. The presentation does not provide an absolute metal-cost number or identify individual metals, but management’s 120-basis-point sensitivity directly quantifies the difference that last year’s metal-price levels would have made to the reported H1FY27 margin.
Got a follow-up? Ask IRIS
Which Indian vehicle segments outpaced their industry volumes for Endurance?
Scooters and four-wheelers had the largest gaps between Endurance’s associated income growth and industry-volume growth in H1FY27. Scooter sales increased 31.1% to 5.30 million units while Endurance’s associated total-income growth was 78%, and total four-wheeler sales grew 24.4% to 3.74 million units while the associated income-growth rate was 48%.
Motorcycles remained the largest two-wheeler category by volume, with sales rising 15.8% to 9.69 million units from 8.37 million units in H1FY26. Endurance reported 32% associated income growth for motorcycles, while total two-wheeler sales rose 20.7% to 15.29 million units and the associated Endurance income-growth rate was 39%.
Three-wheeler sales increased 32.6% to 0.81 million units in H1FY27 from 0.61 million units a year earlier, and Endurance reported 32% associated income growth in that category. Across all vehicle categories, Endurance’s 38% standalone income growth was 16.2 percentage points above the 21.8% growth in industry sales, although the presentation does not disclose segment revenue in rupees.
How did Endurance’s Europe and Maxwell businesses perform in H1FY27?
Endurance’s Europe business reported H1FY27 total income of Rs 2,175 crore, up 14% from Rs 1,910 crore, or 3% in euro terms. Its EBITDA increased 17% to Rs 391 crore and the margin rose to 18.0% from 17.6%, contrasting with the 190-basis-point decline in the standalone EBITDA margin.
Europe PAT rose 2% to Rs 105 crore from Rs 103 crore in H1FY26. Endurance said accelerated depreciation relating to original equipment manufacturer programmes being phased out amounted to Rs 54 crore, partly offset by a Rs 36 crore gain from acquisition accounting; EU new-car registrations grew 6.6% to 5.694 million units but remained 13.4% below H1FY19.
Maxwell recorded H1FY27 total income of Rs 141 crore, up 91% from Rs 74 crore, while EBITDA increased to Rs 10 crore from Rs 3 crore. Its EBITDA margin rose to 6.8% from 3.4%, and PAT moved to Rs 5 crore from a Rs 3 crore loss; Maxwell also won Rs 53 crore of orders in H1FY27 for battery-management-system variants and related products.
Conclusion
The H1FY27 disclosures show Endurance’s Indian business growing faster than the 21.8% increase in total vehicle sales, with scooters and four-wheelers showing the widest reported differences between associated income growth and underlying volumes. However, standalone EBITDA growth of 17% trailed the 38% rise in income, while Europe delivered 3% growth in euro terms and a 40-basis-point improvement in EBITDA margin.
The next disclosed operating milestones are at Maxwell, where two-wheeler battery-pack dispatches commenced and full ramp-up is scheduled for Q3 FY27. Maxwell has also received nominations from two original equipment manufacturers for four-wheeler battery packs, with start of production expected in H1FY28, while Endurance’s disclosed 120-basis-point metal-price sensitivity remains relevant to the next standalone margin comparison.