










Fredun Pharmaceuticals FY27 Trends 15%-20% Above Earlier Plan
Key highlights
- Fredun Pharmaceuticals said FY27 performance is trending 15% to 20% above earlier projections.
- Management said Pet Care and mobility ARR are in line with plan and expected to overachieve.
- Fredun Pharmaceuticals said existing businesses are growing 15% to 20% annually, while new-age operations are growing about 65% to 70%.
- The company said its portfolio has almost 2,400 products and its order book extends seven to eight months.
powered by IRIS
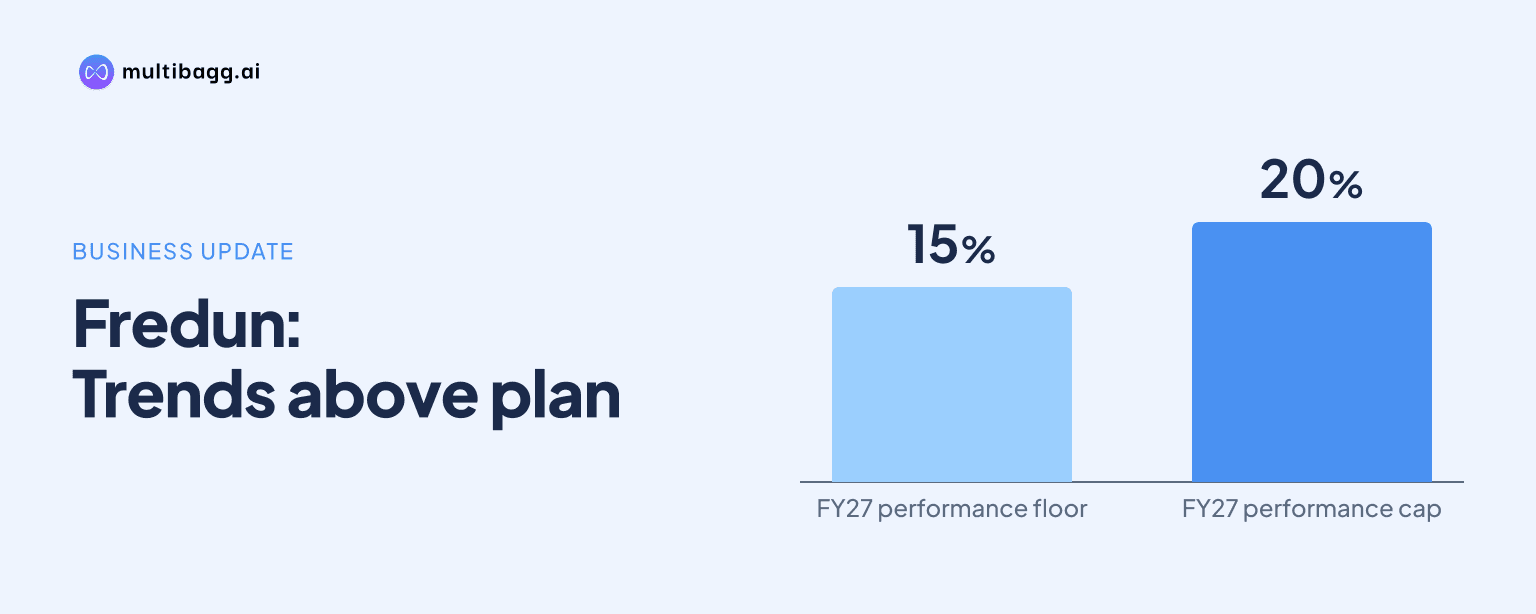
Fredun Pharmaceuticals Limited said FY27 performance is trending 15% to 20% above earlier projections, as annual recurring revenue in Pet Care and mobility is at or above plan and vintage formulations are also ahead. Management cited faster H1 growth in both businesses but gave no absolute FY27 revenue or profit forecast.
Know Fredun Pharmaceuticals inside out
Results, valuation, peers and who's buying, in one view.
Why does Fredun Pharmaceuticals expect FY27 outperformance?
Fredun Pharmaceuticals expects to outperform its earlier FY27 projections by 15% to 20% based on its current trend, according to Fredun Medhora. He said annual recurring revenue, or ARR, in Pet Care was in line with the earlier projection, mobility was also in line, and both were expected to overachieve. Vintage-business ARR was also better, which management said was raising the overall ARR trend.
The statement is directional rather than numerical guidance. Management explicitly said it would not comment on absolute numbers, so the call does not establish a revenue, profit or ARR base, or the exact benchmark for the additional 15% to 20%. The management explanation nevertheless points to three contributors, Pet Care, mobility and vintage formulations, rather than a single new business.
The H1 discussion provided supporting context. An investor described company-level growth as 90%, and management replied that formulations had grown faster during the year than its usual 15% to 20% range. Management linked first-quarter vintage-business growth to order flow during a volatile situation, saying Fredun Pharmaceuticals had held sufficient stock and was relatively unaffected by price increases.
Which businesses are contributing to Fredun Pharmaceuticals' growth?
Fredun Pharmaceuticals says legacy formulations and new-age operations are both contributing to growth, although their contributions differed between the first and second quarters. Management said the vintage business made a substantially larger contribution in the first quarter. In the second quarter, it said almost 30% to 40% of growth came from new-age activities, including new Pet Care and mobility territories and functional-food orders.
Management also referred to another 25% to 30% of growth from new-age activities, but it did not provide a reconciled segment bridge. Those percentages cannot therefore be added together as separately confirmed shares of company growth. The call's clearest conclusion is that territory additions and third-party functional-food work supported the new-age contribution during the second quarter.
Over a longer horizon, management gave different underlying growth expectations for the two groups. It said existing businesses were on an annual growth rate of 15% to 20% and expected that pace for the next seven to eight years, based on its current actions and direction. New-age businesses were described as growing about 65% to 70% year on year, although management cautioned that territory additions could result in triple-digit growth in some years and below-60% growth in others.
Got a follow-up? Ask IRIS
What is supporting Fredun Pharmaceuticals' profitability trajectory?
Fredun Pharmaceuticals attributes its profitability trajectory to a wider portfolio, selective order acceptance and operatingly profitable new-age businesses. Management said it had almost 2,400 products, enabling it to decline low-yielding products when cost efficiencies did not meet expectations. It also said its order book extended seven to eight months into the future, allowing the vintage operation to select more profitable work.
An investor said profit after tax, or PAT, margin had reached about 7% and asked whether a larger new-age contribution had driven the expansion. Management responded that newer businesses were operatingly profitable and contributed to both revenue and profit, while efficiencies were beginning to emerge in established operations. Fredun Pharmaceuticals did not provide a margin target for the next year or say that the approximately 7% PAT margin was sustainable.
Management said margins may vary by quarter as expansion proceeds. When Fredun Pharmaceuticals enters a new state with a division, it may spend during the launch quarter; management said that investment could fructify in the following three quarters for that state. It described established states as more cost-efficient, making the mix of new and mature territories relevant to interim profitability.
What could determine whether Fredun Pharmaceuticals delivers the higher trend?
Fredun Pharmaceuticals' ability to deliver 15% to 20% outperformance depends partly on execution across seven verticals, according to management. It said even Rs 500 crore of revenue growth across those verticals equates to about Rs 65 crore to Rs 70 crore of annual growth per vertical. Management argued that dividing the target by states and businesses made it achievable, while acknowledging that registrations and processes affect expansion timing.
The company named mobility, Pet Care, dermaceutics, nutraceuticals, Fredun Gx and supplies to existing export markets as growth drivers. Management said it had completed 11 years of research on herbal nutraceutical products and conducted light clinical trials on nutraceutical offerings before launch. It also said a competitor could replicate a factory with about Rs 400 crore of investment, but claimed comparable licences could take 15 to 16 years, which is management's assessment rather than an independently verified barrier.
Launch execution is another near-term variable. Management said the CAT business was expected to launch in about 60 to 90 days, around January 2027, while the Daulcél anti-ageing line and hormonal line were in the launch phase. It expected anti-ageing products to reach metros in about six to 18 months and said hormonal products would be sold nationally. No FY27 sales or profitability contribution was disclosed for these launches.
Conclusion
Fredun Pharmaceuticals' central message is that FY27 is tracking 15% to 20% above earlier projections because vintage formulations are growing faster than their usual range while Pet Care and mobility are meeting or exceeding ARR plans. Management also described new-age operations as operatingly profitable, framing the higher trend as a combination of growth, product selection and operating efficiencies.
The next points to watch are delivery on the 60-to-90-day CAT launch timetable, the anti-ageing rollout over six to 18 months, and whether new-state investment begins to yield results over the following three quarters as management indicated. Future disclosures will also be needed to establish the absolute revenue and profit implications of the 15% to 20% outperformance trend.