










GCM H1 EBITDA more than doubles as margin reaches 11.4%
Key highlights
- GCM Sep-26 half-year revenue rose 25.9% to Rs 1,180.1 crore.
- GCM Sep-26 half-year operational EBITDA rose 115.9% to Rs 134.1 crore.
- GCM’s Sep-26 half-year EBITDA margin increased to 11.4% from 6.6%.
- GCM Q2 FY 2026-27 revenue increased 24.3% to Rs 577.6 crore.
powered by IRIS
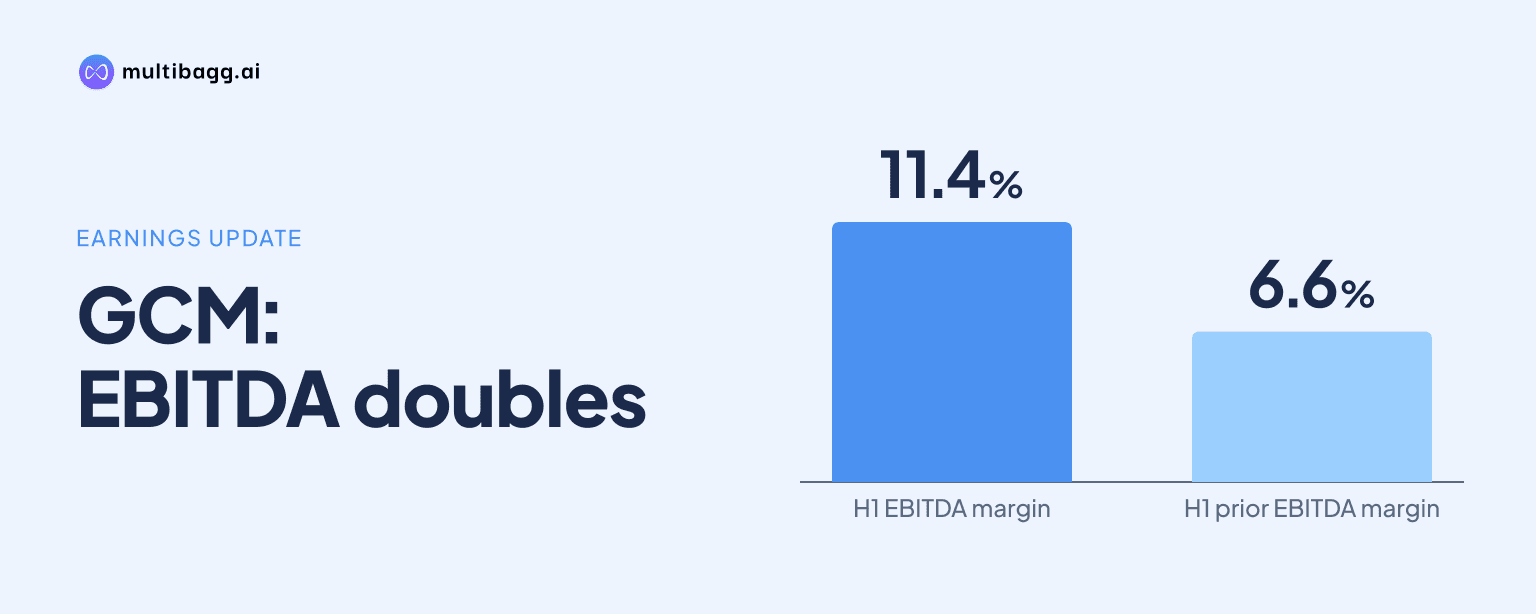
Global Cables & Mechatronics Division including SCS (GCM) increased operational EBITDA by 115.9% to Rs 134.1 crore in Sep-26, while revenue rose 25.9% to Rs 1,180.1 crore and margin reached 11.4% from 6.6%. Management reported the result after completing major restructuring across the division.
Know Suprajit Engineering inside out
Results, valuation, peers and who's buying, in one view.
How did GCM perform in the half year ended Sep-26?
GCM reported revenue of Rs 1,180.1 crore for Sep-26, compared with Rs 937.1 crore in Sep-25, while operational EBITDA increased from Rs 62.1 crore to Rs 134.1 crore. The resulting EBITDA margin expanded by 4.8 percentage points to 11.4% from 6.6%. The presentation defines operational EBITDA as excluding non-operational income, expenses and foreign-exchange gains or losses.
EBITDA grew faster than revenue during the half year, with a 115.9% increase in earnings against 25.9% sales growth. Management said GCM continued to deliver operating progress after major restructuring was completed, and said project wins secured in past years were moving into operations. The presentation does not quantify the separate financial effect of restructuring or individual project launches.
GCM’s reported figures include SCS, and the company says prior-year figures have been regrouped. This means the Sep-25 and Sep-26 revenue, EBITDA and margin comparison uses the same disclosed division-level reporting basis. The presentation does not disclose SCS revenue, EBITDA or its individual contribution to the 4.8-percentage-point margin increase.
What changed in GCM’s second quarter?
GCM generated Rs 577.6 crore of revenue and Rs 58.3 crore of operational EBITDA in Q2 FY 2026-27, compared with Rs 464.8 crore and Rs 34.5 crore in Q2 FY 2025-26. Revenue rose 24.3%, EBITDA increased 69%, and margin improved to 10.1% from 7.4%, an increase of 2.7 percentage points.
The 10.1% Q2 FY 2026-27 margin was 1.3 percentage points below the 11.4% margin reported for the Sep-26 half year, while remaining above the 7.4% recorded in the comparable prior-year quarter. Q2 revenue increased by Rs 112.8 crore year on year and EBITDA rose by Rs 23.8 crore. The presentation does not provide a separate Q1 FY 2026-27 GCM table to explain the difference between the Q2 and half-year margins.
Management described revenue growth as above 24% in both Q2 FY 2026-27 and the Sep-26 half year. The quarterly EBITDA growth rate of 69% was lower than the 115.9% half-year increase, although both periods showed EBITDA growing faster than sales. GCM’s reported operating metric excludes foreign-exchange gains and losses, rather than treating such items as division operating performance.
Which markets and operations are supporting GCM growth?
GCM manufactures cables in India, Mexico, the United States, Hungary, Morocco and China for customers outside India and South Asia. Management reported strong growth with United States and Chinese original equipment manufacturers, while describing the European business as stable despite strong headwinds. The presentation provides no revenue, profit or customer concentration figures for those markets.
Management said new projects won in past years were entering operations seamlessly and showing consistently high business growth. This production ramp-up was cited alongside the division’s Sep-26 revenue increase of Rs 243 crore and operational EBITDA increase of Rs 72 crore from Sep-25. The disclosure does not identify the products, programme timing or the value of the individual awards.
The group’s global business represented 57% of its mix in H1 2026-27, up from 56% in FY 2025-26 and 10% in FY 2011-12. That group-level geographic mix is not allocated specifically to GCM, but the division’s six-country manufacturing footprint is intended for customers outside India and South Asia. Domestic business accounted for the remaining 43% of the group mix in H1 2026-27.
Got a follow-up? Ask IRIS
What expansion plan does GCM have after restructuring?
GCM unit Suprajit Automotive Limited is undertaking a significant capacity expansion plan through a greenfield cable facility in Chennai. The presentation identifies the project as a cable-manufacturing expansion but does not disclose an investment amount, commissioning date, production capacity or linked customer programme.
The Chennai plan follows the division’s Sep-26 half-year revenue of Rs 1,180.1 crore and management’s statement that major restructuring has been completed. The company presents the site as an expansion being undertaken, rather than completed capacity. Its future effect on GCM revenue, utilisation, EBITDA or margin therefore cannot be calculated from the information provided.
At group level, total debt declined to Rs 773.1 crore at Sep-26 from Rs 785 crore at Mar-26, while net debt fell to Rs 371.4 crore from Rs 448.5 crore. Investments in mutual funds and bonds were Rs 244.1 crore and cash and cash equivalents were Rs 157.6 crore at Sep-26. These are group figures, so they do not establish the financing source for the Chennai facility.
How does GCM compare with Suprajit’s other divisions?
GCM’s 25.9% Sep-26 half-year revenue growth exceeded India Cables & Mechatronics’ 16.9% and Phoenix Lighting & Electricals’ 10.3%, but was below Sensors, Electronics & Displays’ 49.4%. GCM’s 11.4% EBITDA margin was below India Cables & Mechatronics’ 14.2%, but above Phoenix Lighting & Electricals’ 10.8% and Sensors, Electronics & Displays’ 8.8%.
GCM also had the fastest disclosed half-year EBITDA growth among the four divisions, at 115.9%. India Cables & Mechatronics EBITDA rose from Rs 98.2 crore to Rs 102.1 crore, Phoenix Lighting & Electricals EBITDA declined from Rs 23 crore to Rs 21.6 crore, and Sensors, Electronics & Displays EBITDA increased from Rs 7.7 crore to Rs 9.4 crore. These divisions reported differing revenue and margin outcomes in Sep-26.
Suprajit’s consolidated results, including SCS, showed Sep-26 revenue of Rs 2,204.7 crore, up 22.2%, and EBITDA of Rs 267.2 crore, up 39.9%. Consolidated margin rose to 12.1% from 10.6%. GCM’s 115.9% EBITDA growth exceeded the consolidated growth rate, although its 11.4% margin was 0.7 percentage points below the group margin.
Conclusion
GCM combined 25.9% revenue growth with a 115.9% rise in operational EBITDA in Sep-26, lifting its margin from 6.6% to 11.4%. Management linked the performance to completed restructuring and earlier project wins moving into operations, while identifying United States and Chinese original equipment manufacturers as growth areas and Europe as stable despite headwinds.
The next disclosed item to watch is Suprajit Automotive Limited’s greenfield cable facility in Chennai. Management has described it as a significant capacity expansion plan, but has not disclosed timing, capital spending, capacity or expected financial contribution. Updates on those details and on GCM’s margin progression would clarify the planned expansion’s operating effect.