










Gokaldas targets BTPL EBITDA break-even before merger debt
Key highlights
- BTPL is expected to reach EBITDA break-even in Q3 after slightly negative EBITDA in Q2.
- BTPL revenue is projected to rise from about Rs 170 crore in Q2 to about Rs 220 crore to Rs 225 crore in Q3.
- The BTPL merger is expected to add about Rs 300 crore of debt to Gokaldas.
- BTPL has accumulated losses exceeding Rs 600 crore, which management expects to create a tax shield.
powered by IRIS
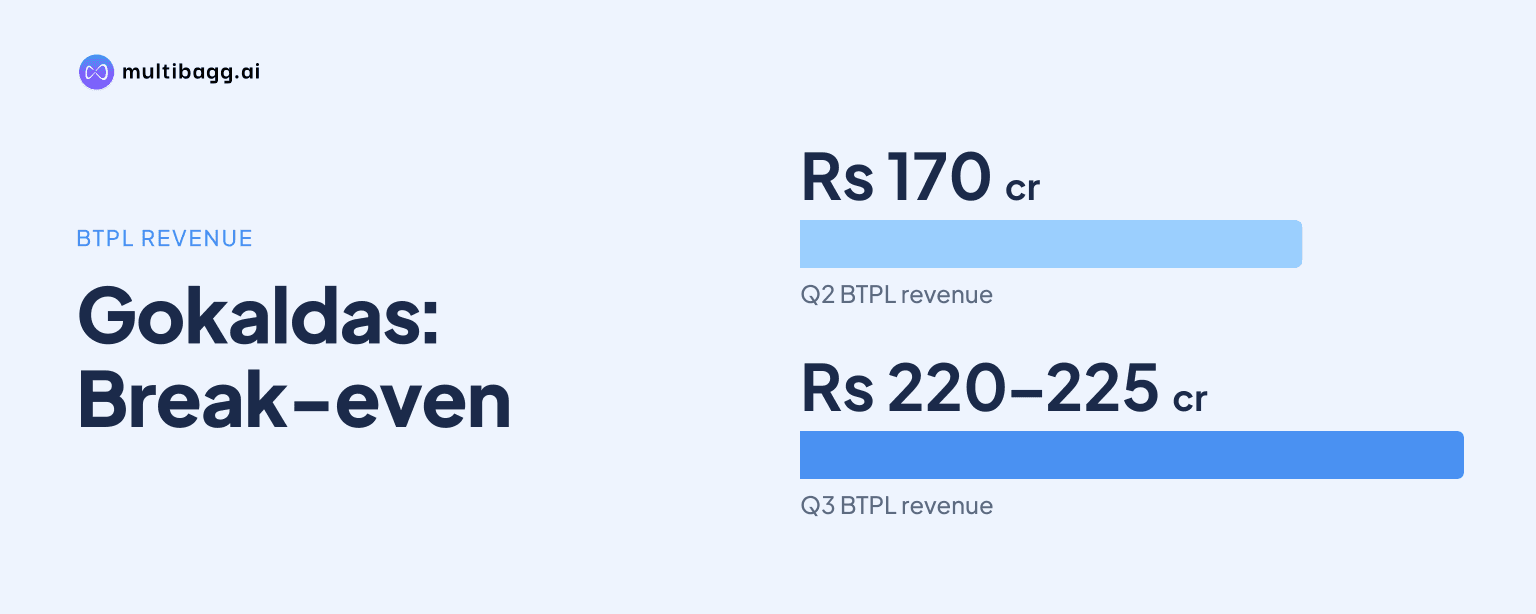
Gokaldas expects BTPL to reach earnings before interest, tax, depreciation and amortisation, or EBITDA, break-even in Q3 after slightly negative EBITDA in Q2, supported by revenue projected at about Rs 220 crore to Rs 225 crore versus about Rs 170 crore in Q2. The planned merger would add about Rs 300 crore of BTPL debt.
Know Gokaldas Exports inside out
Results, valuation, peers and who's buying, in one view.
When will BTPL reach EBITDA break-even?
BTPL is expected to reach EBITDA break-even in Q3, according to Gokaldas management. Revenue is projected to increase from about Rs 170 crore in Q2 to about Rs 220 crore to Rs 225 crore in Q3, after the fabric business reported slightly negative EBITDA in Q2. Management linked the turnaround to higher revenue and throughput rather than to a specified cost-reduction programme.
Management expects BTPL revenue to rise further to about Rs 250 crore in Q4 and said it is working towards profit before tax, or PBT, break-even at that stage. This is a higher hurdle than EBITDA break-even because PBT includes interest and depreciation. Gokaldas did not provide a Q4 EBITDA-margin target or quantify BTPL's expected PBT loss or profit.
The projected revenue increase of about Rs 50 crore to Rs 55 crore between Q2 and Q3 is the stated operating basis for the EBITDA objective. Gokaldas also said BTPL management was working to enhance throughput in Q4 FY 2026, making volume growth central to the fabric unit's path towards PBT break-even.
How much debt will BTPL add to Gokaldas?
BTPL is expected to add about Rs 300 crore of debt to Gokaldas once the merger is completed. Management said BTPL's current debt was about Rs 300 crore and that it intended to manage working capital tightly as quarterly revenue approached about Rs 260 crore in Q4. The transcript does not split this debt between working-capital borrowings and other liabilities.
Gokaldas reported net debt of Rs 429 crore at the end of September, compared with Rs 553 crore at the start of the financial year. Management is targeting year-end net debt of about Rs 650 crore to Rs 700 crore, including the likely debt inherited from BTPL, capital expenditure and working-capital requirements.
Management said the year-end debt target includes a likely Rs 80 crore to Rs 100 crore cash settlement for BTPL shareholders. It also said all capital expenditure and working capital during the financial year were being funded from cash generation. The final merger consideration, settlement terms and debt at legal completion were not specified.
When is the BTPL merger expected to close?
Gokaldas expects the BTPL merger to complete in Q3 after due process is concluded. The expected timing places the legal integration alongside the fabric business's Q3 EBITDA break-even target and before its Q4 PBT break-even objective. Management did not provide a calendar date or identify the remaining procedural steps.
The timing also matters for reported revenue. In response to an analyst's FY 2027 question, management said that if BTPL achieves about Rs 250 crore of revenue in Q4, Gokaldas should be able to add about two-thirds of that amount to its top line in FY 2027. This was management's estimate rather than formal combined-company revenue guidance.
The transcript does not state whether BTPL's Q3 financial performance would be consolidated for a full quarter, a partial quarter or from a later effective date. That uncertainty matters because the merger is expected to bring both about Rs 300 crore of debt and the accumulated losses that management expects to use as a tax shield.
Got a follow-up? Ask IRIS
How will BTPL losses affect Gokaldas tax expense?
BTPL has accumulated losses exceeding Rs 600 crore, which management said should create a tax shield after the merger. Management expects Gokaldas's tax rate to remain low for some time and said it could approach near-zero levels. This is management's expectation, contingent on the losses being available to the relevant entity after the transaction.
The expected benefit will not apply across every group company. Management said some Indian subsidiary entities would continue to pay tax because the shield would apply to the parent or standalone entity. Gokaldas did not quantify the annual tax saving, the usable portion of the losses in FY 2027, or the period for which the shield would last.
The more than Rs 600 crore accumulated-loss balance is separate from BTPL's current operating targets. Management expects the unit to move from about Rs 170 crore of Q2 revenue to about Rs 250 crore in Q4, but neither the tax shield nor the merger itself eliminates the interest and depreciation costs that must be covered for PBT break-even.
What spending plans will accompany the BTPL merger?
Gokaldas plans capital expenditure of about Rs 150 crore in the current year and may increase this to about Rs 175 crore depending on volume growth. Management said customer projections could require annual capital expenditure exceeding Rs 200 crore in each of the following three years, and agreed that about Rs 450 crore to Rs 500 crore from FY 2026 to FY 2029 was plausible.
The expansion plan is wider than BTPL. Gokaldas said it is setting up a 1,000-machine factory in Ranchi and expanding capacity in Bhopal, while management expects double-digit volume growth in its India business from FY 2028. The company said Q3 revenue growth should be strong, with reasonably strong volume growth.
Management also said two new Africa customers, one American and one European, would begin operations from April in FY 2028. These growth plans could support cash generation, but the company is simultaneously targeting Rs 650 crore to Rs 700 crore of year-end net debt after including BTPL, shareholder settlement and current-year investment requirements.
Conclusion
Gokaldas has outlined a sequence in which BTPL moves from slightly negative EBITDA on about Rs 170 crore of Q2 revenue to EBITDA break-even in Q3 on about Rs 220 crore to Rs 225 crore of revenue, then works towards PBT break-even in Q4. The merger would combine that operating recovery with about Rs 300 crore of debt, an Rs 80 crore to Rs 100 crore shareholder cash settlement and accumulated losses exceeding Rs 600 crore.
The next items to watch are completion of due process for the expected Q3 merger, BTPL's actual Q3 EBITDA result and Gokaldas's year-end net-debt outcome against its Rs 650 crore to Rs 700 crore target. Management's planned capital expenditure of Rs 150 crore to Rs 175 crore this year, potentially exceeding Rs 200 crore annually thereafter, will also affect the post-merger cash and debt position.