










Greenlam panel unit posts Rs 8.7 crore EBITDA in Q2FY27
Key highlights
- Greenlam’s Panel & Allied revenue rose 123.9% year on year to Rs 107.0 crore in Q2FY27.
- Panel & Allied EBITDA before foreign-exchange effects was Rs 8.7 crore in Q2FY27, versus a Rs 7.3 crore loss in Q2FY26.
- Greenlam’s chipboard capacity utilisation increased to 61% in Q2FY27 from 36% a year earlier.
- Chipboard average realisation rose 24.2% year on year to Rs 22,591 per cubic metre in Q2FY27.
powered by IRIS
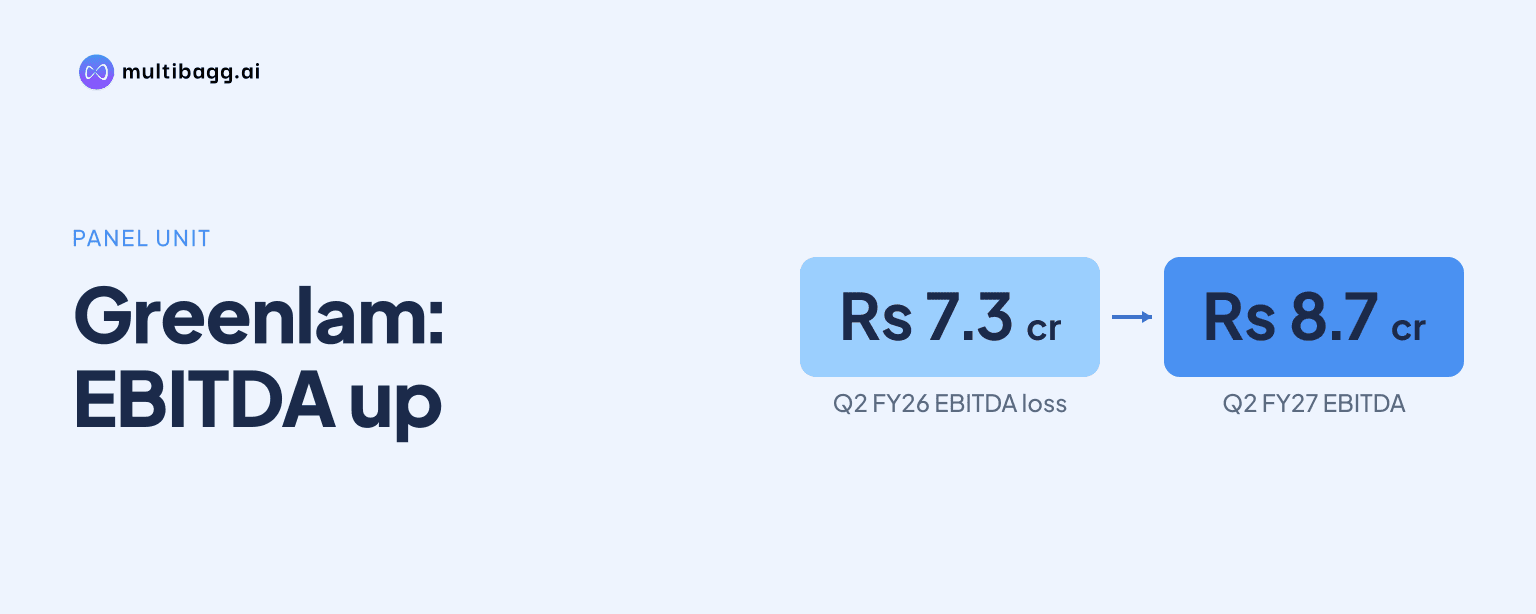
Greenlam Industries Limited’s Panel & Allied segment reported Rs 8.7 crore of earnings before interest, tax, depreciation and amortisation (EBITDA) before foreign-exchange effects in the second quarter of financial year 2027 (Q2FY27), versus a Rs 7.3 crore loss in Q2FY26, as revenue rose 123.9% to Rs 107.0 crore and chipboard utilisation reached 61%.
Know Greenlam Industries inside out
Results, valuation, peers and who's buying, in one view.
How did Greenlam’s Panel & Allied segment become EBITDA-profitable?
Greenlam’s Panel & Allied segment moved to EBITDA before foreign-exchange effects of Rs 8.7 crore in Q2FY27 from a Rs 7.3 crore loss in Q2FY26. The EBITDA margin changed to 8.1% from negative 15.3%, while net revenue increased to Rs 107.0 crore from Rs 47.8 crore. The segment includes plain and pre-laminated chipboards.
The result remained profitable after foreign-exchange effects, although the amount was lower. EBITDA including foreign-exchange effects was Rs 6.8 crore in Q2FY27, compared with a Rs 14.1 crore loss a year earlier, and the margin was 6.3% rather than negative 29.4%. The Rs 1.9 crore difference between the before- and after-foreign-exchange measures in Q2FY27 shows the reported impact of those effects on segment EBITDA.
Greenlam reported gross margin of Rs 47.6 crore for the segment in Q2FY27, up from Rs 16.7 crore in Q2FY26. Gross margin as a percentage of revenue rose 950 basis points, where one basis point is one-hundredth of a percentage point, to 44.5% from 35.0%. Segment capital employed was Rs 768.8 crore, Rs 13.1 crore below the Rs 781.9 crore reported a year earlier.
What changed in Greenlam’s chipboard volumes and realisation?
Greenlam produced 44,241 cubic metres of chipboard in Q2FY27, 66.5% above 26,571 cubic metres in Q2FY26, lifting annualised capacity utilisation to 61% from 36%. Annual installed capacity was unchanged at 292,380 cubic metres in both periods. Production was 1.3% below the 44,838 cubic metres recorded in Q1FY27, while utilisation remained at 61% sequentially.
Chipboard sales rose faster than production year on year, increasing 78.3% to 46,871 cubic metres from 26,287 cubic metres. Sales also rose 13.2% from 41,418 cubic metres in Q1FY27. Average realisation increased 24.2% year on year to Rs 22,591 per cubic metre from Rs 18,187, although it was 0.8% below the Rs 22,764 per cubic metre reported in Q1FY27.
For the first half of financial year 2027 (H1FY27), chipboard sales were 88,289 cubic metres, up 115.9% from 40,896 cubic metres in H1FY26. Average realisation for H1FY27 rose 17.6% to Rs 22,673 per cubic metre from Rs 19,281, while utilisation was 61% compared with 33% in the prior-year half. The presentation provides these operating measures for chipboard but does not provide standalone chipboard EBITDA.
Got a follow-up? Ask IRIS
How did Greenlam’s Q2FY27 panel result compare with Q1FY27?
Greenlam’s Panel & Allied revenue increased 13.1% sequentially to Rs 107.0 crore in Q2FY27 from Rs 94.6 crore in Q1FY27. Gross margin rose 16.0% to Rs 47.6 crore from Rs 41.1 crore, and gross margin percentage increased 110 basis points to 44.5% from 43.4%.
EBITDA before foreign-exchange effects increased from Rs 3.4 crore in Q1FY27 to Rs 8.7 crore in Q2FY27. Its margin rose 450 basis points to 8.1% from 3.6%. EBITDA including foreign-exchange effects rose by Rs 1.5 crore to Rs 6.8 crore from Rs 5.3 crore, while its margin increased 70 basis points to 6.3% from 5.6%.
For H1FY27, the segment reported revenue of Rs 201.6 crore, 155.9% above Rs 78.8 crore in H1FY26. EBITDA before foreign-exchange effects was Rs 12.1 crore, compared with a Rs 17.1 crore loss in the prior-year half, while EBITDA including those effects was Rs 12.1 crore against a Rs 40.0 crore loss. The H1FY27 EBITDA margin before foreign-exchange effects was 6.0%, versus negative 21.6% in H1FY26.
What wider financial indicators accompany Greenlam’s panel turnaround?
Greenlam reported total debt of Rs 1,001.1 crore at H1FY27, down from Rs 1,055.4 crore at FY26, while net debt declined to Rs 921.8 crore from Rs 940.1 crore. Long-term debt, including the current portion, fell to Rs 787.0 crore from Rs 883.9 crore, but short-term debt increased to Rs 214.1 crore from Rs 171.5 crore. Cash and liquid investments declined to Rs 79.3 crore from Rs 115.3 crore.
At the company level, earnings before interest and tax before exceptional items were Rs 106.3 crore in H1FY27, compared with Rs 81.5 crore in H1FY26. Profit after tax increased to Rs 45.7 crore from Rs 16.1 crore. Return on capital employed rose to 9.6% from 7.4%, while return on equity increased to 7.5% from 2.8%.
Net working capital was Rs 504 crore at Q2FY27, compared with Rs 413 crore at Q2FY26, and working-capital days increased to 53 from 47. Inventory stood at Rs 801 crore, or 84 days, while trade receivables were Rs 242 crore, or 25 days. Trade payables were Rs 538 crore, representing 56 days, compared with 58 days in Q2FY26.
Conclusion
Greenlam’s Panel & Allied figures show that higher chipboard activity and pricing coincided with a shift from losses to positive EBITDA in Q2FY27. Revenue rose to Rs 107.0 crore, gross margin percentage reached 44.5%, and chipboard utilisation increased to 61% from 36%, while the segment’s capital employed was broadly lower year on year at Rs 768.8 crore.
The presentation does not disclose a chipboard utilisation target, a segment profitability target, management guidance, or a scheduled event for the business. The next reported results will therefore show whether the Q2FY27 level of 61% chipboard utilisation, the Rs 22,591 per cubic metre realisation and the Rs 6.8 crore EBITDA including foreign-exchange effects are sustained.