










Greenlam Q2 profit falls 23% as freight costs cut margins
Key highlights
- Greenlam’s Q2FY27 revenue rose 8.3% year on year to Rs 875.2 crore.
- Greenlam’s Q2FY27 profit after tax fell 22.9% year on year to Rs 24.5 crore.
- Greenlam’s EBITDA margin before foreign exchange declined 330 basis points to 9.9% in Q2FY27.
- Greenlam’s chipboard revenue increased 123.9% year on year to Rs 107.0 crore in Q2FY27.
powered by IRIS
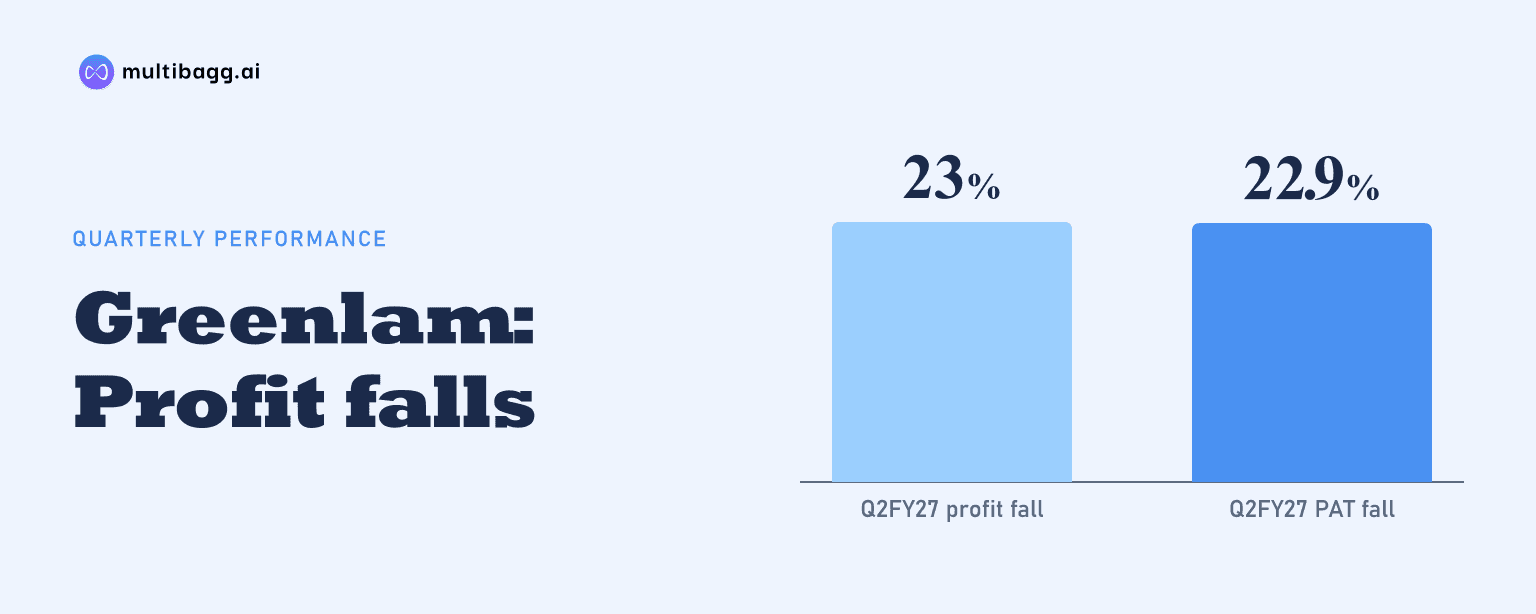
Greenlam Industries Limited reported Q2FY27 revenue growth of 8.3% to Rs 875.2 crore, but profit after tax fell 22.9% year on year to Rs 24.5 crore as higher freight costs and a 12.0% decline in laminate sales volume reduced earnings. EBITDA margin before foreign-exchange effects fell 330 basis points to 9.9%.
Know Greenlam Industries inside out
Results, valuation, peers and who's buying, in one view.
Why did Greenlam’s Q2FY27 profit decline?
Greenlam’s profit after tax declined to Rs 24.5 crore in Q2FY27 from Rs 31.8 crore in Q2FY26, while revenue rose by Rs 66.9 crore. Profit-after-tax margin narrowed to 2.8% from 3.9%, and earnings before interest, tax, depreciation and amortisation, or EBITDA, before foreign-exchange effects fell 19.0% to Rs 86.5 crore from Rs 106.8 crore.
Gross profit increased only 2.1% to Rs 450.5 crore, compared with the 8.3% rise in revenue. Gross margin declined 310 basis points to 51.5% from 54.6%, which Greenlam attributed to raw-material price fluctuations and a change in product mix. Employee costs increased to Rs 163.1 crore from Rs 153.7 crore, while other expenses rose to Rs 200.9 crore from Rs 180.8 crore.
Management said Q2FY27 geopolitical turbulence associated with the Middle East war led to fluctuations in crude prices, crude-linked commodities and foreign-currency rates. It also cited substantially higher freight costs, container and vessel availability delays, and longer transit times. Foreign-exchange loss was Rs 1.9 crore, versus Rs 2.4 crore a year earlier, while EBITDA including foreign exchange declined 18.9% to Rs 84.7 crore.
How did laminate volumes affect Greenlam’s margins?
Greenlam’s Laminates & Allied segment recorded flat Q2FY27 revenue of Rs 658.0 crore year on year, as sales volume fell 12.0% to 5.09 million sheets from 5.79 million sheets. Management said volumes declined in both domestic and international markets, leaving the company’s largest disclosed segment without year-on-year value growth.
Average realisation rose 12.4% to Rs 1,241 per sheet from Rs 1,104 per sheet, offsetting lower sheet sales at the revenue level. However, the segment’s gross margin fell 360 basis points to 52.9%, and EBITDA before foreign exchange declined 32.8% to Rs 79.3 crore from Rs 118.0 crore.
The segment’s EBITDA margin before foreign exchange contracted 590 basis points to 12.0% from 17.9%. Production declined 18.3% to 4.83 million sheets, while annualised capacity utilisation fell to 79% from 96%; annual installed capacity was unchanged at 24.52 million sheets.
Sequentially, Laminates & Allied revenue rose 10.4% from Rs 596.1 crore in Q1FY27 and sales volume increased 10.2% from 4.62 million sheets. Yet its Q2FY27 EBITDA margin before foreign exchange was 190 basis points below Q1FY27’s 13.9%, and gross margin was 240 basis points below 55.3%, showing that the volume recovery did not restore margins.
Got a follow-up? Ask IRIS
Which businesses supported Greenlam’s Q2FY27 revenue growth?
Greenlam’s chipboard business led growth outside laminates, recording Q2FY27 revenue of Rs 107.0 crore, up 123.9% year on year and 13.1% quarter on quarter. Management reported pre-foreign-exchange EBITDA of Rs 8.7 crore and said chipboard remained in operating profit during the quarter.
Plywood & Allied generated Q2FY27 revenue of Rs 110.2 crore and reduced losses by Rs 1.4 crore, according to management. The presentation does not disclose the segment’s absolute loss or EBITDA, but the revenue from chipboard and Plywood & Allied helped lift consolidated revenue while Laminates & Allied revenue remained at Rs 658.0 crore.
For H1FY27, Greenlam’s revenue increased 12.8% to Rs 1,671.9 crore from Rs 1,482.0 crore in H1FY26. EBITDA before foreign exchange rose 3.8% to Rs 167.7 crore, but its margin decreased 90 basis points to 10.0%, compared with 10.9% in the prior-year half.
What changed in Greenlam’s debt and working capital?
Greenlam reported net debt of Rs 921.8 crore as of September 30, 2026, with working-capital days at 53 days in Q2FY27. Total borrowings were Rs 1,001.1 crore at September 2026, down from Rs 1,055.4 crore at March 2026, primarily because long-term borrowings fell to Rs 787.0 crore from Rs 883.9 crore.
Short-term borrowings rose to Rs 214.1 crore at September 2026 from Rs 171.5 crore at March 2026, partly offsetting the reduction in long-term debt. Inventories increased to Rs 800.9 crore from Rs 763.9 crore, trade receivables rose to Rs 241.6 crore from Rs 218.7 crore, and cash and bank balances declined to Rs 46.8 crore from Rs 63.9 crore.
Shareholders’ funds increased to Rs 1,215.8 crore from Rs 1,179.1 crore, including reserves and surplus of Rs 1,190.6 crore versus Rs 1,153.7 crore. Total assets declined to Rs 2,982.1 crore at September 2026 from Rs 3,004.2 crore at March 2026, as fixed assets fell to Rs 1,555.0 crore from Rs 1,715.4 crore.
Conclusion
Greenlam’s Q2FY27 performance showed that revenue growth did not translate into higher earnings. Chipboard revenue grew 123.9% to Rs 107.0 crore and Plywood & Allied generated Rs 110.2 crore, but flat laminate revenue, lower laminate volumes and freight-related cost pressure reduced group EBITDA margin to 9.9% and profit after tax to Rs 24.5 crore.
The next results will indicate whether laminate volumes, which increased sequentially to 5.09 million sheets in Q2FY27, continue to recover and whether freight, raw-material and product-mix pressures ease. Management’s disclosed chipboard operating profit, along with the September 2026 net debt of Rs 921.8 crore and 53 working-capital days, remain relevant measures to track.