










Greenply Industries Limited retains 15%-16% MDF margin target
Key highlights
- Greenply's Q2 FY27 MDF core EBITDA margin was 15.2% after the earlier price increase was rolled back.
- Greenply's MDF revenue rose 18.4% year on year to Rs 173.9 crore in Q2 FY27, with volume up 16.1% to 54,605 CBM.
- Greenply said chemical costs remain 7%-8% higher, while timber prices were stable in Q2 FY27.
- Greenply retained FY27 MDF guidance of approximately 20% volume growth and a 15%-16% core EBITDA margin.
powered by IRIS
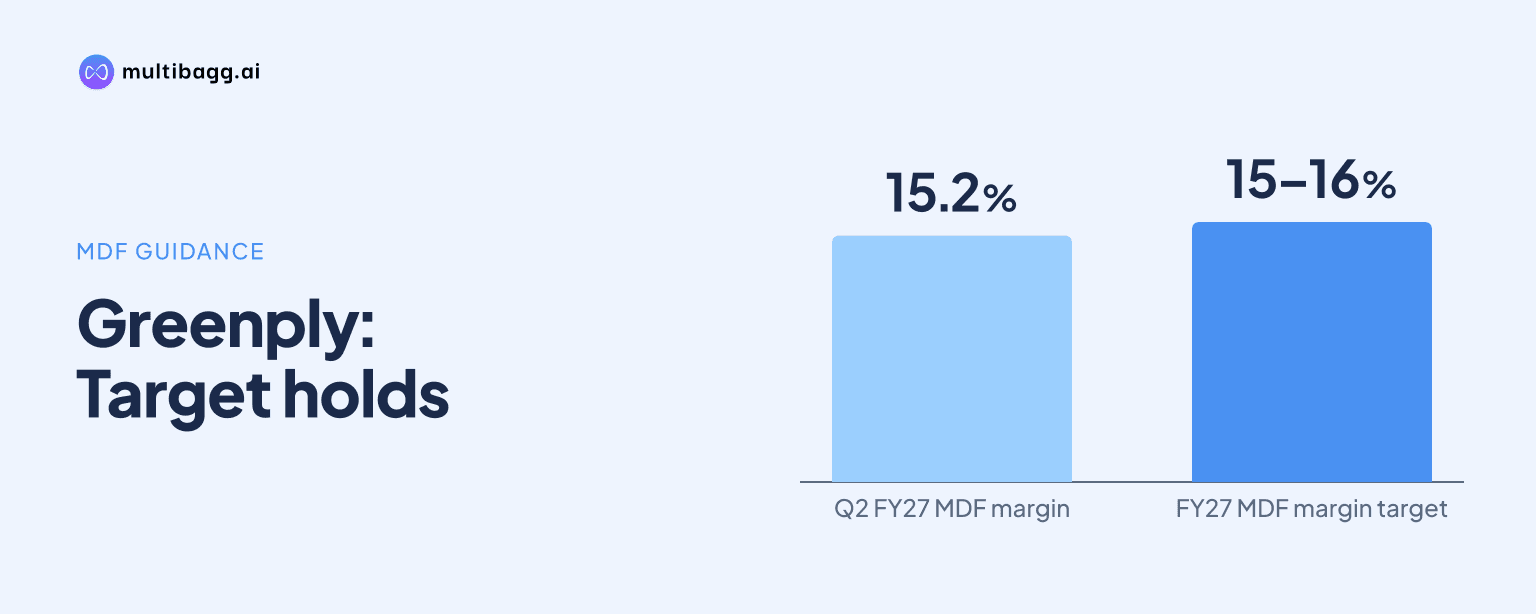
Greenply Industries Limited retained its FY27 medium-density fibreboard, or MDF, core earnings before interest, tax, depreciation and amortisation, or EBITDA, margin target of 15%-16%, despite fully rolling back an earlier price rise and absorbing a 7%-8% increase in chemical costs. Its MDF business delivered a 15.2% core EBITDA margin on Rs 173.9 crore of Q2 FY27 revenue.
Know Greenply Industries inside out
Results, valuation, peers and who's buying, in one view.
Why did Greenply roll back its MDF price increase?
Greenply said the MDF price increase taken in Q1 FY27 was “more or less completely” rolled back during Q2 FY27 because competitive intensity was high. Management said the rollback was the only reason for the sequential decline in MDF EBITDA margin, while Q2 realisation declined to Rs 31,816 per cubic metre, or CBM.
The selling-price reversal was not matched by lower chemical costs. Management said chemical costs had risen by about 7%-8% and that this increase had sustained, while other costs were broadly stable. Timber prices were stable in Q2 FY27, and management said its MDF and plywood margin commitments assumed existing timber costs rather than a future gain from lower prices.
Greenply still reported 18.4% year-on-year MDF revenue growth to Rs 173.9 crore in Q2 FY27, while volume rose 16.1% to 54,605 CBM. Revenue growth exceeded volume growth by 2.3 percentage points, but the gap was narrower than in a rising-price environment because the earlier price increase had been reversed.
Can Greenply maintain its 15%-16% MDF margin target?
Greenply said it expects to maintain a 15%-16% core EBITDA margin in MDF for FY27, while revising its full-year volume-growth expectation to approximately 20%. Management attributed the margin confidence to a better product mix, energy-cost reductions achieved early in FY27 and further operating efficiencies at the plant.
The product-mix mechanism includes replacing some plain interior-grade board sales with pre-laminated, or Pre-lam, boards. Management said absolute volumes of both Pre-lam and plain boards rose, although it did not disclose the share of value-added products in MDF sales. The H1 FY27 MDF margin of 16.3% was 350 basis points higher year on year, providing the reported first-half comparison for the FY27 target.
Management also gave an absolute profitability indicator for the existing MDF line. It said the line can produce approximately 60,000 CBM a quarter and that Greenply was confident it could maintain EBITDA above Rs 5,000 per CBM. An analyst cited Q2 EBITDA of about Rs 4,700 per CBM, but management did not provide a formal quarterly EBITDA-per-CBM target.
Additional products may affect the sales mix in the second half, according to management. Greenply’s high-density fibreboard, or HDF, flooring line began commercial production in July 2026, and management expects it to begin contributing during H2 FY27 as production ramps up. Management also said flooring and insulation products would start soon.
Got a follow-up? Ask IRIS
What changed in Greenply's MDF volume and realisation?
Greenply said Q2 FY27 MDF volume was limited by production disruption rather than sales demand. Monsoon disruption and annual maintenance reduced production to slightly above 53,000 CBM, while sales reached 54,605 CBM, meaning quarterly sales exceeded the output produced during the period.
The annual maintenance activity had been planned for one day but lasted four days, management said. It expects to recover volume in Q3 and Q4 FY27, but retained the approximately 20% full-year growth outlook because H1 FY27 had missed the earlier pace. H1 MDF volume nevertheless rose 20.4% year on year to 1,12,411 CBM.
H1 FY27 revenue increased 25.6% year on year to Rs 369.6 crore, faster than the 20.4% volume increase. However, H1 realisation of Rs 32,694 per CBM was Rs 878 per CBM above the Q2 level of Rs 31,816, showing the effect of the pricing rollback within the half-year period.
The MDF performance differed from plywood, where premium-product sales supported pricing and profitability. Plywood revenue rose 15.5% year on year to Rs 625.7 crore in Q2 FY27 despite 6.1% volume growth, while core EBITDA margin reached 10.05%, up 180 basis points year on year. Management said plywood plant utilisation exceeded 100%, which constrained capacity and led it to prioritise higher-value products.
What capacity and competition factors could affect Greenply's MDF plan?
Greenply acknowledged increasing MDF competition, naming Action TESA’s southern plant and Elixrr, which management said was due to start operations soon. Management also said its new MDF facility at Vadodara was progressing ahead of schedule, although the prepared remarks retained a Q2 FY28 commissioning expectation.
Management’s view is that the existing line’s output can be sold, supported by Greenply’s brand and a larger value-added product mix. It said the second MDF line was designed with an improvement in asset-turn ratio, but did not quantify that ratio or disclose the planned capacity during the call. The company’s Q2 FY27 MDF sales of 54,605 CBM were above production despite the monsoon and maintenance disruption.
Management said some smaller unorganised MDF producers could shut over the next six to 12 months at prevailing margins, but that was management’s assessment rather than a company forecast. It also said it expected industry volume growth of more than 20% over the next three to five years, even as new capacity enters the market.
Greenply reported consolidated net debt of Rs 544 crore at the end of Q2 FY27 and a debt-to-equity ratio of 0.56 times. Management said this was within its guided range of 0.7 to 0.75 times and that the Vadodara MDF facility and Odisha greenfield project remained on their committed timelines.
Conclusion
Greenply’s FY27 MDF margin plan depends on product mix, energy-cost actions and plant efficiencies rather than retaining the Q1 price increase. The rollback reduced Q2 realisation to Rs 31,816 per CBM while chemical costs remained 7%-8% higher, yet the business reported a 15.2% core EBITDA margin and management retained its 15%-16% target.
The next disclosed milestones are volume recovery in Q3 and Q4 FY27 after the maintenance and monsoon disruption, the H2 FY27 ramp-up of HDF flooring, and the planned Q2 FY28 commissioning of the Vadodara MDF facility. Management also said it would provide further detail on the facility’s timing in the next quarter.