










HFL retains FY27 PAT target after H1 profit rises 27.6%
Key highlights
- HFL reported H1FY27 revenue of Rs 2,476.4 crore, up 18.0% year on year.
- HFL reported H1FY27 PAT of Rs 87.8 crore, up 27.6% year on year.
- HFL retained FY27 PAT guidance of Rs 200-220 crore and expects around Rs 200 crore.
- HFL's H1FY27 operating cash flow was Rs 57.7 crore, compared with negative Rs 9.5 crore in H2FY26.
powered by IRIS
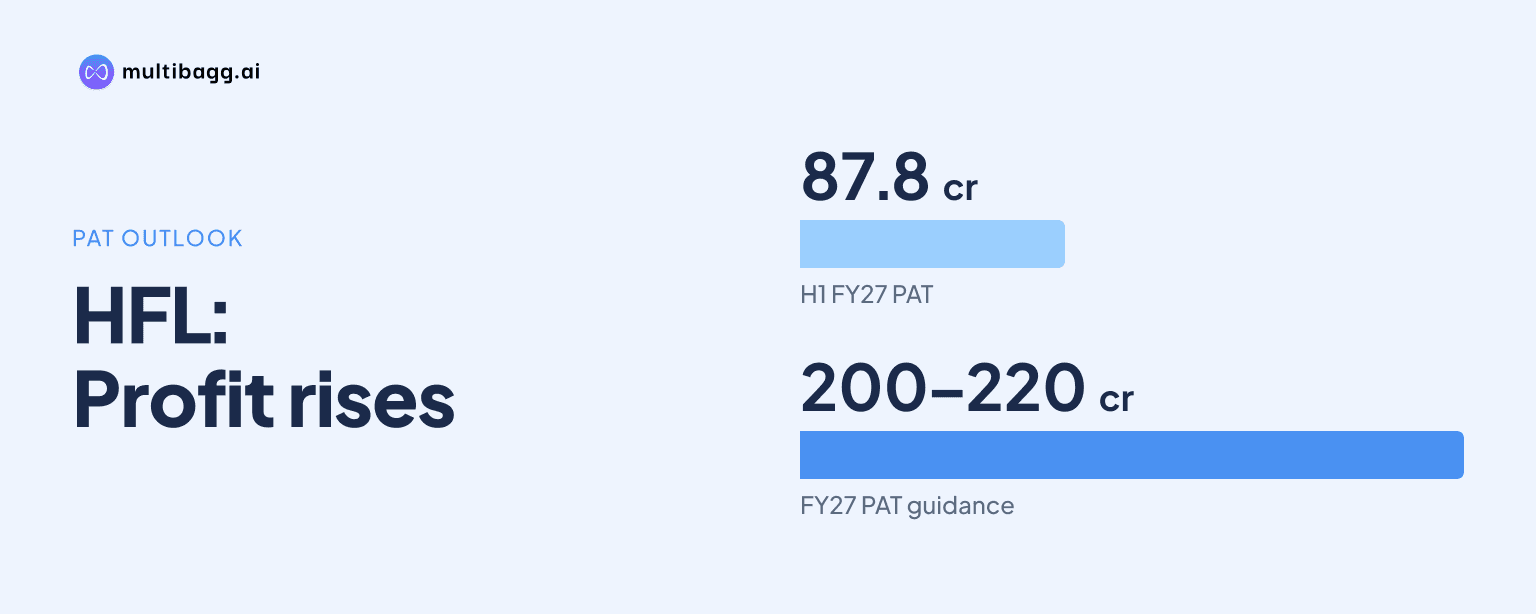
Hindustan Foods Limited retained FY27 profit-after-tax guidance of Rs 200-220 crore after reported H1FY27 profit after tax rose 27.6% year on year to Rs 87.8 crore. HFL said it expects to finish around Rs 200 crore, with Q4FY27 as the major contributor, despite floods, footwear supply-chain disruption and delayed project commissioning.
Know Hindustan Foods inside out
Results, valuation, peers and who's buying, in one view.
How did HFL perform in H1FY27?
HFL delivered total revenue of Rs 2,476.4 crore in H1FY27, up 18.0% from Rs 2,098.1 crore in H1FY26, while earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 25.8% to Rs 221.6 crore from Rs 176.1 crore. Profit before tax increased 28.2% to Rs 117.7 crore from Rs 91.8 crore.
HFL’s adjusted H1FY27 profit after tax, or PAT, was Rs 89.1 crore, up 29.5% year on year, excluding a Rs 1.30 crore exceptional loss. The item reflected the minimum deductible under the insurance policy after floods at the Silvassa facility. Adjusted Q2FY27 PAT was Rs 46.4 crore, up 21.7% year on year and 8.4% quarter on quarter, while reported Q2FY27 PAT was Rs 45.0 crore.
Can HFL reach its FY27 PAT guidance?
HFL has retained FY27 PAT guidance of Rs 200-220 crore, and management said it expects to land around Rs 200 crore with Q4FY27 as the main contributor. Against reported H1FY27 PAT of Rs 87.8 crore, a Rs 200 crore full-year result would require Rs 112.2 crore in H2FY27. Against adjusted H1FY27 PAT of Rs 89.1 crore, the corresponding requirement is Rs 110.9 crore, although the presentation does not state a quarterly PAT target.
HFL’s guidance assigns 43%-48% of FY27 PAT to H1 and 52%-57% to H2. In FY26, H1 represented 46% of the Rs 149 crore annual PAT and H2 represented 54%. H1FY27 adjusted PAT of Rs 89.1 crore is within the stated H1 share range of the Rs 200-220 crore guidance, but HFL has not quantified expected profit from individual new facilities.
HFL’s Q2FY27 progression provides the immediate base for its second-half plan. Q2FY27 revenue of Rs 1,269.4 crore was 5.2% above Q1FY27 revenue of Rs 1,207.0 crore, while EBITDA increased 8.6% to Rs 115.4 crore from Rs 106.3 crore. Profit before tax rose 8.1% sequentially to Rs 61.2 crore, and reported PAT increased 5.3% to Rs 45.0 crore despite the Rs 1.30 crore Silvassa insurance deductible.
What disruptions affected HFL in the first half?
HFL said profitability in the early part of H1FY27 was affected by footwear supply-chain disruption and about 1.5 months of interruption at Silvassa following floods. The disruption delayed ramp-up at the brownfield liquid-detergent facility, which commenced commercial production in Q2FY27. HFL now expects the facility’s ramp-up to be complete by the end of Q3FY27.
HFL’s footwear division returned to profitability in Q2FY27 after it completed legacy fixed-price orders and booked new orders at revised prices reflecting raw-material costs and revised wage rates. HFL also cited timely raw-material procurement and operating efficiencies. October 2026 delivered the division’s highest-ever monthly turnover, and its order book was full until March 2027.
HFL deferred commissioning of three facilities by one to two months because of delays in critical imported equipment. The Rs 50 crore Lucknow detergent-bars plant, Rs 60 crore Goa Greek-yoghurt plant and Rs 25 crore Baddi Ayurvedic-wellness plant are now scheduled to commence production in Q4FY27. The presentation does not quantify the revenue or PAT contribution expected from these projects during FY27.
Got a follow-up? Ask IRIS
What supports HFL’s second-half plan?
HFL reported cash flow from operations of Rs 57.7 crore in H1FY27, recovering from negative Rs 9.5 crore in H2FY26 but below Rs 109.5 crore in H1FY26. Operating profit before working-capital changes rose to Rs 219.5 crore from Rs 172.7 crore, but working-capital changes consumed Rs 144.6 crore compared with Rs 48.4 crore a year earlier.
Management said HFL has started moving selected customer businesses from gross to net revenue recognition to address an inverted goods and services tax, or GST, duty structure. Management said the change releases working capital without affecting profitability, and additional customers have agreed to move to net recognition from Q4FY27. Alongside recently announced GST changes, HFL expects significantly stronger cash flow from operations in H2FY27.
HFL’s gross block, including capital work-in-progress and capital advances under the presentation’s definition, was Rs 1,961 crore at September 2026 and is projected at Rs 2,367 crore by March 2027. The projection includes Rs 89 crore of in-progress projects and Rs 317 crore of new projects. Total borrowings were Rs 1,182.9 crore at September 30, 2026, compared with Rs 1,050.0 crore at March 31, 2026, while net debt to equity was 0.90 times.
Conclusion
HFL’s retained Rs 200-220 crore FY27 PAT guidance depends on a second-half acceleration after H1FY27 revenue increased 18.0%, EBITDA rose 25.8% and reported PAT grew 27.6%. The first half included identifiable disruptions: a Rs 1.30 crore flood-related insurance deductible, about 1.5 months of Silvassa disruption, footwear supply-chain issues and project delays linked to imported equipment.
The next disclosed milestones are completion of the liquid-detergent ramp-up by the end of Q3FY27 and Q4FY27 commissioning targets for Lucknow detergent bars, Goa Greek yoghurt and Baddi Ayurvedic wellness. HFL also plans Q4FY27 commissioning for Aurangabad beverages, Mysuru bottled water, Guwahati carbonated soft drinks and the Panipat ice-cream expansion, while management expects customer moves to net revenue recognition from Q4FY27 to improve operating cash generation without changing profitability.