










HIRECT targets ₹5-5.5 crore locomotive content from 2026
Key highlights
- HIRECT targets ₹5-5.5 crore of value per locomotive from 2026, compared with ₹1.5-1.6 crore in 2022-2025.
- HIRECT has more than 190 engineers and more than 50 products under active research and development.
- HIRECT has begun official 50,000-kilometre field trials for its propulsion systems.
- HIRECT reported an order book of about ₹795 crore as of September 2026.
powered by IRIS
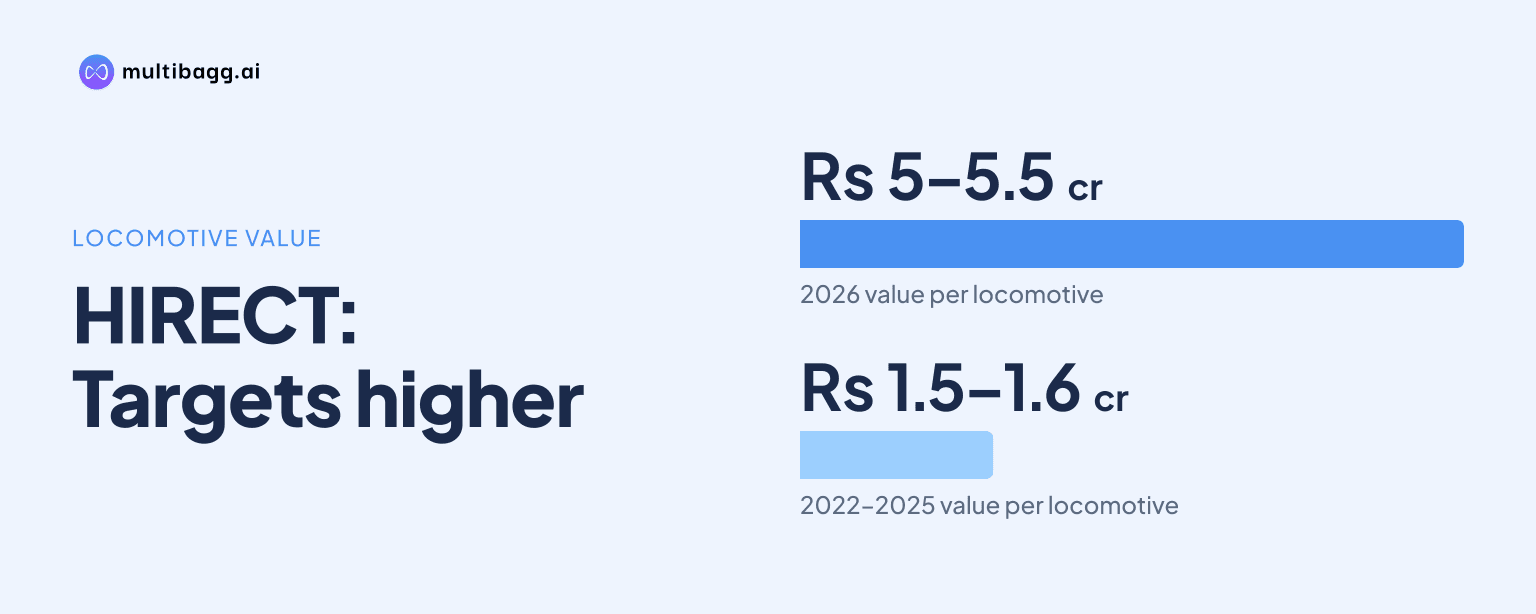
Hind Rectifiers Limited (HIRECT) targets ₹5-5.5 crore of value per locomotive from 2026 onward, compared with ₹1.5-1.6 crore in 2022-2025, by supplying propulsion, brake systems, integrated power electronics and design integration rather than products and sub-systems alone.
Know Hirect inside out
Results, valuation, peers and who's buying, in one view.
What is HIRECT's locomotive value target?
HIRECT's stated target is ₹5-5.5 crore of content per locomotive in its integrated-systems phase from 2026 onward. The presentation places its 2022-2025 products-and-sub-systems phase at ₹1.5-1.6 crore per locomotive, covering traction transformers, rectifiers, auxiliary converters and locomotive panels. At the stated ranges, the planned increase is ₹3.4-4 crore per locomotive, taking content to more than three times the earlier level.
The presentation describes 2022-2025 as a move beyond HIRECT's pre-2022 role as a component supplier. The 2026 plan adds systems that combine equipment and engineering rather than only increasing sales of the four sub-system categories cited for 2022-2025. This is a value-per-unit objective, not a disclosed locomotive-volume target or revenue forecast.
Which products are intended to raise HIRECT's content per locomotive?
HIRECT intends to raise locomotive content through indigenous propulsion systems, brake systems, integrated power electronics, and design and integration. It also lists traction motors, insulated-gate bipolar transistor, or IGBT, based electronics, heating, ventilation and air-conditioning systems, and battery chargers in its strategic-evolution plan. These categories extend beyond the traction transformers and converters associated with the 2022-2025 phase.
The propulsion programme has entered validation and initial supply stages. HIRECT says it is included in the Research Designs and Standards Organisation, or RDSO, Unified Vendor Approval Module list as a Development Source for propulsion systems, with supplies commenced. It also reports completing external type tests by RDSO and Chittaranjan Locomotive Works, or CLW, initiating official 50,000-kilometre field trials, and securing development orders for next-generation passenger-locomotive propulsion systems.
HIRECT also identifies brake systems as part of the integrated offering. It says it was the first Indian company to develop and successfully test an indigenous brake system for 6,000-horsepower locomotives. The disclosure concerns development and testing rather than a stated series-production order, but places brakes alongside propulsion in the categories supporting the ₹5-5.5 crore per-locomotive target.
What engineering capability is HIRECT building for integrated systems?
HIRECT reports more than 190 engineers across research and development centres in Mumbai and Hyderabad, with more than 50 products under active development. Its stated pipeline spans propulsion, brake systems, converters, heating, ventilation and air-conditioning, digital intelligence and electronics manufacturing services, or EMS. These categories are relevant to supplying and integrating a broader set of locomotive systems.
The company says its innovation work is intended to reduce time to market while expanding localisation, reliability and lifecycle performance in rail mobility. Its collaboration activity includes investment in Coincade Studios for artificial-intelligence-led capabilities such as predictive analytics, intelligent monitoring and operational optimisation. HIRECT also cites collaboration with Elventive France in power electronics, automation, EMS and printed electronics.
The disclosed milestones distinguish the development pipeline from mature commercial scale. The 50,000-kilometre field trials and development orders show that the propulsion system remains in customer evaluation and deployment stages. RDSO Development Source status and commenced supplies indicate market entry, while the presentation does not give a date for completing trials or converting development orders into wider production.
Got a follow-up? Ask IRIS
How does vertical integration support HIRECT's systems strategy?
HIRECT's vertical-integration plan covers continuously transposed conductors, or CTC, copper conductors, aluminium tanks, EMS assemblies, power supplies and IGBT gate drivers. The stated mechanism is greater control over critical components and indigenisation, allowing HIRECT to bring more inputs, electronics and engineering into its systems offering. The presentation does not quantify cost savings or margins from individual components.
Its copper-conductor operation illustrates both the opportunity and a capacity disclosure to track. One page highlights 500 tonnes per month, or TPM, of installed capacity, while accompanying text cites 350 TPM of installed capacity against internal demand of about 220 TPM. Based on the 350-TPM figure, the text implies roughly 130 TPM of surplus capacity, alongside commercial production of CTC, enameled paper insulated copper conductors and paper insulated copper conductors for transformer applications.
HIRECT says it received Indian Railways approvals for CTC and paper insulated copper conductors for traction transformers in Q2 FY27. It also says the conductor operation has secured private-customer orders, creating a potential third-party sales channel beyond internal transformer requirements. The presentation does not disclose the value, delivery schedule or locomotive-content contribution of those orders.
How does Elventive France fit HIRECT's 2026 plan?
HIRECT presents the acquisition of Elventive France, formerly BeLink Solutions, as a European manufacturing hub for robotics, power electronics and EMS. Elventive France has about four decades of expertise and six automated production lines, according to the presentation. HIRECT says the acquisition combines its high-reliability power-electronics experience with Elventive France's precision manufacturing and testing capabilities.
The company says the French business provides access to regulated European railway, defence and aerospace markets, together with certifications and established customer relationships. Its geographic plan also includes using the acquisition to strengthen Europe and other strategic markets while establishing a foothold in United States rail and mining markets. These are expansion priorities rather than disclosed revenue targets for 2026 or later.
Management's Q2 FY27 commentary places the systems push alongside execution costs. As of September 2026, HIRECT reported an order book of about ₹795 crore, while management said Elventive France was in an integration and scale-up phase with higher employee and operating expenses as it progressed toward breakeven. Management therefore expects consolidated earnings before interest, tax, depreciation and amortisation margins to remain under pressure over the next few quarters.
Conclusion
HIRECT's move from ₹1.5-1.6 crore to ₹5-5.5 crore of locomotive value is based on supplying a broader package of propulsion, braking, power electronics and engineering integration from 2026. The plan is supported by more than 190 engineers, more than 50 products under development, RDSO Development Source recognition, commenced propulsion supplies and 50,000-kilometre field trials.
The next evidence to watch is progress through propulsion trials and development orders, and conversion of the Indian Railways approvals for CTC and paper insulated copper conductors received in Q2 FY27. Management has also identified the unresolved earnings effect of Elventive France's scale-up, saying the business is progressing toward breakeven while consolidated EBITDA margins remain under pressure for the next few quarters.