










HUDCO foreign-currency loans reach Rs 29,088.53 crore in H1 FY27
Key highlights
- HUDCO’s foreign-currency ECB/ODA loans rose to Rs 29,088.53 crore in H1 FY27 from Rs 10,034.03 crore in H1 FY26.
- Foreign-currency loans represented 17.70% of HUDCO’s Rs 1,64,376.66 crore total borrowings in H1 FY27.
- HUDCO raised Rs 14,972.93 crore through the RBI concessional forex-swap window.
- HUDCO reported a 6.16% weighted average cost on five-year ECB raised in H1 FY27.
powered by IRIS
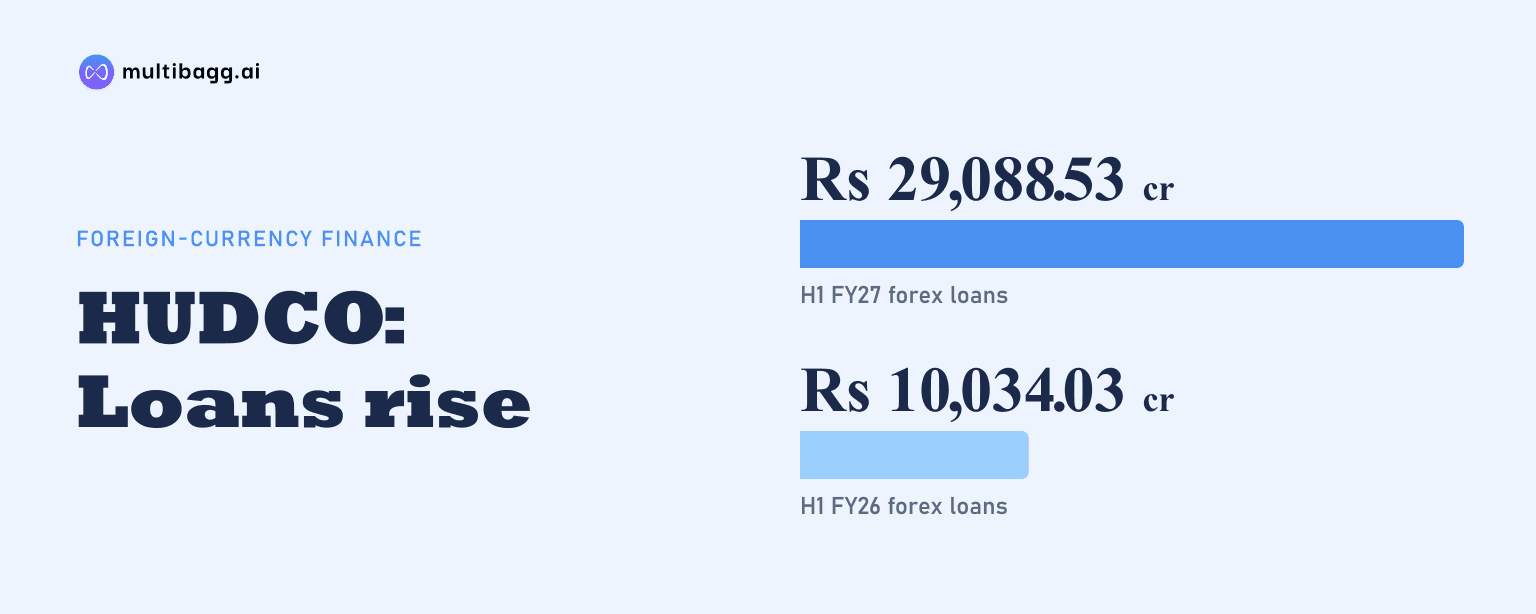
HUDCO’s foreign-currency loan balance reached Rs 29,088.53 crore in H1 FY27, up from Rs 10,034.03 crore in H1 FY26, lifting foreign-currency ECB/ODA loans to 17.70% of total borrowings. HUDCO reported that Rs 14,972.93 crore of foreign-currency fundraising was raised through the Reserve Bank of India’s concessional forex-swap window.
Know Housing & Urban Development Corporation inside out
Results, valuation, peers and who's buying, in one view.
How much did HUDCO’s foreign-currency borrowing increase?
HUDCO increased its foreign-currency loans by Rs 19,054.50 crore year on year to Rs 29,088.53 crore in H1 FY27, compared with Rs 10,034.03 crore in H1 FY26. The borrowing-profile table classifies this balance as external commercial borrowings, or ECB, and official development assistance, or ODA, within HUDCO’s foreign-currency funding exposure.
The increase came alongside a Rs 38,341.20 crore rise in total borrowings, which reached Rs 1,64,376.66 crore in H1 FY27 from Rs 1,26,035.46 crore a year earlier. Foreign-currency loans accounted for about half of the reported year-on-year increase in total borrowings, while medium-term bank loans increased by Rs 21,162.74 crore to Rs 67,150.99 crore.
What was HUDCO’s borrowing mix in H1 FY27?
HUDCO funded 43.21% of its H1 FY27 borrowings through bank loans, while foreign-currency ECB/ODA represented 17.70%, bonds represented 36.32% and refinance represented 2.77%. In rupee terms, bank loans were Rs 71,032.91 crore, bonds were Rs 59,704.27 crore, foreign-currency loans were Rs 29,088.53 crore and refinance assistance was Rs 4,550.95 crore.
The mix shows a larger foreign-currency component alongside a higher bank-loan balance. Total bonds, including Rs 20,000 crore of Government of India fully serviced bonds, were Rs 59,704.27 crore in H1 FY27, compared with Rs 61,900.33 crore in H1 FY26 when the same bond categories are added. Taxable bonds were Rs 29,019.57 crore, including capital gain bonds launched on 7 May 2025, versus Rs 29,678.95 crore a year earlier.
How did the RBI forex-swap window support HUDCO’s funding?
HUDCO raised Rs 14,972.93 crore under the Reserve Bank of India, or RBI, concessional forex-swap window, according to its H1 FY27 liability-management disclosure. That amount is included in Rs 16,618.18 crore of foreign-currency borrowing raised during H1 FY27, indicating that the RBI-linked route formed most of the reported foreign-currency fundraising in the half year.
HUDCO separately distinguished foreign-currency funds raised during H1 FY27 from foreign-currency loans outstanding at the reporting date. Foreign-currency funds raised were Rs 16,618.18 crore, whereas outstanding ECB/ODA loans were Rs 29,088.53 crore. The difference indicates that the outstanding balance includes funding beyond the half-year’s newly raised amount, while the presentation does not provide a maturity-by-maturity reconciliation.
Got a follow-up? Ask IRIS
What was the cost of HUDCO’s new foreign-currency funding?
HUDCO reported a weighted average cost of 6.16% on five-year ECB raised in H1 FY27, while its overall cost of funds was 7.07%. The presentation identifies this ECB borrowing as international funding aligned with HUDCO’s asset-liability management, or ALM, profile.
The 6.16% foreign-currency cost compared with 7.12% for medium-term bank and financial institution loans raised in H1 FY27, and 7.06% for taxable bonds raised in the half year. However, HUDCO’s overall cost of funds increased by 3 basis points from 7.04% in H1 FY26 to 7.07% in H1 FY27. A basis point is one-hundredth of a percentage point, so the lower cost on the reported foreign-currency tranche did not reduce the aggregate funding cost disclosed for the half year.
The liability-management table separates funds raised during H1 FY27 from balances reported in the borrowing profile. Foreign-currency funds raised in H1 FY27 were Rs 16,618.18 crore, while the outstanding ECB/ODA category was Rs 29,088.53 crore. The presentation therefore identifies the two measures separately and does not reconcile them by individual borrowing maturity.
What international funding plans has HUDCO disclosed?
HUDCO says it is exploring loans and bonds denominated in US dollars, euros and Japanese yen across new geographies, while strengthening internal controls and applying appropriate currency hedging. HUDCO also says it is in advanced discussions with multilateral institutions for infrastructure funding, though the presentation gives no amount, signing date or final terms for potential arrangements.
HUDCO is setting up a GMTN programme for a maiden international bond offering. This is a stated plan rather than a completed issuance. HUDCO’s disclosed funding strategy also includes allocation of capital gain bonds, while its H1 FY27 loan book stood at Rs 1,86,111 crore, up from Rs 1,44,554 crore in H1 FY26, providing the balance-sheet context for pursuing multiple funding channels.
Conclusion
HUDCO’s H1 FY27 disclosures show a marked expansion in foreign-currency funding: ECB/ODA loans reached Rs 29,088.53 crore and represented 17.70% of Rs 1,64,376.66 crore of total borrowings. The RBI concessional forex-swap window contributed Rs 14,972.93 crore of the Rs 16,618.18 crore foreign-currency amount raised during the half year, while bank loans remained the largest funding source at 43.21%.
Next, readers should watch whether HUDCO converts its stated multilateral discussions, foreign-currency loan exploration and GMTN programme into disclosed transactions. The key unresolved matters are the size, currency, maturity, hedging approach and cost of any maiden international bond, as well as whether funds tied up or under negotiation through the RBI forex-swap window become completed borrowings.