










Ind-Swift H1 EBITDA rises 4.5 times as margin reaches 17.97%
Key highlights
- Ind-Swift’s H1 FY27 operating EBITDA was Rs 75.65 crore, 4.5 times the Rs 16.98 crore reported in H1 FY26.
- Ind-Swift’s operating EBITDA margin rose to 17.97% in H1 FY27 from 5.47%, an increase of 1,249.34 basis points.
- Ind-Swift’s H1 FY27 PAT increased 3.3 times to Rs 55.47 crore, with PAT margin reaching 13.18%.
- Ind-Swift’s total revenue rose 31.83% to Rs 436.20 crore in H1 FY27.
powered by IRIS
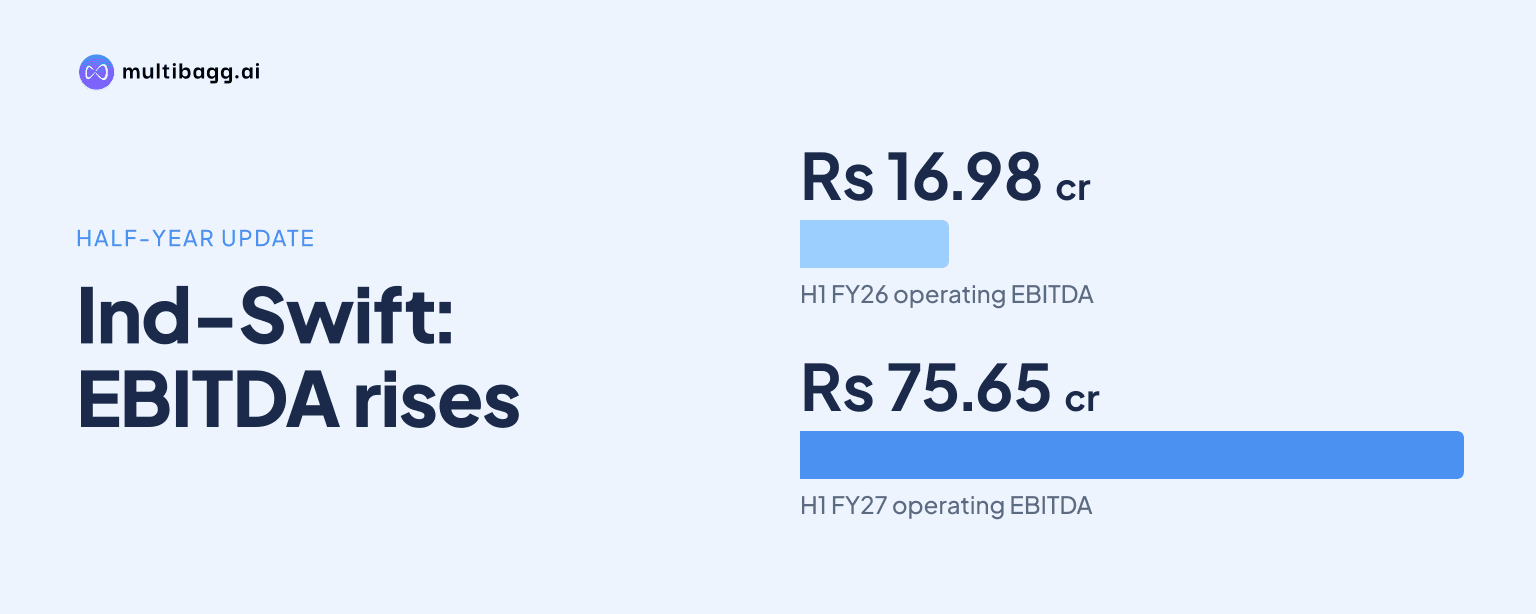
Ind-Swift LABORATORIES Limited reported H1 FY27 operating earnings before interest, tax, depreciation and amortisation (operating EBITDA) of Rs 75.65 crore, 4.5 times H1 FY26, as its operating EBITDA margin rose to 17.97% from 5.47%. Total revenue grew 31.83% to Rs 436.20 crore, while profit after tax (PAT) increased 3.3 times to Rs 55.47 crore.
Know Ind-Swift Laboratories inside out
Results, valuation, peers and who's buying, in one view.
How did Ind-Swift’s H1 FY27 profitability change?
Ind-Swift’s H1 FY27 profitability increased faster than revenue, with operating EBITDA rising by Rs 58.67 crore from Rs 16.98 crore in H1 FY26 to Rs 75.65 crore. Total revenue increased by Rs 105.33 crore to Rs 436.20 crore over the same periods. The operating EBITDA margin expanded by 1,249.34 basis points, where one basis point equals one-hundredth of a percentage point.
PAT rose by Rs 38.59 crore, and its margin increased to 13.18% in H1 FY27 from 5.44% in H1 FY26, a 773.35-basis-point change. Profit before tax (PBT) before exceptional items rose 3.5 times to Rs 73.49 crore from Rs 20.88 crore. Exceptional items were Rs 0.82 crore in H1 FY27, compared with nil in H1 FY26, while tax increased to Rs 17.20 crore from Rs 4.01 crore.
The reported improvement occurred alongside a different income and cost mix. Operating other income declined to Rs 4.63 crore from Rs 11.58 crore, while non-operating other income declined to Rs 15.23 crore from Rs 20.86 crore. Raw-material expense rose to Rs 181.26 crore from Rs 148.50 crore, employee-benefit expense rose to Rs 76.32 crore from Rs 67.73 crore, and other expenses rose to Rs 87.75 crore from Rs 76.94 crore.
What changed between Q1 and Q2 FY27?
Ind-Swift’s Q2 FY27 total revenue increased 25.18% quarter on quarter to Rs 242.49 crore from Rs 193.71 crore in Q1 FY27. Operating EBITDA rose 27.04% to Rs 42.33 crore from Rs 33.32 crore, and the operating EBITDA margin edged up by 11 basis points to 18.02% from 17.91%.
Revenue excluding other income was Rs 230.23 crore in Q2 FY27, compared with Rs 186.12 crore in Q1 FY27. Q2 operating other income was Rs 4.66 crore after negative Rs 0.03 crore in Q1, while non-operating other income was broadly unchanged at Rs 7.60 crore from Rs 7.63 crore. The reported quarter-on-quarter revenue and EBITDA increases were therefore accompanied by both higher operating revenue and higher operating other income.
PAT increased 26.96% quarter on quarter to Rs 31.03 crore in Q2 FY27 from Rs 24.44 crore in Q1 FY27. PBT after exceptional items rose to Rs 40.24 crore from Rs 32.43 crore, while tax increased to Rs 9.21 crore from Rs 7.98 crore. PAT margin reached 13.21% in Q2, compared with 13.13% in Q1 and 8.65% in Q4 FY26.
Got a follow-up? Ask IRIS
How did Ind-Swift’s balance-sheet items move?
Ind-Swift’s total assets increased to Rs 1,754.29 crore in H1 FY27 from Rs 1,530.06 crore in H1 FY26, while total equity rose to Rs 1,460.59 crore from Rs 1,298.66 crore. Reserves and surplus increased by Rs 156.58 crore to Rs 1,373.62 crore, and share capital rose to Rs 86.96 crore from Rs 81.61 crore.
Current assets rose to Rs 918.30 crore from Rs 773.95 crore, led by trade receivables of Rs 234.79 crore versus Rs 168.53 crore and inventories of Rs 168.35 crore versus Rs 102.83 crore. Cash and cash equivalents declined to Rs 322.81 crore from Rs 388.31 crore, whereas investments increased to Rs 45.03 crore from Rs 19.37 crore. Other current assets rose to Rs 147.32 crore from Rs 94.92 crore.
Current liabilities increased to Rs 259.03 crore from Rs 203.98 crore. Trade payables were Rs 133.70 crore, compared with Rs 117.09 crore, and other current liabilities were Rs 118.22 crore, compared with Rs 72.29 crore. Short-term borrowings declined to Rs 4.34 crore from Rs 12.77 crore, while long-term borrowings increased to Rs 15.14 crore from Rs 8.78 crore; capital work in progress was Rs 41.82 crore in H1 FY27 after nil a year earlier.
What are Ind-Swift’s disclosed growth plans?
Ind-Swift has stated a FY30 topline target of more than Rs 1,500 crore, compared with Rs 636 crore cited as the starting scale, implying management’s stated 20% to 25% compound annual growth rate objective. Management also targets operating EBITDA-margin expansion of 200 to 300 basis points through operating leverage and higher utilisation, with a gross-margin mix shift towards domestic ethical products and export own brands.
The company says its contract development and manufacturing organisation, or CDMO, business is expected to deliver Rs 200 crore to Rs 220 crore over two years through commercial scale-ups. Commercial supplies are stated to begin in 2026, with Rs 100 crore to Rs 130 crore of incremental revenue expected in FY27. These are management plans and expected outcomes, rather than reported H1 FY27 revenue.
Ind-Swift also plans more than 300 dossier filings by FY27 and says capacity debottlenecking and regulatory capital expenditure will be funded through internal accruals. Its domestic business objective is 15% to 20% compound annual growth, supported by chronic therapies and a distribution network of 3,000 stockists and 14 carrying and forwarding agents. The presentation additionally identifies field-force and distribution scaling in the United Arab Emirates, Uzbekistan and West Africa.
Conclusion
Ind-Swift’s H1 FY27 figures show that a 31.83% increase in total revenue to Rs 436.20 crore was accompanied by a substantially larger increase in operating EBITDA and PAT. The operating margin rose by 1,249.34 basis points to 17.97%, while the balance sheet showed higher inventories, receivables and current liabilities alongside lower cash and short-term borrowings.
The next disclosed milestones are management’s planned start of CDMO commercial supplies in 2026, its stated Rs 100 crore to Rs 130 crore incremental-revenue expectation for FY27, and more than 300 dossier filings by FY27. The presentation also identifies a 200 to 300 basis-point operating EBITDA-margin expansion objective, making the delivery of higher utilisation and the movement in working-capital balances relevant areas to watch.