










India Glycols Limited: H1 sales rise 26% as margins split
Key highlights
- IGL reported H1 FY27 revenue from operations of Rs 713 crore, up 26% from Rs 568 crore.
- IGL's Bio Based Specialty Materials revenue rose 43% to Rs 382 crore in H1 FY27, but EBITDA margin fell to 16.2% from 20.1%.
- IGL's Sustainable & Performance Chemicals EBITDA increased 40% to Rs 51 crore in H1 FY27 and margin improved to 16.3% from 15.0%.
- IGL said chemicals costs rose 35% to 75% in Q2 FY27 and freight was about double.
powered by IRIS
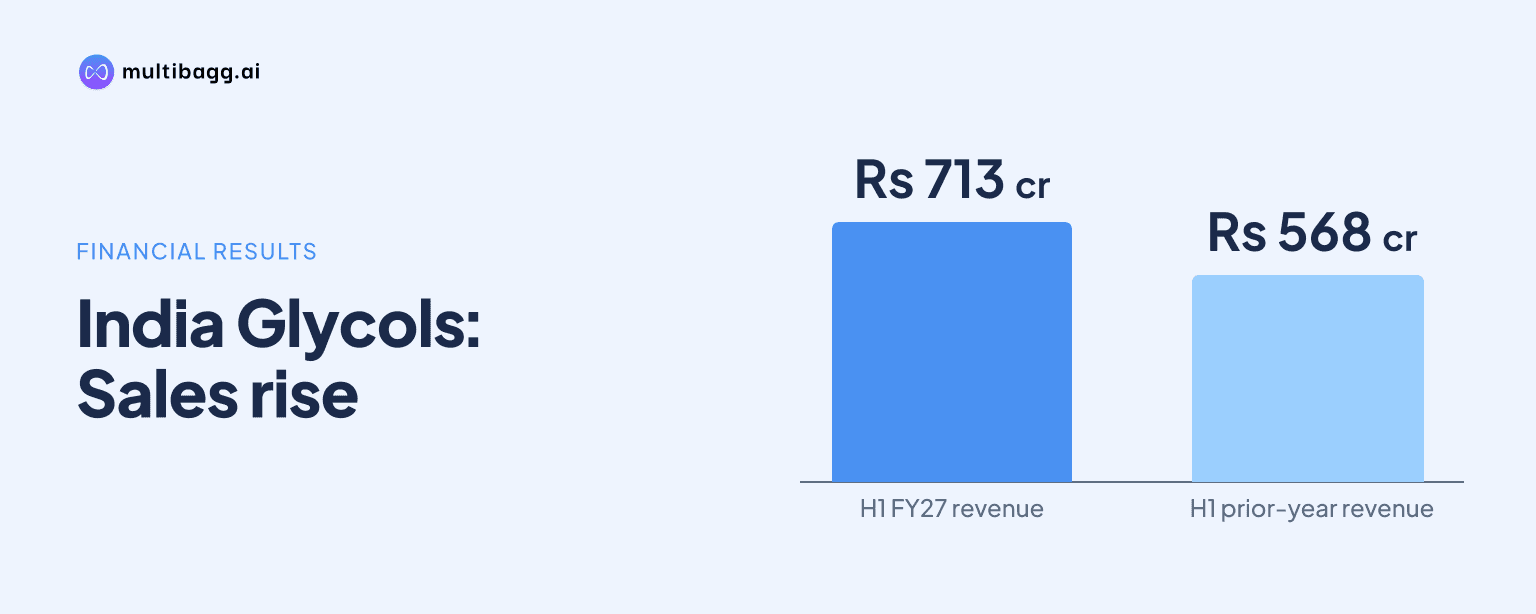
India Glycols Limited reported Rs 713 crore of revenue from operations in H1 FY27, up 26% from Rs 568 crore on a like-for-like basis, but Bio Based Specialty Materials EBITDA margin fell to 16.2% from 20.1% as higher input and freight costs limited profit growth.
Know India Glycols inside out
Results, valuation, peers and who's buying, in one view.
How did IGL's H1 FY27 revenue and EBITDA change?
IGL increased H1 FY27 revenue from operations to Rs 713 crore from Rs 568 crore in H1 FY26, while earnings before interest, tax, depreciation and amortisation, or EBITDA, including joint-venture share, rose 25% to Rs 113 crore from Rs 90 crore. H1 EBITDA margin was 15.8%, and Q2 FY27 revenue increased 30% year on year to Rs 358 crore while EBITDA rose 26% to Rs 52 crore.
Segment revenue growth was led by Bio Based Specialty Materials, including gases, which added Rs 115 crore in H1 FY27 revenue, rising to Rs 382 crore from Rs 267 crore. Sustainable & Performance Chemicals added Rs 70 crore, with revenue rising to Rs 313 crore from Rs 243 crore. IGL presents the H1 FY26 comparison on a like-for-like basis because Spirits & Bio-fuels and Ennature Biopharma were subsequently demerged.
Why did IGL's segment margins diverge in H1 FY27?
IGL's Bio Based Specialty Materials revenue increased 43% in H1 FY27, but its EBITDA rose 15% to Rs 62 crore from Rs 54 crore, reducing the segment margin to 16.2% from 20.1%. The 3.9-percentage-point decline reflected EBITDA growth trailing the Rs 115 crore revenue increase. IGL said Q2 margin pressure came from increased costs and freight, although H1 growth was supported by volume expansion and improved contribution across product categories.
Sustainable & Performance Chemicals increased H1 EBITDA 40% to Rs 51 crore from Rs 36 crore on 29% revenue growth to Rs 313 crore. Its EBITDA margin rose to 16.3% from 15.0%, a 1.3-percentage-point increase. IGL attributed the segment's EBITDA growth exceeding revenue growth to improving operating leverage and a stronger earnings profile.
The Q2 FY27 data showed the same contrast. Bio Based Specialty Materials revenue rose 42% to Rs 194 crore, while EBITDA grew 12% to Rs 28 crore and margin declined to 14.6% from 18.4%. Sustainable & Performance Chemicals revenue increased 36% to Rs 167 crore, EBITDA rose 49% to Rs 24 crore, and margin improved to 14.2% from 13.0%, an expansion of about 124 basis points.
Got a follow-up? Ask IRIS
What costs and market conditions affected IGL in Q2 FY27?
IGL reported that chemicals costs rose 35% to 75% in Q2 FY27, drums and intermediate bulk containers rose 21% to 54%, and freight was about double. Brent crude rose from about US$72 to US$98 during the quarter. These conditions affected the relationship between selling prices and costs across the company's chemicals platforms.
For bio-glycols, IGL said the petrochemical monoethylene glycol, or MEG, price increase narrowed the bio-MEG price gap, but ethanol and ethylene oxide costs did not decline. Freight and a weak Japanese yen also held back margins, while the bio-MEG gap remained about 2.5 times. In glycol ethers and glycol ether acetates, short Gulf supply and a propylene oxide shortage raised competing import prices in India, but IGL said this tailwind was fading and higher costs reduced margins.
Sustainable & Performance Chemicals faced more expensive and scarce propylene oxide, lactic acid and phenol, which IGL classified as a high headwind for both margins and growth. In gases and ethylene oxide, argon recovery was a medium tailwind, while fuel rationing and new capacity were offsetting factors. Despite those operating constraints, the segment's H1 FY27 EBITDA margin increased to 16.3%.
What is IGL planning after H1 FY27?
IGL's disclosed roadmap covers foundation materials, specialty chemical scaling and novel technologies, with management aspiring to Rs 2,000 crore of net revenue and Rs 400 crore of EBITDA in the next four to five years. The Sustainable Specialty Materials platform includes bio-glycols, glycol ethers and esters produced through the bio-based ethylene oxide route, with plans to improve cost, differentiation, markets and applications.
The Sustainable & Performance Chemicals platform includes surfactants, esters, quaternaries, polyglycerols, CarbonSmart chemicals and amines for personal care, crop care, coatings, lubricants, textiles, and oil and gas. Management also described a 10-times sales and profits ambition over 10 years, based on a renewable-carbon strategy rather than acquisitions. These figures are management aspirations, not reported results.
IGL's Kashipur complex covers 300 acres and has 175,000 tonnes per annum of glycols capacity, 70,000 tonnes per annum of glycol ethers capacity and 7,500 tonnes per annum of new-specialties capacity. About 35% of IGL cargo is routed through the Kashipur inland container depot, with rail-linked export gateways about 1,500 kilometres away at Mundra, Pipavav and Nhava Sheva. IGL identifies multi-source ethanol procurement, captive bio-ethylene and ethylene oxide, and rail access as mechanisms for supply and cost management.
Conclusion
IGL's H1 FY27 performance combined 26% revenue growth with different margin outcomes across its two main chemicals platforms. Bio Based Specialty Materials produced the faster 43% revenue increase to Rs 382 crore, but its margin fell to 16.2%; Sustainable & Performance Chemicals grew revenue 29% to Rs 313 crore and expanded its margin to 16.3%.
The next issue is whether the Q2 pressures on inputs, packaging and freight persist, particularly chemicals cost increases of 35% to 75% and freight that was about double. Management's disclosed four-to-five-year aspiration of Rs 2,000 crore in net revenue and Rs 400 crore in EBITDA will also depend on progress in cost improvement, product development and the stated scaling of Sustainable & Performance Chemicals.