










Indo Count expects to exceed FY27 revenue and EBITDA guidance
Key highlights
- H1 FY27 total income was Rs 2,923 crore, approximately 53% of Indo Count’s Rs 5,500 crore annual guidance.
- H1 FY27 EBITDA margin reached 14.4%, above Indo Count’s 13% full-year guidance.
- Q2 FY27 income increased 57% year on year to Rs 1,699 crore, while EBITDA rose to Rs 259 crore from Rs 123 crore.
- New businesses generated Rs 890 crore in H1 FY27, nearly 60% of their approximately Rs 1,500 crore FY27 target.
powered by IRIS
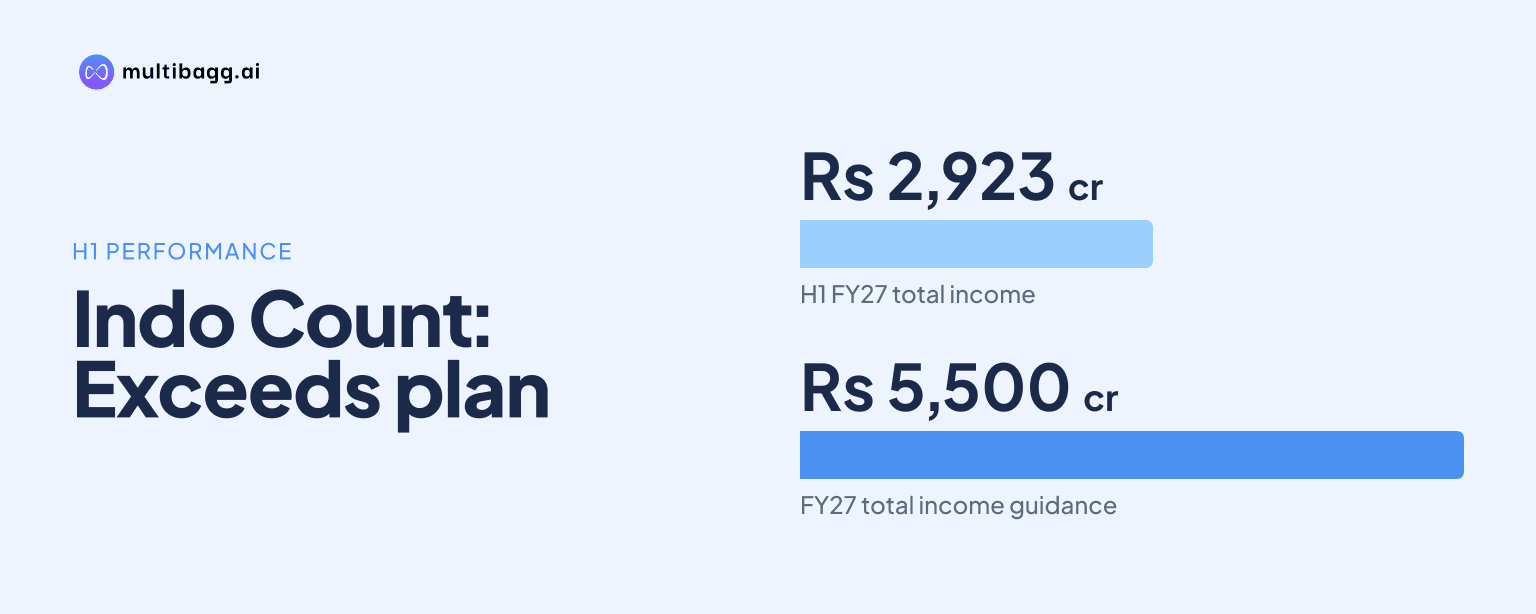
Indo Count Industries Limited said on November 5, 2026, that it expects to exceed FY27 revenue and EBITDA guidance after H1 total income reached Rs 2,923 crore, or 53% of its Rs 5,500 crore target, while EBITDA margin reached 14.4%, 140 basis points above its 13% full-year guidance.
Know Indo Count Industries inside out
Results, valuation, peers and who's buying, in one view.
Why does Indo Count expect to exceed FY27 guidance?
Indo Count expects to exceed FY27 guidance because its first-half revenue crossed half of the annual target and its EBITDA margin was already above the full-year target. Management said H1 volume was 51 million metres, about 49% of its 105 million to 110 million metres guidance, while total income reached Rs 2,923 crore, about 53% of the Rs 5,500 crore revenue target.
The company did not announce revised numerical targets for FY27. Its stated guidance remains Rs 5,500 crore of total income, 105 million to 110 million metres of volume and a 13% EBITDA margin. Management said the H1 result provided a strong foundation and made it confident of outperforming guidance on both revenue and EBITDA.
Revenue progress was ahead of volume progress in H1, with 53% of the income target achieved against about 49% of the volume range. Q2 FY27 total income of Rs 1,699 crore was also 39% higher sequentially, according to management, which attributed growth to market-share gains, higher customer wallet share and a rising contribution from newer businesses.
How did Indo Count’s Q2 and H1 profits change?
Indo Count’s profitability increased faster than income in Q2 and H1 FY27, expanding EBITDA margins in both periods. Q2 EBITDA more than doubled to Rs 259 crore from Rs 123 crore in Q2 FY26, while the margin rose by 380 basis points to 15.3% from 11.5% a year earlier.
For H1 FY27, EBITDA grew 73% to Rs 420 crore from Rs 243 crore in H1 FY26, and the margin increased by 250 basis points to 14.4%. Management attributed the improvement to higher capacity utilisation, better cost absorption and operational efficiencies.
Profit after tax reached Rs 132 crore in Q2 FY27, compared with Rs 39 crore in Q2 FY26, and H1 profit after tax rose 150% to Rs 195 crore from Rs 78 crore. Management described Q2 as Indo Count’s highest-ever quarterly performance, citing strategic investments, portfolio expansion and greater use of existing assets.
Which businesses are driving Indo Count’s FY27 progress?
Indo Count’s new businesses are moving faster towards their FY27 revenue target than the core business. Core business revenue was Rs 2,033 crore in H1 FY27, about 50% of its Rs 4,000 crore target, whereas new-business revenue was Rs 890 crore, nearly 60% of its approximately Rs 1,500 crore target.
New businesses generated approximately Rs 502 crore in Q2 FY27, contributing about 30% of total income. The portfolio includes utility bedding, branded businesses, quilts, comforters, blankets, towels and curtains, alongside Indo Count’s bed-linen operations.
During Q2, the Wamsutta brand moved beyond its direct-to-consumer platform into broader U.S. retail markets. Management said this was intended to widen distribution and consumer reach, while all three U.S. utility-bedding facilities had ramped up to utilisation of more than 65%.
Outside the U.S., Indo Count expects non-U.S. revenue to grow by more than 20% in FY27. Management said the U.K. and European Union offer an addressable opportunity comparable to the U.S., and stated that non-U.S. sales accounted for around 30% of the core business at the time of the call.
Got a follow-up? Ask IRIS
What could influence Indo Count’s second-half performance?
Input-cost movements and the Bhilad insurance settlement could influence Indo Count’s second-half results. Management said cotton and cotton-related prices had increased, but it typically holds four to five months of inventory and seeks price increases from customers when cost changes are significant.
Management said earlier raw-material cost increases had already been passed on, with adjustments typically taking one quarter or one to two quarters. It said this process meant the recent increase was not expected to have a major effect on profitability or margins, while noting that gross margin can fluctuate quarterly with product mix and should be assessed annually.
Unprecedented rainfall and flooding temporarily affected the Bhilad manufacturing facility in Gujarat during Q2 FY27. Indo Count recognised an inventory loss of Rs 45.02 crore, net of salvage, and an equal insurance claim as an exceptional item; the insurer acknowledged the claim and approved an interim payment of Rs 14.99 crore after the quarter ended, pending final settlement.
The balance sheet also changed during H1 FY27, with net debt declining to Rs 518 crore as of September 2026 from a position management called its lowest ever. Cash and cash equivalents rose to Rs 315 crore from Rs 114 crore at the end of March 2026, while net debt to equity stood at 0.2 times, annualised return on capital employed was 21.4% and return on equity was 15.3%.
Conclusion
Indo Count’s expectation of exceeding FY27 guidance is supported by first-half delivery across income, margin and new businesses. H1 income of Rs 2,923 crore represented 53% of the annual target, the 14.4% EBITDA margin exceeded the 13% guide, and new businesses reached nearly 60% of their FY27 revenue objective.
The next points to watch are the final settlement of the Rs 45.02 crore Bhilad insurance claim, progress in U.S. utility-bedding utilisation above 65%, and management’s next-year guidance. Management said it would return with proper numbers and guidance for the following year while maintaining its stated aim of doubling revenue from Rs 4,000 crore in FY25 to Rs 8,000 crore by calendar year 2028.