










Jyoti Resins Q2 EBITDA Margin Rebounds to 23% From 14.4%
Key highlights
- Jyoti Resins’ Q2 FY27 EBITDA margin rose to 23.0% from 14.4% in Q1 FY27.
- Q2 FY27 operating EBITDA increased 77.7% sequentially to Rs 22.50 crore on net sales of Rs 97.67 crore.
- H1 FY27 EBITDA was Rs 35.15 crore, compared with Rs 41.11 crore in H1 FY26.
- Management expects a 24% to 25% H2 FY27 EBITDA margin, subject to raw-material prices not rising sharply.
powered by IRIS
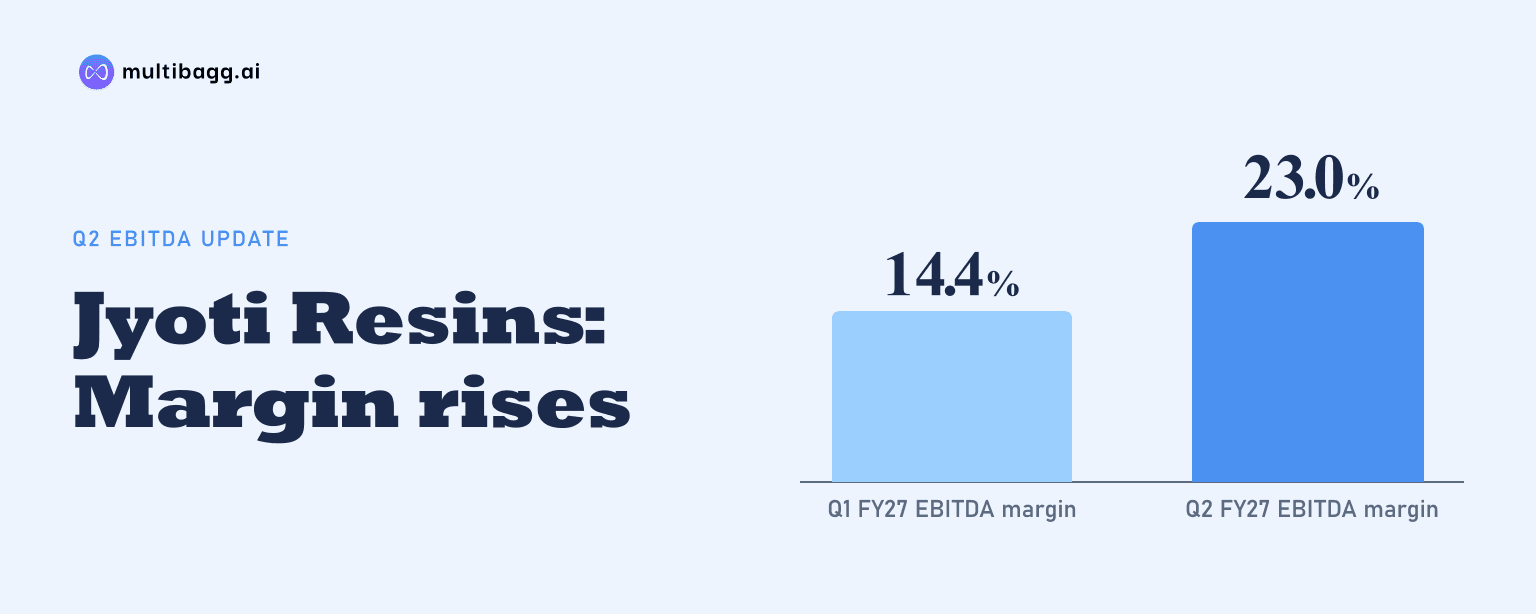
In Q2 FY27, Jyoti Resins and Adhesives Limited reported an EBITDA, or earnings before interest, tax, depreciation and amortisation, margin of 23.0%, up from 14.4% in Q1 FY27, as Q1 price increases improved realisations; operating EBITDA rose 77.7% sequentially to Rs 22.50 crore on net sales of Rs 97.67 crore.
Know Jyoti Resins and Adhesives inside out
Results, valuation, peers and who's buying, in one view.
Why did Jyoti Resins’ EBITDA margin rise in Q2 FY27?
Jyoti Resins’ Q2 FY27 margin rose because price increases taken in Q1 FY27 had a positive effect on realisations during the quarter. The company said the EBITDA margin bounced back from 14.4% in Q1 FY27 to 23.0% in Q2 FY27, a sequential gain of 8.6 percentage points in a seasonally weak quarter.
Volume growth and price increases both contributed to the 31.3% year-on-year increase in Q2 FY27 revenue. Jyoti Resins reported about 15% volume growth over a strong Q2 FY26 base, while net sales reached Rs 97.67 crore, compared with Rs 87.71 crore in Q1 FY27 and Rs 74.38 crore in Q2 FY26.
The recovery in profitability was larger sequentially than the rise in sales. Operating EBITDA increased from Rs 12.66 crore in Q1 FY27 to Rs 22.50 crore in Q2 FY27, whereas expenditure was almost unchanged at Rs 75.17 crore from Rs 75.05 crore. That movement is consistent with the company’s stated improvement in realisations after its Q1 price action.
How did Jyoti Resins’ Q2 FY27 earnings compare with prior periods?
Jyoti Resins’ Q2 FY27 operating profit recovered sharply from Q1 FY27, but its margin remained below the 27.5% reported in Q2 FY26. Net sales were up 11.4% quarter on quarter and 31.3% year on year, while EBITDA was up 77.7% sequentially but only 9.9% from the prior-year quarter.
Year on year, expenditure rose 39.4% to Rs 75.17 crore, exceeding the 31.3% growth in sales. This explains why Q2 FY27 EBITDA grew more slowly than revenue and why the 23.0% EBITDA margin was 4.5 percentage points lower than Q2 FY26’s 27.5%. The presentation identifies better realisations from price increases as the driver of the sequential improvement, rather than stating that costs declined.
Profit after tax, or PAT, reached Rs 18.48 crore in Q2 FY27, up 57.3% from Rs 11.75 crore in Q1 FY27 and 7.7% from Rs 17.16 crore in Q2 FY26. PAT margin similarly improved from 13.4% sequentially to 18.9%, but stayed below the 23.1% reported a year earlier. Reported earnings per share were Rs 15 in Q2 FY27, compared with Rs 10 in Q1 FY27 and Rs 14 in Q2 FY26.
Got a follow-up? Ask IRIS
What does Jyoti Resins’ H1 FY27 performance show?
Jyoti Resins’ first-half FY27 results show that Q2’s margin recovery did not fully offset the weaker first quarter. For H1 FY27, net sales increased to Rs 185.37 crore from Rs 149.48 crore in H1 FY26, while EBITDA declined to Rs 35.15 crore from Rs 41.11 crore.
The resulting H1 FY27 EBITDA margin was 19.0%, versus 27.5% in H1 FY26. H1 expenditure rose to Rs 150.22 crore from Rs 108.37 crore, while sales increased by a smaller absolute amount than the rise in expenditure. The half-year comparison therefore differs from Q2’s sequential pattern, where nearly flat expenditure accompanied higher revenue and EBITDA.
H1 FY27 profit before tax was Rs 40.35 crore, down from Rs 46.36 crore in H1 FY26, and PAT was Rs 30.23 crore compared with Rs 34.54 crore. The H1 PAT margin was 16.3%, against 23.1% a year earlier, and reported earnings per share were Rs 25 compared with Rs 29. Net cash flow from operating activities stood at Rs 46.16 crore, according to the presentation.
What is Jyoti Resins’ margin outlook and operating expansion plan?
Jyoti Resins expects EBITDA margin of 24% to 25% in H2 FY27, subject to no further sharp increase in raw-material prices. Management said the raw material it identifies as VAM remains volatile because freight rates are affected by the current geopolitical scenario; the stated H2 margin range is therefore conditional rather than a firm forecast.
The company completed a brownfield expansion, taking capacity to 3,500 metric tonnes per month, annualised to 42,000 metric tonnes per annum, in October 2026. This capacity position coincides with Q2 FY27 expansion into Odisha, taking Jyoti Resins’ presence to 16 states and its branch network to 61 from 54 in Q1 FY27.
Distribution and field coverage also expanded during Q2 FY27. The sales force increased to about 650 members from 562 in Q1 FY27, the retailer base reached 14,000, and carpenter reach was 355,000. The active carpenter base was 212,000, while the product range presented includes Euro 7000 wood adhesive, PVC Glue, XTRA, ULTRA 5in1, WP 2in1 and Extreme 3.
Conclusion
Jyoti Resins’ Q2 FY27 figures show a sequential restoration in profitability: the EBITDA margin rose 8.6 percentage points to 23.0%, operating EBITDA increased 77.7% to Rs 22.50 crore, and PAT rose 57.3% to Rs 18.48 crore. Against Q2 FY26, however, revenue grew faster than EBITDA and the margin remained 4.5 percentage points lower, leaving H1 FY27 EBITDA at Rs 35.15 crore versus Rs 41.11 crore a year earlier.
The next measure is whether Jyoti Resins can reach management’s stated 24% to 25% H2 FY27 EBITDA-margin range without another sharp increase in raw-material prices. Investors can also track how the October 2026 capacity expansion to 42,000 metric tonnes per annum, the move into Odisha, and the increase to 61 branches translate into sales and profitability in the remaining FY27 quarters.