










Kissht plans property, gold and auto loans for three-year mix
Key highlights
- Kissht said non-unsecured products should make a sizable contribution over the next three years.
- Management discussed expanding the book from about Rs 9,000 crore to Rs 30,000 crore.
- Kissht's average personal-loan ticket was cited at Rs 34,000 a year earlier and Rs 41,000 currently.
- Management said less than 5% of loans are between Rs 2 lakh and Rs 3 lakh, its stated ticket-size ceiling.
powered by IRIS
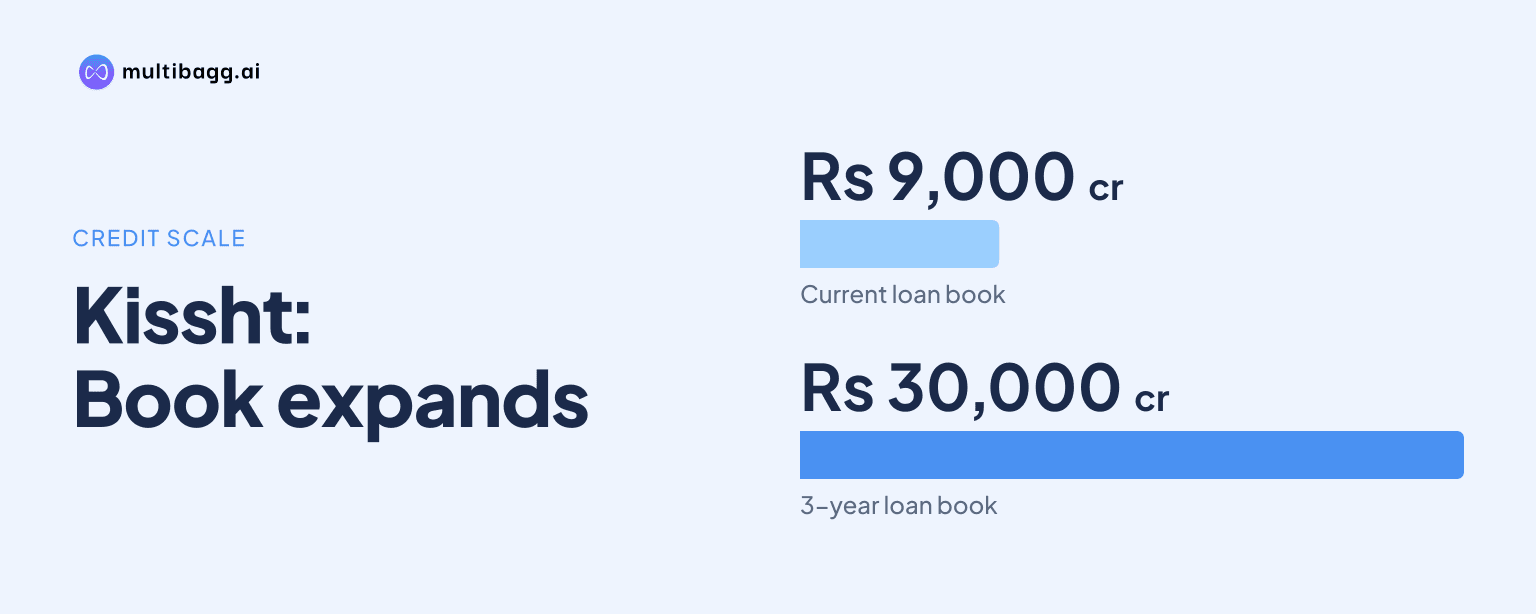
Kissht plans to make loan against property, gold loans and auto loans a sizable non-unsecured contribution over the next three years while discussing a path from about Rs 9,000 crore to Rs 30,000 crore. Management said unsecured personal loans will remain in the mix, supported by technology-led underwriting and risk-based pricing.
Know Onemi Technology Solutions inside out
Results, valuation, peers and who's buying, in one view.
What products will Kissht add beyond unsecured personal loans?
Kissht intends to build loan against property (LAP), gold loans and auto loans alongside unsecured personal loans. Management said its three-year strategy “cannot be only” personal loans and pointed to Kissht's investment in LAP, while saying it has been studying gold and auto loans carefully. It did not disclose a launch timetable or product-level book targets for gold and auto loans.
The strategy is connected to management's illustrative expansion from about Rs 9,000 crore to Rs 30,000 crore. Management said adding products would not mean exiting its existing personal-loan borrowers. Instead, it expects the product mix to broaden as the book grows, including a sizable contribution from non-unsecured lending.
How will Kissht change its customer mix and pricing?
Kissht expects a higher share of lower-risk borrowers while continuing to price loans by risk across customer groups. Management said more than 20% to 25% of customers belong to a pool with eventual risk below 3%, compared with the 6.2% risk measure it cited for the overall book. It said borrower income alone is not a sufficient risk indicator.
Management illustrated that a borrower earning Rs 50,000 a month may sometimes be a better risk than one earning Rs 2.5 lakh to Rs 3 lakh a month. It also said a customer segment with risk around 6%, estimated at 50% to 60% of the mix currently, could fall to around 20% to 30% when the book reaches Rs 30,000 crore. Management said Kissht would continue to serve that segment rather than reject it outright.
Krishnan Vishwanathan said the higher-quality, higher-income segment, currently about 20% of the mix, could rise to more than 50%. That expectation is management's view of a gradual mix shift, not a reported target for a specific quarter. The stated mechanism is risk-based pricing and improved identification of customer signals, rather than an income-based rule alone.
How are Kissht's personal-loan tickets and tenures changing?
Kissht said personal-loan ticket sizes and tenures are increasing incrementally. Krishnan Vishwanathan cited an average ticket size of Rs 34,000 a year earlier and Rs 41,000 currently, a rise of Rs 7,000. He attributed the movement to a larger share of repeat customers, higher-quality and higher-income borrowers, nominal growth and inflation.
Management said repeat customers generally receive larger loans than on their earlier exposures. It also cited an increase in average tenure from 14 months to 16 to 17 months. Krishnan Vishwanathan said Kissht would not abruptly change a model developed for specific income bands, loan tenures and products.
The call included a second current ticket-size reference. Ranvir Singh described the average ticket as Rs 43,000, while Krishnan Vishwanathan cited Rs 41,000 in the one-year comparison. Ranvir Singh also said the maximum ticket size was Rs 3 lakh and that less than 5% of loans were between Rs 2 lakh and Rs 3 lakh, placing the reported ticket-size trend within a stated ceiling.
Got a follow-up? Ask IRIS
How will Kissht manage risk in new loan categories?
Kissht says technology-led processes, underwriting and frequent portfolio adjustments will guide risk management as products expand. Management said its LAP build is process-driven and uses artificial intelligence (AI) to support staff interactions and the customer journey. It described technology investment as a means to reduce risk while scaling the book toward Rs 30,000 crore.
Management said it uses a location framework from A to D and rejects locations beyond that range, with upgrades and downgrades made regularly. It identified an issue among self-employed revolving borrowers in some locations where exposure is between Rs 25,000 and Rs 40,000. Those adjustments were presented as ongoing portfolio actions rather than a new product-policy disclosure.
Kissht reported overlap with microfinance institution borrowers of less than 3.4%, overlap with Kisan Credit Card borrowers of less than 2.6%, and customers with overlapping gold loans at under 8%. It also said drought-affected areas accounted for less than 6% of the portfolio. Management characterized risk in these segments as superior or average, which was its assessment rather than an independently reported performance measure.
What could the strategy mean for Kissht's operating model?
Kissht expects scale and larger-ticket lending to create some efficiency, while retaining spending on technology-led collections when needed. Management said almost 50% of current costs are indirect and could become almost half over roughly six quarters if the business doubles. It said doubling could occur over about 18 months, but presented that timeframe as an expectation.
Management estimated a potential benefit of around 2.5% to 3% over six quarters from this cost structure. Its more conservative guidance was operating-expense improvement of 25 to 40 basis points each quarter. Management also said collection effort on a higher instalment can be similar to that on a smaller instalment, though it cautioned that this would not be the main source of operating leverage.
On capital, management said it did not envisage further fundraising before the book reaches Rs 30,000 crore, starting from Rs 9,317 crore. It said 75% of recently raised preferential-issue proceeds would be infused into the subsidiary for balance-sheet funding and growth. The remaining 25% was earmarked for corporate expenses, AI investment and first-loss default guarantee commitments to support off-book scaling.
Conclusion
Kissht's three-year strategy combines a broader lending mix with a planned change in borrower composition, rather than a withdrawal from unsecured personal loans. Management's case rests on building LAP, gold-loan and auto-loan activity, raising the share of higher-quality customers from about 20% toward more than 50%, and maintaining risk-based pricing as the book moves from about Rs 9,000 crore toward Rs 30,000 crore.
The next measures to watch are management's execution against its stated 18-month potential doubling timeframe, the emergence of a sizable non-unsecured contribution, and ticket-size and tenure trends from the Rs 41,000 and 16-to-17-month levels cited on the call. Management also expects 25 to 40 basis points of quarterly operating-expense improvement and has said no further fundraising is envisaged before Rs 30,000 crore.