










Knowledge Realty Trust sees demand exceed supply through 2028
Key highlights
- KRT projects Indian Grade-A absorption of 99 msf in CY28P against supply of 75 msf.
- Bengaluru is forecast to record 26 msf of absorption and 22 msf of supply in CY28P.
- Mumbai market rent is projected to reach Rs 203 psf pm in CY28P.
- Hyderabad vacancy is forecast to decline from 27% in CY25 to 24% in CY28P.
powered by IRIS
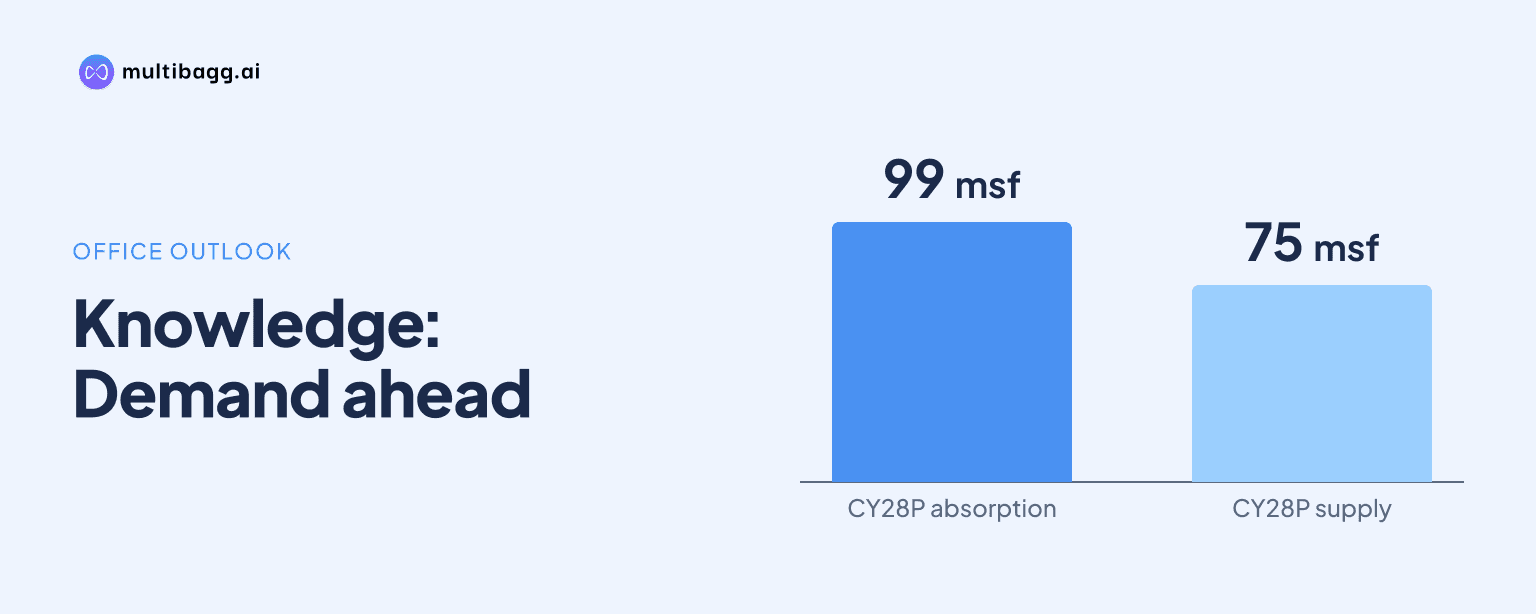
Knowledge Realty Trust projects Indian Grade-A office gross absorption of 99 million square feet (msf) in CY28P, exceeding projected supply of 75 msf by 24 msf. Its outlook shows vacancy falling to 17%, while Bengaluru, Hyderabad and Mumbai are each forecast to record higher rents by CY28P.
Know Knowledge Realty Trust inside out
Results, valuation, peers and who's buying, in one view.
Will KRT expect Indian Grade-A office demand to exceed supply through 2028?
Yes. KRT forecasts national Grade-A gross absorption of 88 msf against supply of 67 msf in CY26P, 96 msf against 78 msf in CY27P, and 99 msf against 75 msf in CY28P. The projected demand-supply gap is therefore 21 msf in CY26P, 18 msf in CY27P and 24 msf in CY28P, while vacancy is projected at 18%, 18% and 17%, respectively.
The forecast follows a recovery from the COVID period shown in the presentation. National gross absorption declined from 67 msf in CY19 to 37 msf in CY20, then increased to 81 msf in CY24 and 83 msf in CY25; supply was 47 msf in CY24 and 58 msf in CY25. Vacancy reached 21% in CY21, CY22 and CY23 before declining to 19% in CY24 and CY25.
The three months ended September 30, 2026 provide the latest market snapshot in the presentation. Pan-India gross absorption was 21 msf against 19 msf of supply, with office stock of 984 msf and vacancy of 18%. Hyderabad and Bengaluru each accounted for 25% of quarterly absorption, while Hyderabad accounted for 54% of quarterly supply.
What does KRT forecast for Bengaluru offices through CY28P?
KRT forecasts Bengaluru gross absorption of 23 msf in CY26P, 25 msf in CY27P and 26 msf in CY28P, compared with supply of 21 msf, 22 msf and 22 msf. The projected absorption surplus rises from 2 msf in CY26P to 3 msf in CY27P and 4 msf in CY28P. This follows 22 msf of absorption and 16 msf of supply in CY25.
Bengaluru vacancy is projected at 17% in each year from CY26P to CY28P, versus 16% in CY23 through CY25. KRT projects market rent to rise from Rs 96 per square foot per month (psf pm) in CY25 to Rs 100 in CY26P, Rs 105 in CY27P and Rs 110 in CY28P. KRT reports 15.3 msf of completed Bengaluru area, 9.2 msf of under-construction and future development area, and 18 assets in the city.
How does KRT's Hyderabad outlook compare with Bengaluru?
KRT forecasts Hyderabad absorption of 15 msf in CY26P, 14 msf in CY27P and 13 msf in CY28P, against supply of 14 msf, 14 msf and 12 msf. Unlike Bengaluru, Hyderabad absorption is projected to decline after CY26P, although supply also declines. Demand exceeds supply by 1 msf in CY26P and CY28P, while both measures are 14 msf in CY27P.
Hyderabad vacancy is projected to fall from 27% in CY25 to 26% in CY26P, 25% in CY27P and 24% in CY28P. Market rent is forecast to increase from Rs 76 psf pm in CY25 to Rs 84, Rs 88 and Rs 91 across the three projected years. KRT has three Hyderabad assets, 12.9 msf of completed area and 99% committed occupancy; 82% of its Hyderabad stock is in HITEC City.
Got a follow-up? Ask IRIS
What is KRT forecasting for Mumbai office space?
KRT forecasts Mumbai absorption of 9 msf in CY26P, 18 msf in CY27P and 19 msf in CY28P, while projected supply is 4 msf, 10 msf and 12 msf. The resulting gap expands from 5 msf in CY26P to 8 msf in CY27P, before narrowing to 7 msf in CY28P. In CY25, Mumbai recorded 15 msf of absorption and 5 msf of supply.
Mumbai vacancy is projected to remain at 15% in CY26P before declining to 13% in CY27P and 12% in CY28P. KRT forecasts market rent of Rs 179 psf pm in CY26P, Rs 190 in CY27P and Rs 203 in CY28P, compared with Rs 164 in CY25. The CY28P rental forecast exceeds Bengaluru's Rs 110 psf pm and Hyderabad's Rs 91 psf pm.
How are KRT's core-market forecasts linked to its portfolio?
KRT's three core markets are forecast to generate combined absorption of 47 msf against supply of 39 msf in CY26P, widening to 58 msf against 46 msf in CY28P. Bengaluru represents 26 msf of projected CY28P absorption, followed by Mumbai at 19 msf and Hyderabad at 13 msf. Mumbai has the largest projected city-level absorption-supply difference in CY28P at 7 msf.
KRT's office portfolio comprises 37.3 msf of completed area and 46.5 msf of total leasable area, including 9.2 msf of under-construction and future development area. Committed occupancy is 93%, while reported market rent is Rs 122 psf pm against in-place rent of Rs 101 psf pm. In the Q3 CY26 snapshot, Hyderabad recorded 5 msf of absorption and 10 msf of supply, compared with Bengaluru's 5 msf and 4 msf, and Mumbai's 3 msf and 0 msf.
Conclusion
KRT's market outlook anticipates that national Grade-A office demand will continue to exceed supply through CY28P, with the gap reaching 24 msf and vacancy declining to 17%. Bengaluru is forecast to have the largest core-market absorption, Mumbai the highest projected rent, and Hyderabad a lower vacancy rate than in CY25 despite its higher starting vacancy.
The next measures to watch are the CY26P, CY27P and CY28P absorption and supply outcomes, particularly in Hyderabad after 10 msf of Q3 CY26 supply. KRT also reports 9.2 msf of under-construction and future development area in Bengaluru, making leasing progress, committed occupancy and market rents in that market relevant to the outlook.