










KSH International EBITDA per tonne triples to Rs 97,600
Key highlights
- KSH International reported EBITDA per tonne of Rs 97,600 in H1 FY27, compared with Rs 32,326 in FY23.
- KSH International's H1 FY27 EBITDA was Rs 164.1 crore, up 89.93% year on year.
- KSH International reported H1 FY27 revenue of Rs 2,483.9 crore, up 95.45% year on year.
- KSH International plans up to Rs 185 crore of investment for a 22% specialised-wire capacity increase by Q1 FY2029.
powered by IRIS
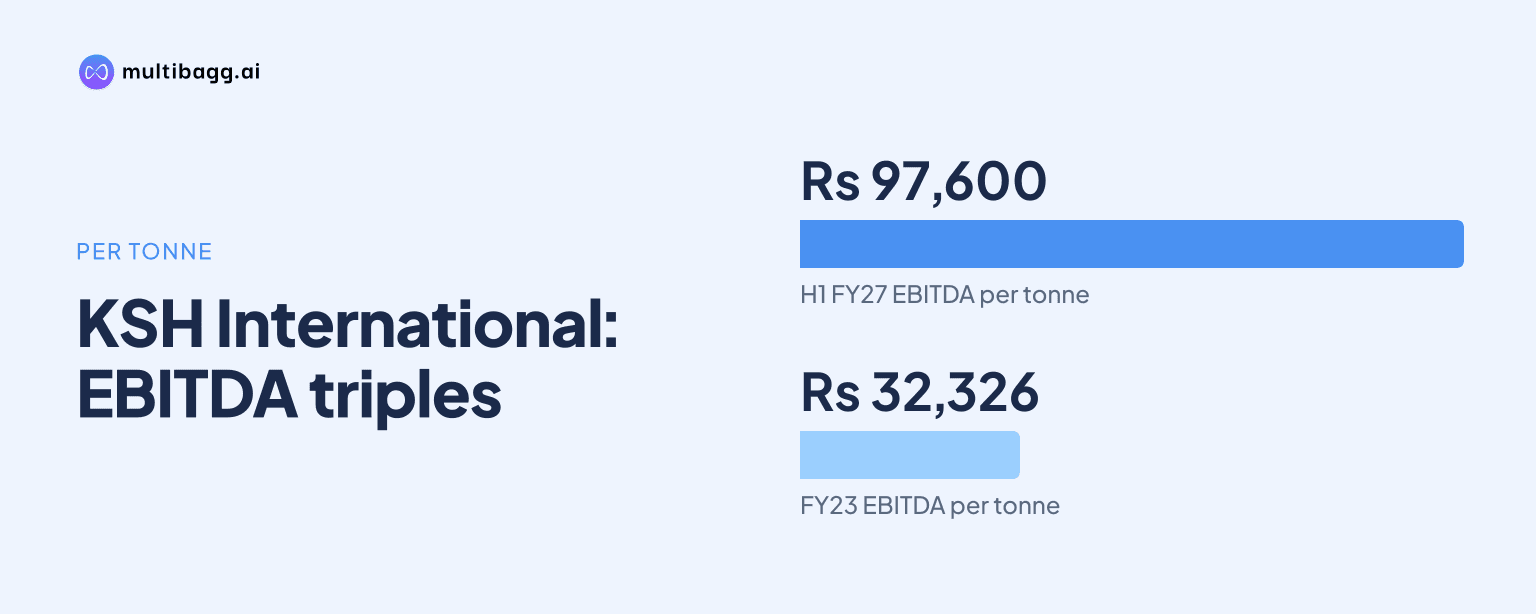
KSH International Limited reported EBITDA per tonne of Rs 97,600 in H1 FY27, three times the Rs 32,326 reported in FY23, while EBITDA margin reached 6.61%. H1 FY27 EBITDA rose 89.93% year on year to Rs 164.1 crore, and debt-to-equity stood at 0.38.
Know KSH International inside out
Results, valuation, peers and who's buying, in one view.
How has KSH International's EBITDA per tonne changed?
KSH International's reported EBITDA per tonne increased by Rs 65,274 from FY23 to H1 FY27, reaching Rs 97,600 from Rs 32,326. The metric was Rs 33,244 in FY24, Rs 52,536 in FY25 and Rs 67,625 in FY26. H1 FY27 is a six-month period rather than a full financial year, but it records the highest EBITDA-per-tonne figure in the presented series.
The per-tonne measure rose alongside total EBITDA, which increased from Rs 49.9 crore in FY23 to Rs 71.5 crore in FY24, Rs 122.5 crore in FY25 and Rs 192.1 crore in FY26. KSH International reported Rs 164.1 crore of EBITDA in H1 FY27. The presentation does not disclose production volumes or identify operational drivers for the change in EBITDA per tonne.
KSH International's EBITDA margin increased by 1.86 percentage points from 4.75% in FY23 to 6.61% in H1 FY27. The annual trend was not continuous: margin rose to 6.35% in FY25 before declining to 6.18% in FY26. EBITDA means earnings before interest, tax, depreciation and amortisation.
What happened to KSH International's revenue and profit?
KSH International's revenue from operations rose from Rs 1,049.5 crore in FY23 to Rs 3,107 crore in FY26, while H1 FY27 revenue was Rs 2,483.9 crore. Revenue moved from Rs 1,382.8 crore in FY24 to Rs 1,928.3 crore in FY25 before reaching the FY26 level. H1 FY27 revenue was 95.45% higher than Rs 1,270.9 crore in H1 FY26.
Profit after tax, or PAT, increased from Rs 26.6 crore in FY23 to Rs 110.1 crore in FY26. KSH International reported PAT of Rs 37.4 crore in FY24, Rs 68 crore in FY25 and Rs 90.2 crore in H1 FY27. The H1 FY27 result was 72.51% above Rs 52.3 crore in H1 FY26, while PAT margin was 3.63%, compared with 4.11% a year earlier.
KSH International's H1 FY27 gross profit increased 79.64% year on year to Rs 252.7 crore, but gross margin declined to 10.17% from 11.07% in H1 FY26. EBITDA rose faster than gross profit, increasing 89.93% from Rs 86.4 crore to Rs 164.1 crore. However, EBITDA margin was 6.61%, below 6.80% in the prior-year half.
How did KSH International perform in Q2 FY27?
KSH International reported Q2 FY27 revenue from operations of Rs 1,319.7 crore, up 85.33% from Rs 712.1 crore in Q2 FY26 and 13.35% from Rs 1,164.2 crore in Q1 FY27. Q2 FY27 EBITDA was Rs 89.8 crore, up 94.79% year on year and 20.69% quarter on quarter. EBITDA margin was 6.80%, compared with 6.47% a year earlier and 6.39% in Q1 FY27.
KSH International's Q2 FY27 PAT was Rs 48 crore, compared with Rs 29.6 crore in Q2 FY26 and Rs 42.2 crore in Q1 FY27. PAT increased 62.16% year on year and 13.74% quarter on quarter, while the margin was 3.63%. That margin was below 4.16% in Q2 FY26 and unchanged from Q1 FY27.
Q2 FY27 gross profit was Rs 136.5 crore, up 80.55% from Rs 75.6 crore in Q2 FY26 and 17.37% from Rs 116.3 crore in Q1 FY27. Gross margin was 10.34%, compared with 10.62% a year earlier. Finance costs rose to Rs 22.3 crore from Rs 9.3 crore in Q2 FY26 and Rs 17.3 crore in Q1 FY27.
Got a follow-up? Ask IRIS
What changed in KSH International's leverage and balance sheet?
KSH International reported debt-to-equity of 0.38 in H1 FY27, compared with 0.39 in FY26 and 1.21 in FY25. The ratio was 0.62 in FY23 and 0.90 in FY24 before reaching the FY25 level. Return on equity, or ROE, was 24.98% in H1 FY27, while return on capital employed, or ROCE, was 21.13%, compared with 19.90% and 16.17% respectively in FY26.
Total assets were Rs 1,755.4 crore in H1 FY27, up from Rs 1,322.6 crore at FY26 end. Inventories increased to Rs 542 crore from Rs 424.9 crore, and trade receivables rose to Rs 586.4 crore from Rs 332.7 crore. Total equity increased to Rs 898.9 crore at H1 FY27 from Rs 808.1 crore at FY26 end.
KSH International had Rs 22.9 crore of non-current borrowings and Rs 318.4 crore of current borrowings in H1 FY27. At FY26 end, non-current borrowings were Rs 26 crore and current borrowings were Rs 290.2 crore. Trade payables rose to Rs 418.3 crore from Rs 123.5 crore, while total current liabilities increased to Rs 791.1 crore from Rs 476.9 crore.
What is KSH International planning at Supa?
KSH International plans a brownfield expansion and land acquisition at Supa, Ahilyanagar, involving capital investment of up to Rs 185 crore and expected completion in Q1 FY2029. The project is designed to increase specialised-wire capacity by 22%, from 59,045 metric tonnes after Phase II to 72,200 metric tonnes after expansion.
Management identifies transformers, railways, renewable energy and electric vehicles as applications for specialised wires. Its stated rationale includes maintaining supply continuity for large original equipment manufacturer customers with multi-year backlogs, increasing the long-term specialised-wire mix, supporting export penetration and improving readiness for larger orders. The presentation does not disclose revenue, utilisation, EBITDA-per-tonne or return targets for the project.
Conclusion
KSH International's financial highlights show EBITDA per tonne rising from Rs 32,326 in FY23 to Rs 97,600 in H1 FY27, alongside an increase in EBITDA from Rs 49.9 crore to Rs 164.1 crore over those reported periods. Revenue, PAT and return measures also increased over the series, while H1 FY27 working-capital balances were higher than at FY26 end.
The disclosed next milestone is the Supa expansion, expected to be completed in Q1 FY2029, with capacity set to rise 22% to 72,200 metric tonnes and planned investment of up to Rs 185 crore. Subsequent disclosures can show progress on that project and whether specialised-wire capacity, product mix and per-tonne EBITDA change as planned.