










Lumax Industries Limited Revenue Rises 33% in Q2 FY27
Key highlights
- Lumax Industries reported Q2 FY27 revenue of ₹1,341.84 crore, up 33.0% year-on-year.
- Consolidated Q2 FY27 profit after tax rose 45.9% year-on-year to ₹51.99 crore.
- Q2 FY27 EBITDA was ₹110 crore, while EBITDA margin declined to 8.2% from 9.0%.
- Lumax Industries raised FY27 revenue growth guidance from more than 20% to 25% or more.
powered by IRIS
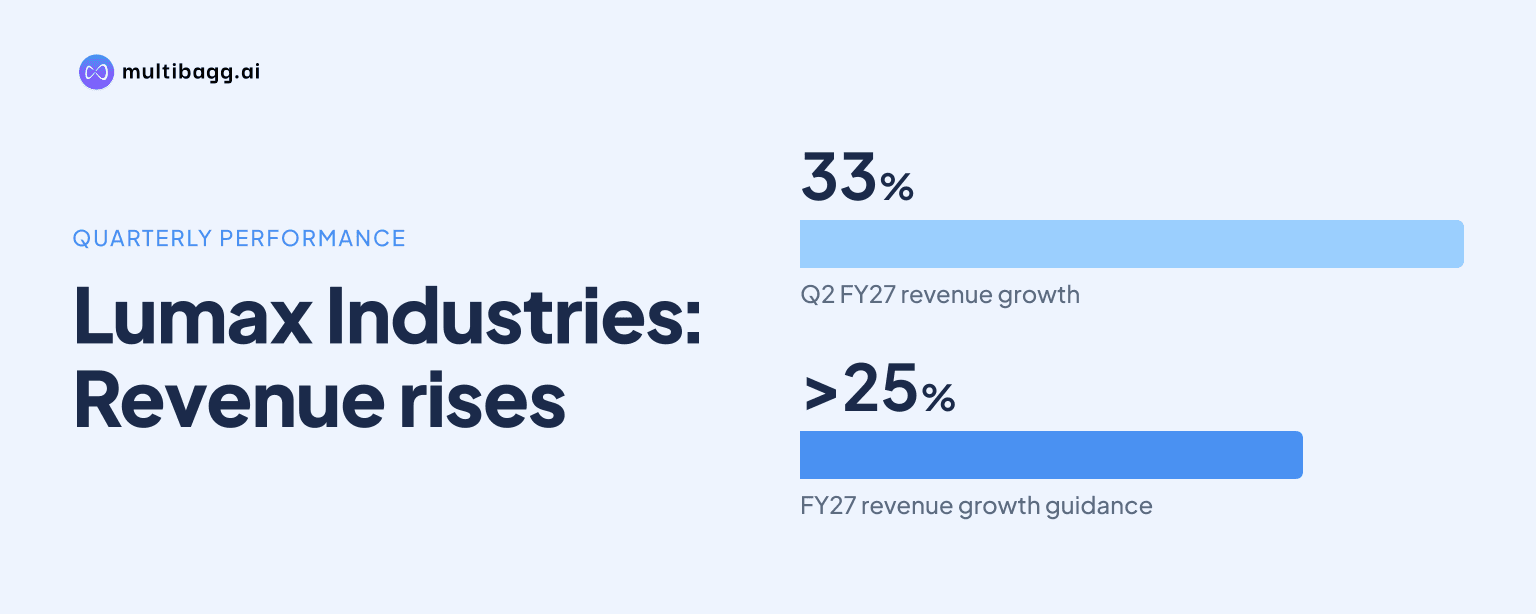
Lumax Industries Limited reported consolidated revenue of ₹1,342 crore in Q2 FY27, a 33% year-on-year increase, while EBITDA rose 21% to ₹110 crore and the EBITDA margin declined to 8.2% from 9.0% a year earlier. The result shows revenue growth ahead of the broader industry, but also highlights pressure from volatile input costs and supply-chain disruptions.
Know Lumax Industries inside out
Results, valuation, peers and who's buying, in one view.
What did Lumax Industries report for Q2 FY27?
Lumax Industries reported revenue from operations of ₹1,341.84 crore for the quarter ended September 30, 2026. This was 33.0% higher than ₹1,008.60 crore in Q2 FY26 and 9.7% above ₹1,223.23 crore in Q1 FY27. Total income stood at ₹1,342.54 crore, compared with ₹1,226.53 crore in the preceding quarter.
Manufacturing revenue was ₹1,300 crore in Q2 FY27, also up 33% year-on-year. For the first half of FY27, revenue reached ₹2,565 crore, representing 33% growth from ₹1,931 crore in H1 FY26. The reported quarterly revenue was described as a six-quarter high.
Consolidated profit after tax was ₹51.99 crore, up 45.9% from ₹35.64 crore in Q2 FY26. Profit after tax was marginally higher than ₹51.08 crore in Q1 FY27. Earnings per share rose to ₹55.62 from ₹38.13 in the year-earlier quarter and ₹54.64 in the preceding quarter.
Why did Lumax Industries' margin decline despite revenue growth?
Lumax Industries' consolidated EBITDA was ₹110 crore in Q2 FY27, up 21% year-on-year, but the EBITDA margin fell to 8.2% from 9.0% in Q2 FY26. The margin was also lower than the prior quarter, with reported commentary indicating a contraction of about 100 basis points sequentially.
Management attributed the pressure to geopolitical challenges, supply-chain disruptions and volatility in input costs. The company said it was holding discussions with customers for cost recovery while continuing to focus on operational efficiencies. The higher revenue base therefore did not translate into a proportional increase in operating profitability.
The quarterly profit growth also needs to be read alongside the difference between operating performance and other income sources. The available results commentary noted that part of the profit outperformance came from non-operating associate income, while core operating margins remained under pressure.
What are the key Q2 FY27 financial figures?
The following figures summarise Lumax Industries' reported consolidated performance for Q2 FY27 and the first half of the financial year.
Profit before tax was ₹53.12 crore in Q2 FY27, broadly stable compared with ₹52.71 crore in Q1 FY27. The sequential comparison indicates that revenue expanded more rapidly than profit during the quarter, consistent with the pressure on operating margin.
Got a follow-up? Ask IRIS
What is Lumax Industries' FY27 revenue outlook?
Lumax Industries revised its FY27 revenue growth guidance upward to 25% or more, from its earlier guidance of more than 20%. The revision follows 33% year-on-year revenue growth in both Q2 FY27 and H1 FY27.
The guidance signals management's expectation of continued sales momentum through the second half. However, the earnings call also identified ongoing uncertainty around input costs, supply chains and geopolitical conditions. The disclosed information does not provide a revised full-year EBITDA margin forecast.
The company made the audio recording of its October 27, 2026 earnings conference call available on its website. The call covered financial and operational performance for the quarter and half year ended September 30, 2026, in line with disclosure requirements under SEBI's Listing Obligations and Disclosure Requirements Regulations.
How do the results matter for investors and the auto-component industry?
For investors, the key contrast in the quarter is between strong revenue expansion and lower operating margin. Lumax Industries grew revenue by 33% year-on-year, exceeding the broader industry's growth according to the reported results, but EBITDA growth of 21% lagged revenue growth because of cost pressures.
The results also underline the importance of customer negotiations on input-cost recovery for auto-component manufacturers. Cost movements can affect profitability even when vehicle-linked demand and production volumes support revenue. Lumax Industries' ability to maintain efficiencies and recover eligible cost increases will remain relevant to its operating performance.
The company reported H1 FY27 profit after tax of ₹103 crore, up 43% from ₹72 crore a year earlier. This provides a stronger first-half earnings base, although the Q2 margin decline shows that revenue growth alone does not remove the impact of input-cost and supply-chain conditions.
Conclusion
Lumax Industries delivered 33% year-on-year revenue growth to ₹1,342 crore in Q2 FY27 and increased consolidated profit after tax by nearly 46% to ₹51.99 crore. The quarter was marked by higher manufacturing revenue and a stronger first-half sales run rate, while EBITDA margin fell to 8.2% as input-cost volatility and supply-chain issues weighed on operating profitability.
The next point to watch is whether Lumax Industries can deliver its revised FY27 revenue growth guidance of 25% or more while improving cost recovery discussions with customers. Investors will also track the company's subsequent quarterly margin trend, given the stated geopolitical and supply-chain pressures.