










Lumax Industries sees lighting share gains at five OEMs
Key highlights
- Lumax Industries expects Volkswagen India or Škoda India tail-lamp wallet share to rise from about 30% to about 70% in two to three years.
- Lumax Industries expects Maruti Suzuki combined headlamp and tail-lamp share to increase from 25-30% to 35-40%.
- About 60% of Lumax Industries' order book is expected to be delivered in FY 28, representing revenue close to Rs 1,500 crore.
- LED products account for 88% of Lumax Industries' current order book and 63% of H1 FY 27 revenue.
powered by IRIS
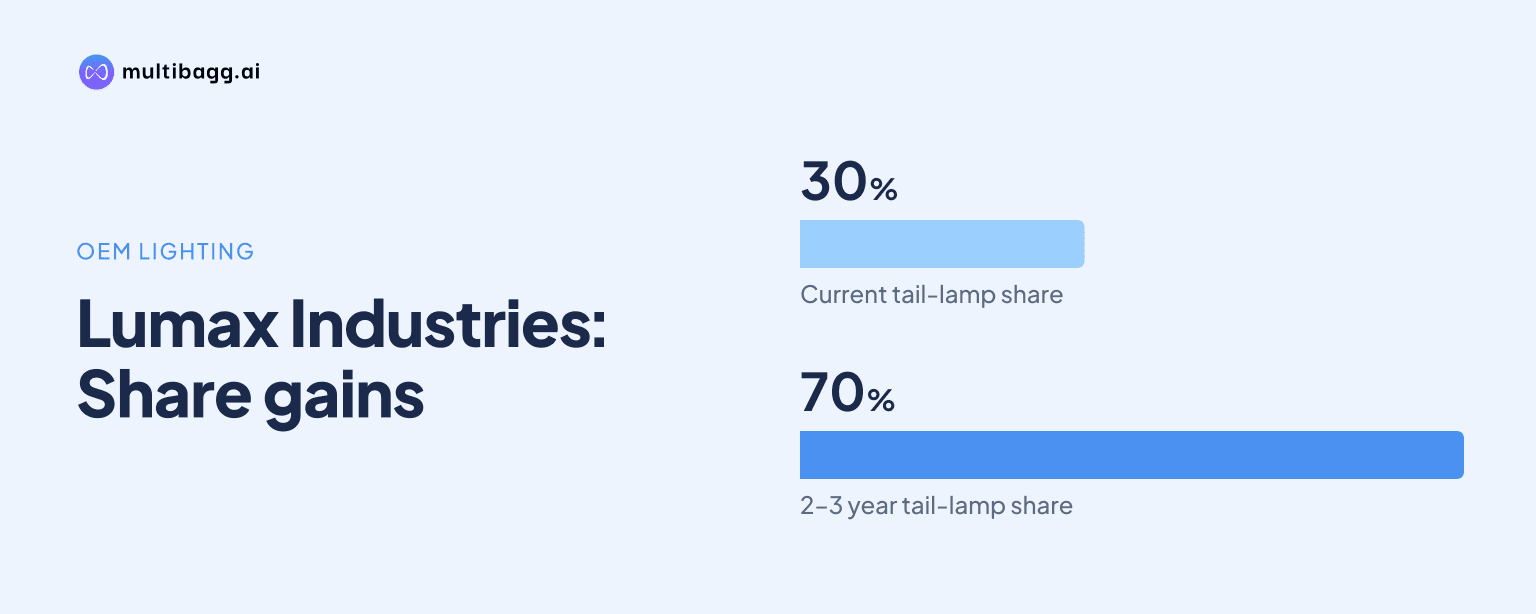
Lumax Industries Limited expects lighting wallet share to increase at five named original equipment manufacturers over the next two to three years, led by Volkswagen India or Škoda India tail-lamp share rising from about 30% to about 70%. Management said its order book also supports gains at Maruti Suzuki, Honda Motorcycle and Scooter India, Toyota Kirloskar and Suzuki 2-Wheelers India.
Know Lumax Industries inside out
Results, valuation, peers and who's buying, in one view.
Which OEMs are expected to increase Lumax Industries' wallet share?
Lumax Industries expects wallet-share gains at Maruti Suzuki, Honda Motorcycle and Scooter India, Toyota Kirloskar, Suzuki 2-Wheelers India, and Volkswagen India or Škoda India. Management identified these accounts when asked where its order book would increase share over the next two years, while saying it had a strong order book across nearly all OEMs and no wallet-share contraction at other customers.
The disclosures cover different products, so the percentages are not directly comparable across customers. Maruti Suzuki covers headlamps and tail lamps combined, Honda Motorcycle and Scooter India covers tail lamps, Toyota Kirloskar concerns new front-lighting supply, Suzuki 2-Wheelers India covers both main lamp categories, and Volkswagen India or Škoda India concerns tail lamps.
How will Maruti Suzuki and Honda Motorcycle and Scooter India change?
Lumax Industries expects its combined headlamp and tail-lamp wallet share at Maruti Suzuki to rise from 25-30% to 35-40% over the next two to three years. Management described Maruti Suzuki as the largest component of the order book, making this projected 10-15 percentage-point gain a central part of the company’s customer-share plan.
At Honda Motorcycle and Scooter India, Lumax Industries expects tail-lamp wallet share to rise from less than 20% to near 50% after a significant order win. Management said the tail-lamp gain would come from one unnamed competing supplier, while headlamp share at Honda Motorcycle and Scooter India would remain unchanged at 60-70%.
The order wins accompany revised FY 27 revenue guidance of more than 25%, compared with the earlier target of more than 20%. Management said H2 FY 27 growth would be lower than the roughly 35% reported in H1 because of a higher H2 FY 26 base, while about 60% of the order book is scheduled for delivery in FY 28, representing revenue close to Rs 1,500 crore.
What will change at Toyota Kirloskar, Suzuki 2-Wheelers India and Volkswagen India or Škoda India?
Lumax Industries is entering Toyota Kirloskar’s front-lighting business through a headlamp order for one forthcoming model. The company previously supplied Toyota Kirloskar only with rear lighting, and management expects the new order to establish 15-20% of the customer’s front-lighting share.
At Suzuki 2-Wheelers India, Lumax Industries expects combined headlamp and tail-lamp wallet share to increase from 15-20% to above 30% over the next two to three years. Management did not disclose separate headlamp and tail-lamp shares, but the stated range indicates the position would more than double from the lower end of the current range.
Volkswagen India or Škoda India has the largest disclosed end-point share. Lumax Industries expects its tail-lamp wallet share to rise from about 30% to about 70% over the next two to three years, an increase of about 40 percentage points. Management discussed Volkswagen India or Škoda India together and did not separately disclose orders, shares or timing for either brand.
Got a follow-up? Ask IRIS
What supports Lumax Industries' order-book execution?
Lumax Industries’ current order book is 88% light-emitting diode, or LED, based, supporting its focus on higher-technology lighting programs. LED lighting contributed 63% of revenue in H1 FY 27, compared with 61% in H1 FY 26, while management said domestic OEM wallet-share expansion remains its priority over exports.
Management aims to raise LED localization above 50% from 30-35% currently, beginning with the LED light source and subsequently intelligent modules such as light-control modules. It said it was too early to determine whether localization would be handled in-house, through another group company or through outsourcing, and clarified that automotive lighting is not covered by the Production Linked Incentive scheme.
Lumax Industries also expects advanced lighting to widen content per vehicle over time. Management said adaptive driving beam, or ADB, is currently limited to a couple of models but could gain traction over three to five years, principally in passenger vehicles; it is powertrain-agnostic. The company cited development work on projection technologies, organic light-emitting diodes, digital light processing, multi-pixel LEDs and laser lighting through its Czech and Taiwan engineering centres with Stanley support.
How does the share-gain plan fit Lumax Industries' financial targets?
Lumax Industries expects customer-share gains to support FY 27 revenue growth of more than 25% and has retained its target for a double-digit earnings before interest, tax, depreciation and amortisation, or EBITDA, margin. Management expects H2 FY 27 EBITDA margin of 10.5-11%, potentially lower in Q3 and higher in Q4, based on recovering most Q1 and Q2 raw-material price escalations in H2.
Management said the margin outlook could be reassessed if volatility linked to the West Asia crisis continued. Its FY 27 capital-expenditure guidance remains Rs 200 crore to Rs 250 crore, of which around Rs 80 crore had been spent in H1 for projects expected to progress in H2.
Net long-term debt stood at Rs 188 crore on September 30, 2026, down from Rs 291 crore on March 31, 2025. Net debt to EBITDA improved to 2.2 from 3.0 over the same dates, providing the balance-sheet context for capacity projects tied to the order-book ramp.
Conclusion
Lumax Industries’ order book indicates expansion through deeper share at established OEM accounts and entry into Toyota Kirloskar’s front-lighting category. The largest disclosed end-point is about 70% tail-lamp share at Volkswagen India or Škoda India, while Maruti Suzuki remains the largest part of the order book and Honda Motorcycle and Scooter India offers a tail-lamp share increase to near 50%.
The next measure will be delivery of the order book, around 60% of which management expects in FY 28. Management’s progress toward LED and light-control-module localization over the next three years, recovery of Q1 and Q2 raw-material escalations in H2 FY 27, and any review of margin guidance following West Asia-related volatility will also determine how the planned share gains translate into results.