










Lumax Industries raises FY27 growth outlook to above 25%
Key highlights
- Lumax Industries raised FY27 revenue-growth guidance to above 25% from above 20%.
- Q2 FY27 consolidated revenue increased 33% year on year to Rs 1,342 crore.
- Q2 FY27 EBITDA was Rs 110 crore, while EBITDA margin declined to 8.2% from 9.0%.
- Net long-term debt was Rs 188 crore on September 30, 2026, compared with Rs 291 crore on March 31, 2025.
powered by IRIS
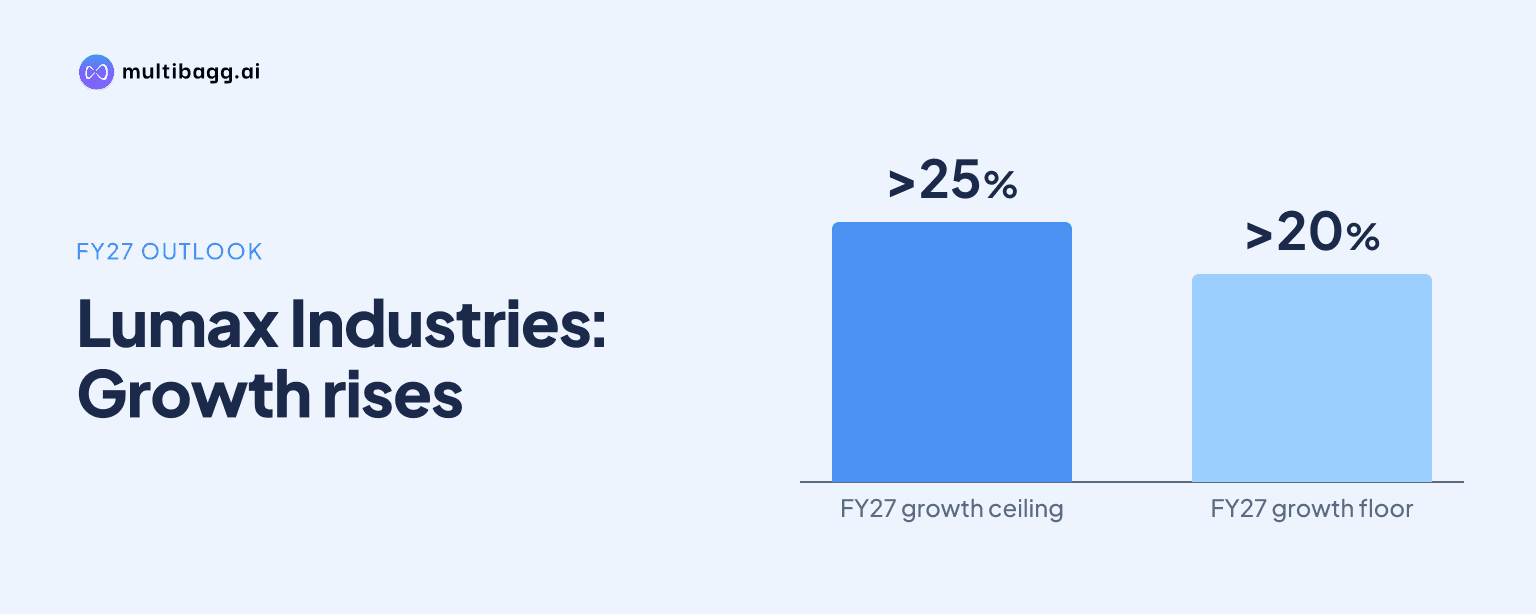
Lumax Industries Limited raised its FY27 revenue-growth outlook to above 25%, from above 20%, after consolidated revenue rose 33% year on year to Rs 1,342 crore in Q2 FY27. Lumax Industries retained its double-digit full-year EBITDA margin expectation, although higher material costs reduced quarterly margin to 8.2% from 9.0% a year earlier.
Know Lumax Industries inside out
Results, valuation, peers and who's buying, in one view.
Why did Lumax Industries raise its FY27 revenue-growth outlook?
Lumax Industries raised its FY27 revenue-growth outlook because revenue expanded 33% year on year in both Q2 FY27 and H1 FY27. Q2 consolidated revenue was Rs 1,342 crore, up 10% quarter on quarter, while H1 revenue reached Rs 2,565 crore. Management increased its full-year top-line guidance from above 20% to above 25%, without giving a rupee-denominated revenue target.
The company attributed the first-half growth to new programme launches, sustained sales with leading original equipment manufacturer, or OEM, customers, and faster scale-up with smaller customers. Manufacturing revenue rose 33% year on year to Rs 1,300 crore in Q2 FY27, accounting for most of the Rs 1,342 crore consolidated revenue reported in the quarter.
Management expects H2 FY27 revenue in absolute rupees to exceed the Rs 1,342 crore reported in Q2 FY27. However, Managing Director Anmol Jain said H2 growth will be lower than the roughly 35% rate reported in H1 FY27 because the company faces a higher comparison base in H2 FY26. The revised full-year forecast therefore does not indicate that the H1 growth rate will continue unchanged.
What is driving Lumax Industries' revenue growth?
Lumax Industries' growth is being led by new vehicle programmes, broader OEM business and a rising contribution from light-emitting diode, or LED, lighting. LED lighting represented 63% of H1 FY27 revenue, compared with 61% in H1 FY26, increasing its share by 200 basis points. Management also cited higher lighting content per vehicle as a long-term driver.
In passenger vehicles, Lumax Industries supplies tail lamps for the high and base versions of Tata Motors Aeris. It also supplies headlamps, fog lamps, cornering lamps and side repeater lamps for the Mahindra & Mahindra Thar Refresh. The company said it was gaining business with TVS, Suzuki 2-Wheelers, Yamaha Motors and Toyota during Q2 FY27.
The order book stood at Rs 2,580 crore, with passenger cars accounting for 63% and two- and three-wheelers accounting for 37%. Management said on one part of the call that LED lighting was about 80% of the order book, while later remarks described about 88% as LED-based; the transcript did not explain the difference. Electric-vehicle programmes accounted for about 11% of the order book.
Why did Lumax Industries' EBITDA margin decline in Q2 FY27?
Lumax Industries' EBITDA margin declined because material-cost escalation was reflected in costs before customer recoveries were fully received. Earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 21% year on year to Rs 110 crore in Q2 FY27, but the margin fell to 8.2% from 9.0% in Q2 FY26 as revenue increased faster than EBITDA.
Management identified elevated electronic-component prices and effects associated with the West Asia conflict as contributors to the pressure. It also listed crude-linked polymer prices, freight costs and rupee depreciation as items to monitor. The company estimated that higher material costs reduced H1 FY27 margin by approximately 100 to 120 basis points.
The recovery timing is central to the margin outcome. Management said some escalations effective in Q1 FY27 had not been fully recovered in Q2 FY27, while further Q2 escalation could reach the profit and loss account in Q3 FY27. Customer price recovery typically comes with a lag, so reported margin can decline before related selling-price adjustments are booked.
Profit after tax, including share of associates, rose 46% year on year to Rs 52 crore in Q2 FY27. Profit-after-tax margin increased 40 basis points to 3.9%, and the effective tax rate was 25.3%. These measures moved differently from EBITDA margin, which fell 80 basis points during the same quarter.
Got a follow-up? Ask IRIS
Can Lumax Industries achieve a double-digit FY27 EBITDA margin?
Lumax Industries said it continues to expect a double-digit EBITDA margin for FY27, based on recovering raw-material escalation from Q1 and Q2 and on management's expectation of no significant further price increases in H2 FY27. This is management guidance rather than a reported result, following the 8.2% EBITDA margin in Q2 FY27.
Management expects recovery of the remaining Q1 escalation and the Q2 cost impact to improve H2 FY27 margin. Anmol Jain said the company does not anticipate significant price increases beyond the current cost base established for H2 FY27. If costs rise beyond that base or recoveries are delayed, those developments would fall outside the assumptions management described on the call.
The company is also pursuing cost discipline and operational efficiency while discussing recoveries with customers. Its Q2 FY27 revenue of Rs 1,342 crore grew 33% year on year, compared with 21% growth in EBITDA to Rs 110 crore, showing the effect of input-cost timing on operating profitability during the quarter.
What should investors watch in H2 FY27?
Investors should watch customer cost recoveries, festive-season demand and the effect of higher comparison bases on H2 FY27 growth. Management said automotive-industry growth could moderate after the low base of the first half passes and goods and services tax rate cuts are fully reflected in demand. It described the festive season as an indicator of whether current demand momentum continues.
In Q2 FY27, Indian automobile production was 106 lakh units, up 19% year on year, according to Society of Indian Automobile Manufacturers data cited by management. Passenger-vehicle production rose 25% to about 17 lakh units, two-wheeler production increased 17% to around 81 lakh units, and commercial-vehicle production grew 34% to around 3.5 lakh units. These industry figures supported the company's operating environment during the quarter.
Lumax Industries retained FY27 capital-expenditure guidance of Rs 200 crore to Rs 250 crore and said projects were progressing as planned. Net long-term debt was Rs 188 crore on September 30, 2026, compared with Rs 291 crore on March 31, 2025. Net debt to EBITDA improved to 2.2 from 3.0 over the same dates.
Conclusion
Lumax Industries raised its FY27 revenue-growth outlook after delivering 33% growth in both Q2 and H1 FY27, supported by new programmes, broader OEM engagement and a 63% LED share of H1 revenue. The key offset was margin pressure: EBITDA reached Rs 110 crore in Q2 FY27, but its margin declined to 8.2% as material-cost increases preceded customer recovery.
The next disclosures to watch are progress in recovering Q1 and Q2 cost escalation, which management expects to lift H2 FY27 margin toward a double-digit full-year outcome, and demand after the festive season. Investors can also track execution of the Rs 200 crore to Rs 250 crore FY27 capital-expenditure plan and conversion of the Rs 2,580 crore order book.