










Manaksia Coated Metals targets 35%-55% FY27 revenue growth
Key highlights
- Manaksia Coated Metals targets FY27 revenue growth of 35%-55% over FY26.
- The second colour-coating line adds 150,000 tonnes a year, lifting Pre-Painted Steel capacity to 236,000 tonnes.
- H1 FY27 total income was Rs 584.62 crore, up 22.4% year on year.
- The order book was Rs 525 crore, including Rs 420 crore of export orders for execution over five months.
powered by IRIS
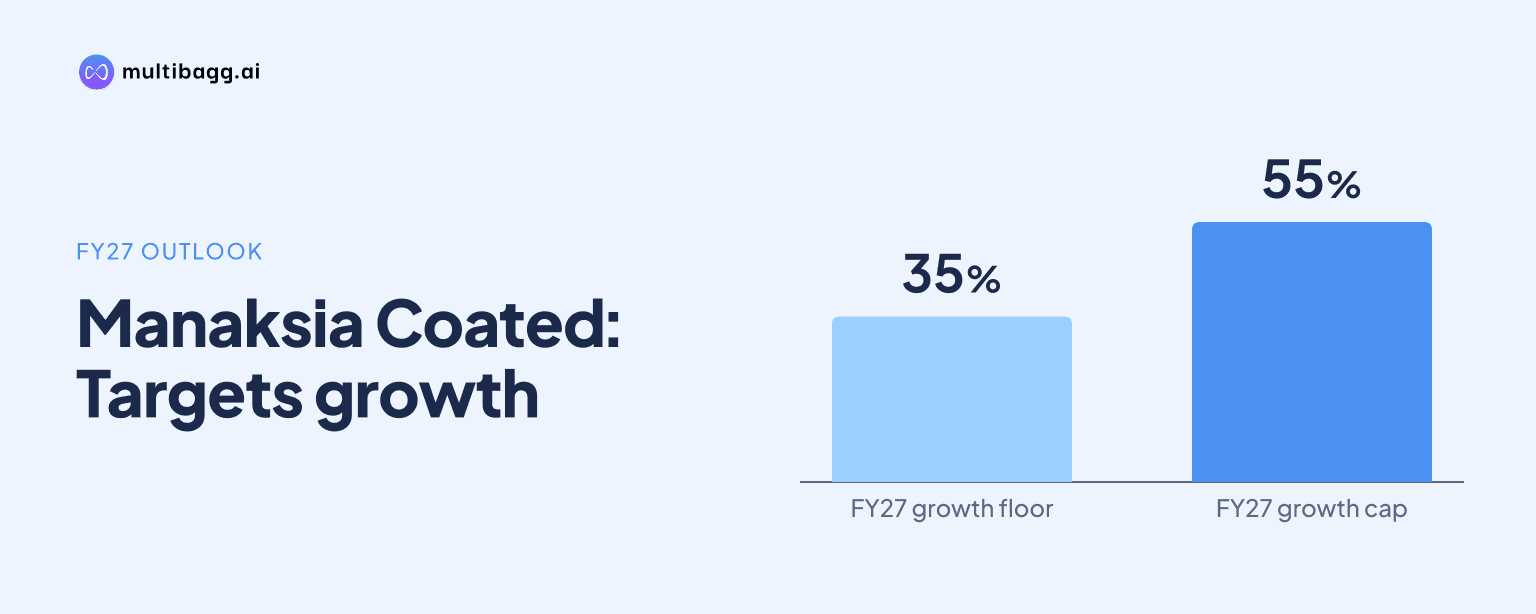
Manaksia Coated Metals & Industries Limited is targeting FY27 revenue growth of 35%-55% over FY26, supported by a 150,000-tonne-a-year second colour-coating line targeted for commissioning in Q3 FY27; management expects a partial Q3 contribution and a full Q4 contribution from the asset.
Know Manaksia Coated Metals & Industries inside out
Results, valuation, peers and who's buying, in one view.
What is Manaksia Coated Metals' FY27 revenue-growth guidance?
Manaksia Coated Metals is targeting FY27 revenue growth of 35%-55% over FY26, according to Whole-Time Director Karan Agrawal. He said the company had completed about 50% of FY27, with H1 total income of Rs 584.62 crore, and that the new line would contribute during part of Q3 and all of Q4 after it comes on stream.
The guidance is a range rather than a revenue figure, and management did not provide a numerical FY28 revenue forecast. For FY28, Agrawal instead indicated that production and sales volumes could reach about 175,000-200,000 tonnes, compared with just over 100,000 tonnes in FY26, assuming a full year from the new capacities. The FY27 range is therefore tied to commissioning and ramp-up rather than a disclosed sales-price or utilisation assumption.
The FY27 target follows a higher first-half base. Q2 total income was Rs 321.55 crore, up 22.2% sequentially and 43.8% year on year, while H1 total income grew 22.4% year on year to Rs 584.62 crore. Q2 realisation rose to Rs 95,291 per tonne, up 7.6% from Q1 and 8.3% from a year earlier, which management attributed to product premiumisation, mix and pricing discipline.
How much capacity will the second colour-coating line add?
The second colour-coating line will add 150,000 tonnes a year of capacity, taking Manaksia Coated Metals' Pre-Painted Steel capacity to 236,000 tonnes a year from 86,000 tonnes a year. Management described the expansion as an approximately 174% increase and said the project was in trial and pre-commissioning stages, with commissioning targeted within Q3 FY27.
The new capacity is directed at Pre-Painted Steel, which accounted for 69.19% of Q2 FY27 sales, making it the company's largest reported product category. Alu-Zinc Steel represented another 26.48% of sales in the quarter. Management said the additional colour-coating capacity should allow it to serve larger customer requirements and raise the contribution of its highest value-added product.
A 7-megawatt captive solar power plant is also targeted for commissioning in Q3 FY27, subject to readiness and grid connectivity. Management expects the facility to offset about 50%-55% of grid-power consumption at Kutch. The solar project does not add steel capacity, but management expects it to improve the energy-cost structure and reduce reliance on grid electricity as output rises.
Got a follow-up? Ask IRIS
What evidence supports the planned production ramp-up?
Manaksia Coated Metals reported an order book of Rs 525 crore, including Rs 420 crore of export orders scheduled for execution over the next five months. Management cited that backlog as demand visibility while declining to disclose its detailed sales strategy for the expanded line, including the geographic split or anchor customers.
Exports supplied 71.25% of Q2 FY27 revenue, or Rs 227.07 crore. In H1 FY27, export volumes reached 40,561 tonnes and generated Rs 397.28 crore of revenue, up 20.7% year on year. Domestic revenue for the half year rose 30.3% year on year to Rs 183.55 crore, giving the company growth in both reported sales channels.
Product and operating metrics also improved in Q2. Earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 26.9% sequentially to Rs 36.91 crore, and EBITDA margin increased to 11.48% from 11.06% in Q1. EBITDA per tonne increased to Rs 11,536 from Rs 10,411 in Q1, with management citing upgraded Alu-Zinc technology, higher realisations and greater value-added-product acceptance.
The export mix remains centred on Pre-Painted Steel. Management said quarterly Pre-Painted Steel exports were just over 20,000 tonnes, compared with about 2,000 tonnes of Alu-Zinc exports, or roughly a 90%-10% volume split. Europe is the dominant export market, while the company is also entering South America, Central America and the Caribbean to diversify its regional sales mix.
Can the new line deliver Manaksia Coated Metals' FY29 ambition?
Management's broader ambition is to triple output, revenue and EBITDA by FY29, and it considers the second colour-coating line an important part of that plan. Agrawal said the company is also pursuing backward integration and a second Alu-Zinc facility in Kutch, which together could provide potential capacity of 360,000 tonnes a year if the projects are executed on time.
The disclosed FY28 volume range of 175,000-200,000 tonnes provides an intermediate operational marker, but it is not revenue guidance. It assumes a full year of the second colour-coating line and the Alu-Zinc line. Management did not disclose expected utilisation rates, pricing, capital expenditure, the commissioning date for a second Alu-Zinc facility, or the revenue contribution expected from each project.
Export conditions remain relevant because exports made up Rs 397.28 crore of H1 revenue. In discussing European import quotas, management said the quota changes took effect in July and argued that India had retained an advantage relative to Turkey, Vietnam, Korea and Taiwan, while also gaining access to an additional free-trade-agreement quota. This was management's assessment, not a quantified company forecast, and it said the Rs 525 crore order book showed continuing export momentum.
Manaksia Coated Metals is also scheduling systems investments around the capacity expansion. Salesforce customer-relationship-management implementation is targeted for Q3 FY27, while a Manufacturing Execution System, or MES, at Kutch is targeted to go live in Q1 FY28. Management said MES is intended to support production planning, process control, quality management and dispatch coordination as volumes scale.
Conclusion
The FY27 growth range places a measurable near-term target alongside Manaksia Coated Metals' FY29 threefold-growth ambition. The case presented by management combines a 150,000-tonne increase in Pre-Painted Steel capacity, H1 total income of Rs 584.62 crore, and an order book of Rs 525 crore, of which Rs 420 crore is export business scheduled over five months.
The next event to watch is Q3 FY27 commissioning of both the second colour-coating line and the 7-megawatt solar plant, including whether grid connectivity is completed for the latter. Investors can then assess Q4's full-quarter line contribution, progress toward the 175,000-200,000-tonne FY28 volume indication, and the Q1 FY28 MES go-live target.