










Mitsu Chem Plast Ltd Posts 365% H1 FY27 PAT Growth on Margins
Key highlights
- Mitsu Chem Plast reported H1 FY27 revenue from operations of Rs 190.95 crore, up 7.46% year on year.
- Mitsu Chem Plast' H1 FY27 EBITDA rose 151.40% to Rs 27.83 crore, with a reported 14.34% margin.
- Mitsu Chem Plast reported H1 FY27 profit after tax of Rs 14.84 crore, up 364.66% year on year.
- Q2 FY27 profit before tax was Rs 6.10 crore, up 224.5% year on year.
powered by IRIS
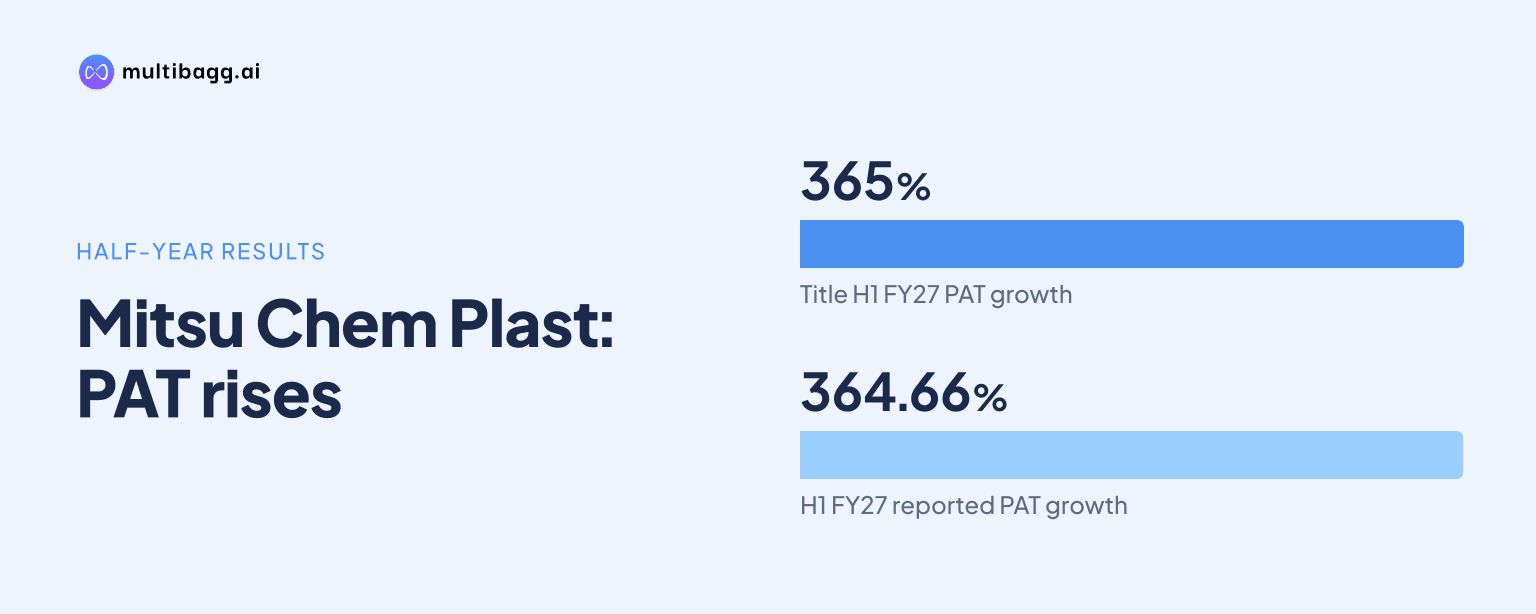
Mitsu Chem Plast Ltd reported H1 FY27 profit after tax of Rs 14.84 crore, a 364.66% year-on-year increase, while revenue from operations rose 7.46% to Rs 190.95 crore for the half year ended September 30, 2026. The earnings update showed substantially stronger profitability despite more modest revenue growth.
Know Mitsu Chem Plast inside out
Results, valuation, peers and who's buying, in one view.
What did Mitsu Chem Plast report for Q2 and H1 FY27?
Mitsu Chem Plast reported Q2 FY27 revenue from operations of Rs 95.81 crore, compared with Rs 92.42 crore in Q2 FY26, representing growth of 3.67% year on year. Quarterly EBITDA stood at Rs 10.89 crore, increasing by Rs 1.02 crore from the prior-year quarter. The company reported an EBITDA margin of 12.47% for the quarter.
Profit before tax for Q2 FY27 was Rs 6.10 crore, up 224.5% year on year, with a reported margin of 6.37%. For the first half, revenue from operations reached Rs 190.95 crore, up 7.46% year on year. H1 EBITDA increased 151.40% to Rs 27.83 crore, while the reported EBITDA margin was 14.34%.
The most notable movement was in half-year profitability. H1 profit after tax rose to Rs 14.84 crore, a 364.66% increase from the comparable period of FY26. The company reported a PAT margin of 7.77%, indicating that profit growth materially outpaced the increase in sales during the six-month period.
What drove the improvement in profitability?
Mitsu Chem Plast linked the H1 FY27 performance to strong demand for hospital furniture and operational efficiency, according to the available results summary and investor presentation details. These factors were cited alongside the higher EBITDA and PAT reported for the half year.
The available information does not provide a detailed line-by-line breakdown of changes in product pricing, volumes, employee costs, finance costs, depreciation, or taxes. Therefore, the reported figures establish a sharp improvement in margins and earnings, but do not independently quantify the contribution from each cost or product category.
The company also described the outlook for India’s plastic packaging industry as positive, citing demand from FMCG, healthcare, automotive and infrastructure. Rising consumption and demand from FMCG, pharmaceutical and e-commerce segments were identified as broader industry demand factors in the results communication.
Got a follow-up? Ask IRIS
How did the Q2 FY27 earnings call address raw-material risk?
Mitsu Chem Plast held its Q2 and H1 FY27 earnings call on November 3, 2026, at 11:00 AM IST, after the quarter ended September 30, 2026. The company subsequently disclosed the audio recording of the call through its corporate announcement, with the BSE scrip code 540078.
During the call, Managing Director and CFO Manish Dedhia addressed a question on polymer hedging. He stated that polymers in India are not hedged and that the company buys about 90% to 95% of its raw material domestically. He said there was consequently no hedging-related impact for the company.
This disclosure is relevant because polymers are a core input for plastic-product manufacturers. The company’s statement clarifies its procurement approach, but the available call material does not provide detailed information on raw-material price movements during Q2 or the terms of supplier arrangements.
Why do the FY27 results matter for investors and the packaging industry?
The H1 figures show a distinction between revenue growth and profit growth. Revenue increased 7.46%, while EBITDA and PAT increased 151.40% and 364.66%, respectively. For investors, this makes the reported margin performance central to evaluating the period rather than sales growth alone.
The Q2 results also indicate that improved half-year profitability was not solely a matter of higher turnover. Quarterly revenue grew 3.67%, whereas Q2 profit before tax rose 224.5%. The reported Q2 EBITDA margin of 12.47% and H1 EBITDA margin of 14.34% provide the company’s stated measures of operating performance.
For the industry, the company’s comments point to continuing demand across end-use sectors including healthcare, FMCG, automotive and infrastructure. However, the available disclosures do not provide a volume outlook, capacity-expansion target, order-book figure, or earnings guidance. As a result, the reported financial performance is clearer than the forward visibility provided in the update.
Conclusion
Mitsu Chem Plast delivered a strong improvement in H1 FY27 profitability, with PAT reaching Rs 14.84 crore and EBITDA rising to Rs 27.83 crore, while revenue from operations rose to Rs 190.95 crore. The earnings call also clarified that the company sources most raw material domestically and does not face a hedging-related impact on polymer purchases.
Investors will watch whether the company can sustain its reported margins as it serves demand from hospital furniture and end-markets such as FMCG, healthcare, automotive and infrastructure. The disclosed materials do not include formal guidance, so future quarterly results and management commentary will be important for assessing the durability of the H1 performance.