










Mitsu Chem Plast H1 EBITDA Margin More Than Doubles to 14%
Key highlights
- Mitsu Chem Plast’s H1FY27 EBITDA margin rose to 14% from 6% in H1FY26, an expansion of 800 basis points.
- H1FY27 revenue increased 7% to Rs 190.95 crore, while EBITDA rose 151% to Rs 27.38 crore.
- Hospital Furniture Parts revenue grew 30% to Rs 29.85 crore, increasing its revenue contribution to 16% from 13%.
- H1FY27 profit after tax surged 365% to Rs 14.84 crore, lifting the PAT margin to 8% from 2%.
powered by IRIS
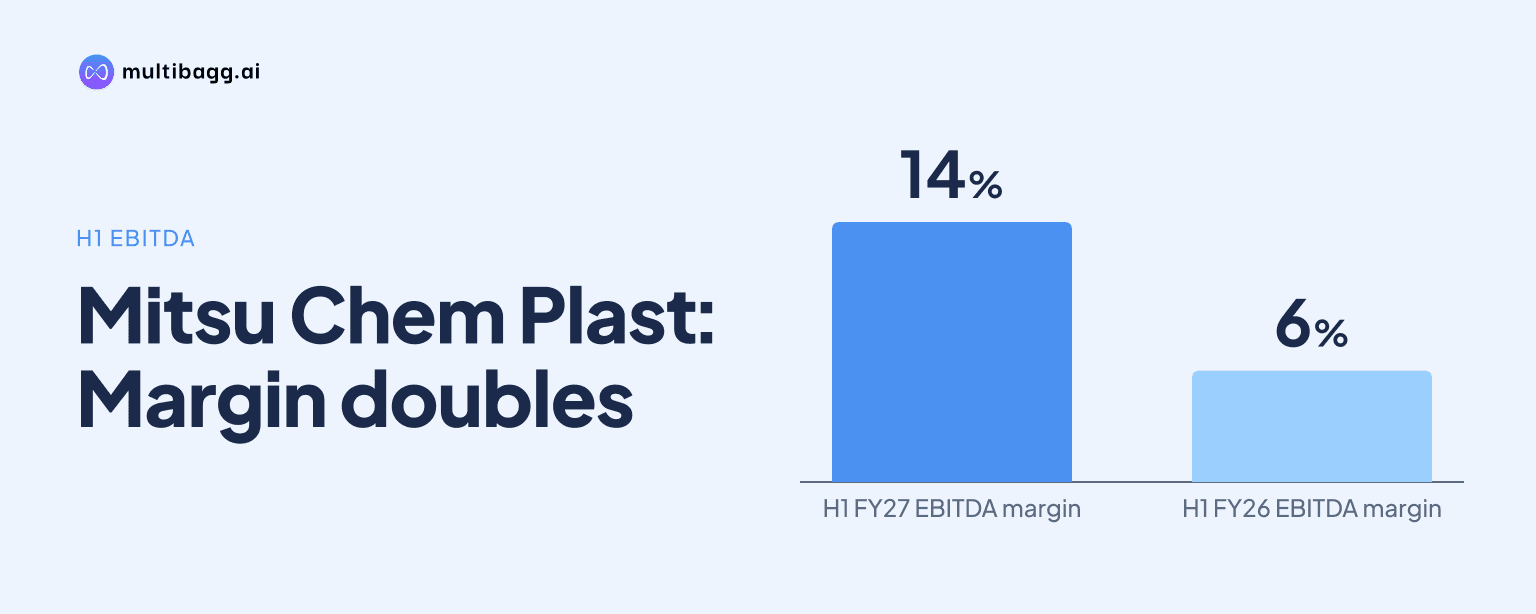
Mitsu Chem Plast reported a 14% earnings before interest, tax, depreciation and amortisation (EBITDA) margin in the first half of fiscal year 2027 (H1FY27), up from 6% a year earlier. EBITDA rose 151% to Rs 27.38 crore while revenue increased 7% to Rs 190.95 crore, supported by a 30% rise in Hospital Furniture Parts revenue.
Know Mitsu Chem Plast inside out
Results, valuation, peers and who's buying, in one view.
Why did Mitsu’s H1FY27 EBITDA margin rise to 14%?
Mitsu’s H1FY27 EBITDA margin rose by about 800 basis points to 14%, from 6% in H1FY26, as EBITDA increased to Rs 27.38 crore from Rs 10.89 crore. Revenue from operations rose 7% to Rs 190.95 crore from Rs 177.70 crore, meaning operating profit increased much faster than sales during the six-month period.
Management attributed the margin expansion to cost optimisation, operational efficiencies and a higher contribution from high-margin products. Raw-material costs increased to Rs 117.04 crore from Rs 112.02 crore, while employee expenses declined to Rs 12.96 crore from Rs 13.43 crore and other expenses fell to Rs 33.57 crore from Rs 41.36 crore.
How did Mitsu’s product revenue mix change in H1FY27?
Mitsu’s Hospital Furniture Parts revenue rose 30% year on year to Rs 29.85 crore in H1FY27 from Rs 23.03 crore in H1FY26. Its contribution to revenue increased to 16% from 13%, making the healthcare-linked vertical a larger part of Mitsu’s Rs 190.95 crore revenue base.
Industrial Packaging remained Mitsu’s largest vertical, generating Rs 154.75 crore in H1FY27 compared with Rs 149.10 crore a year earlier. Its 4% growth was below the 30% increase in Hospital Furniture Parts, while Infrastructural Furniture & Others grew 14% to Rs 6.35 crore from Rs 5.57 crore.
Mitsu said it is accelerating its portfolio transition beyond Industrial Packaging, with greater emphasis on higher-growth and higher-value verticals such as Hospital Furniture Parts. The company also identified healthcare and intermediate bulk container (IBC) opportunities as areas intended to create additional avenues for scale.
Got a follow-up? Ask IRIS
What happened to Mitsu’s profit after tax in H1FY27?
Mitsu’s profit after tax (PAT) increased 365% year on year to Rs 14.84 crore in H1FY27 from Rs 3.20 crore in H1FY26. PAT margin increased to 8% from 2%, following the rise in operating profit despite tax expense increasing to Rs 5.29 crore from Rs 1.14 crore.
Profit before tax rose 364% to Rs 20.13 crore from Rs 4.34 crore. Earnings before interest and tax increased 220% to Rs 23.10 crore, while depreciation rose to Rs 4.28 crore from Rs 3.67 crore and finance cost increased to Rs 3.47 crore from Rs 3.15 crore.
The half-year result included Rs 0.50 crore of other income, compared with Rs 0.26 crore in H1FY26, with no exceptional item in either period. The larger increase in PAT than revenue reflected the reported expansion in EBITDA and earnings before interest and tax margins rather than a comparable rise in sales.
Did Mitsu sustain its H1FY27 profitability improvement in Q2FY27?
Mitsu remained more profitable in Q2FY27 than a year earlier, although EBITDA was lower than in Q1FY27. Q2FY27 EBITDA was Rs 11.89 crore, up 102% from Rs 5.88 crore in Q2FY26, while EBITDA margin was 12% versus 6% a year earlier and 16% in Q1FY27.
Q2FY27 revenue from operations increased 4% year on year to Rs 95.81 crore from Rs 92.42 crore and was 1% higher than Rs 95.15 crore in Q1FY27. PAT was Rs 6.10 crore, up 224% from Rs 1.88 crore a year earlier but 30% below Rs 8.74 crore in Q1FY27; PAT margin was 6%, compared with 9% in the preceding quarter.
Hospital Furniture Parts revenue was Rs 15.59 crore in Q2FY27, up 34% year on year and 9% sequentially. Industrial Packaging revenue was Rs 78.45 crore, broadly unchanged from Rs 78.54 crore a year earlier, while Infrastructural Furniture & Others declined 61% sequentially to Rs 1.78 crore from Rs 4.58 crore in Q1FY27.
Conclusion
Mitsu’s H1FY27 results showed a marked increase in profitability alongside moderate revenue growth. Revenue increased 7% to Rs 190.95 crore, while EBITDA rose 151% to Rs 27.38 crore and PAT increased 365% to Rs 14.84 crore; Hospital Furniture Parts also expanded its revenue contribution from 13% to 16%.
The next disclosed milestone is commissioning of Mitsu’s IBC facility, which management said was on track for Q3FY27. Management expects growth momentum to continue through FY27, with the facility intended to support the company’s next phase of growth.