










MobiKwik receives RBI NBFC registration, targets Rs 5,000 crore
Key highlights
- MobiKwik announced RBI NBFC registration for its wholly owned subsidiary on 6 November 2026.
- MobiKwik aims to disburse Rs 5,000 crore of loans over the next three to four years.
- MobiKwik expects to launch asset-light co-lending operations with banks and NBFCs within three to six months.
- MobiKwik reported Rs 1,083 crore of Q2 FY27 disbursals through 11 partners, up 34% year on year.
powered by IRIS
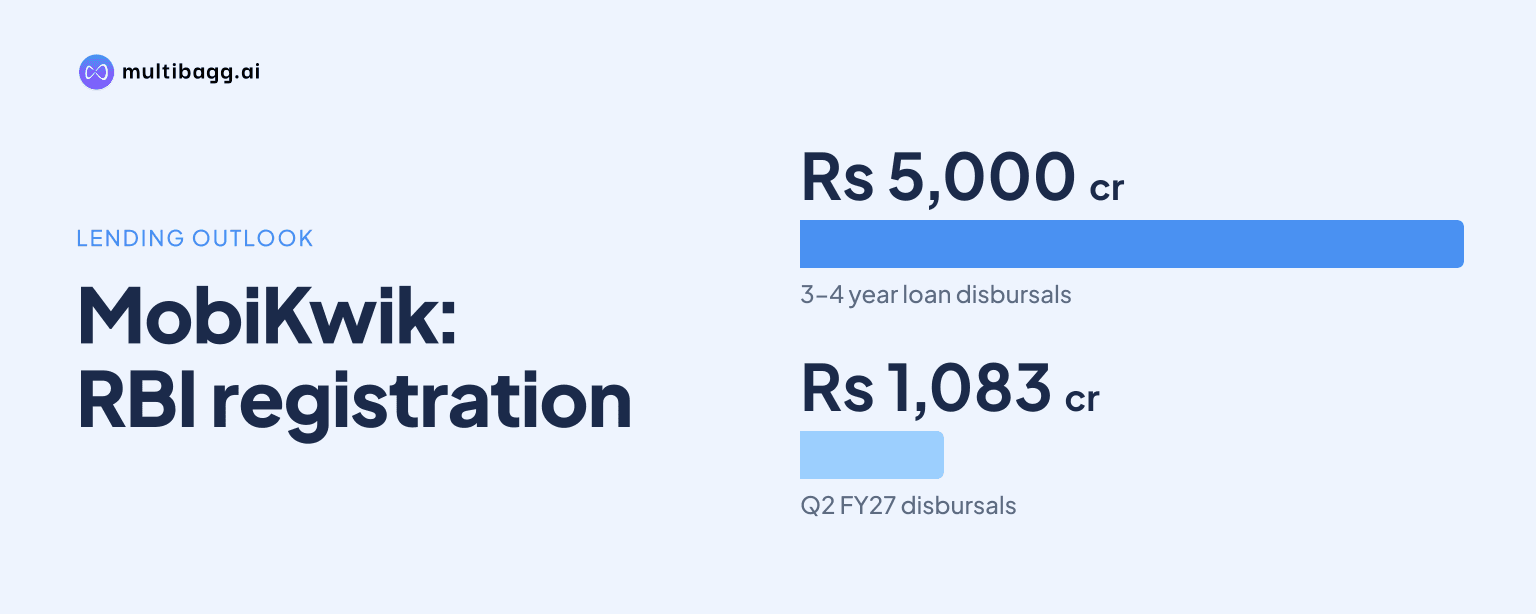
One MobiKwik Systems Limited announced on 6 November 2026 that its wholly owned subsidiary received a Reserve Bank of India certificate to operate as a Non-Banking Financial Company, allowing direct credit origination. MobiKwik aims to disburse Rs 5,000 crore of loans through the NBFC over the next three to four years.
Know One Mobikwik Systems inside out
Results, valuation, peers and who's buying, in one view.
What RBI registration did MobiKwik receive?
MobiKwik received a Certificate of Registration from the Reserve Bank of India (RBI) for its wholly owned subsidiary, MobiKwik Financial Services Private Limited (MFSPL), to operate as a Non-Banking Financial Company (NBFC). The company announced the certificate on 6 November 2026, after the RBI granted MFSPL in-principle approval in April 2026.
The certificate allows MFSPL to commence NBFC operations, while MobiKwik continues its existing Lending Service Provider (LSP) business. As an LSP, MobiKwik distributes loans through lender partnerships; the NBFC registration adds the ability to originate credit directly through its subsidiary.
MobiKwik said the new structure is intended to complement its lender relationships rather than replace them. The company said direct origination can provide greater flexibility in product development, faster go-to-market execution and opportunities to improve lending economics, but it did not disclose an expected margin, yield or capital allocation for the NBFC.
How will MobiKwik start NBFC lending operations?
MobiKwik expects MFSPL to begin business operations within three to six months through an asset-light co-lending model with banks and other NBFCs. The company did not name the proposed co-lending partners or state the date on which the first products will be available.
MFSPL plans to develop secured and unsecured credit products for consumers and micro, small and medium enterprises (MSMEs) across India. Its initial operating model combines co-lending partnerships with MobiKwik's stated technology infrastructure, data and analytics capabilities, risk assessment models and collections expertise.
The three-to-six-month launch plan means the Rs 5,000 crore objective is a forward target rather than a reported NBFC disbursal figure. MobiKwik said underwriting discipline and risk management will remain central as it develops the consumer and MSME loan offering.
What loan disbursal target has MobiKwik set?
MobiKwik aims to disburse Rs 5,000 crore of loans over the next three to four years through its NBFC strategy. The target covers a multi-year period after the planned co-lending launch and is not an annual target disclosed for financial year 2027.
The company reported Rs 1,083 crore of lending disbursal through its partner network in Q2 FY27, providing a comparison with the longer-term NBFC target. The two measures differ in scope and period: the Q2 FY27 figure reflects lending through 11 partners, while the Rs 5,000 crore aim relates to the planned NBFC business over three to four years.
MobiKwik has not disclosed yearly milestones, a quarterly run-rate target or a product-level split for the Rs 5,000 crore goal. It also has not stated what proportion of the planned disbursals would be secured credit, unsecured credit, consumer lending or MSME lending.
Got a follow-up? Ask IRIS
How did MobiKwik's partner-led lending business perform in Q2 FY27?
MobiKwik reported that lending disbursal through 11 lending partners rose 34% year on year to Rs 1,083 crore in Q2 FY27. The disclosed change shows higher disbursal through the partner-led model than in Q2 FY26, before MFSPL begins its planned operations.
MobiKwik also reported 2.2 times year-on-year growth in gross profit from financial services in Q2 FY27. The company attributed the gross-profit increase to improved credit quality and portfolio recoveries, although it did not disclose the gross-profit amount, delinquency data, recovery rate or loan-book balance.
The NBFC will therefore be added to a lending operation that already uses 11 lending partners. MobiKwik said it intends to retain those established relationships while participating more directly in the lending value chain through credit origination by MFSPL.
What customer network will MobiKwik use for lending?
MobiKwik said it will use its payment network of 196 million registered users and 5 million registered merchants as it develops NBFC credit products. Management said the ability to provide loans through the NBFC will benefit this network, but did not give a customer conversion target or planned loan-penetration rate.
The 196 million users access products including MobiKwik Wallet, Pocket UPI, Unified Payments Interface payments and bill payments. The 5 million merchants use merchant-acquiring products including electronic data capture terminals, Soundbox devices, QR codes and online checkout through the Zaakpay payment gateway.
MobiKwik identified data, analytics, risk models and collections as mechanisms for supporting the planned lending operation. The announcement did not disclose loan pricing, ticket sizes, borrower eligibility rules, geographic rollout stages, funding arrangements or the initial mix of secured and unsecured products.
Conclusion
MobiKwik's RBI certificate gives its wholly owned MFSPL subsidiary the ability to operate as an NBFC and originate credit directly, alongside the company's existing partner-led LSP business. The planned structure builds on Q2 FY27 partner-network disbursals of Rs 1,083 crore, which were 34% higher year on year, while setting a Rs 5,000 crore disbursal aim over three to four years.
The next disclosed event is MFSPL's planned asset-light co-lending launch within three to six months with banks and NBFCs. Progress will depend on the partnership model, the first consumer and MSME products, and any later disclosure of funding, underwriting outcomes and disbursals under the NBFC structure.