










Mrs Bectors says inflation will pressure margins near term
Key highlights
- Mrs Bectors reported record Q2 FY2027 revenue of Rs 630.5 crore, up 14.3% year on year.
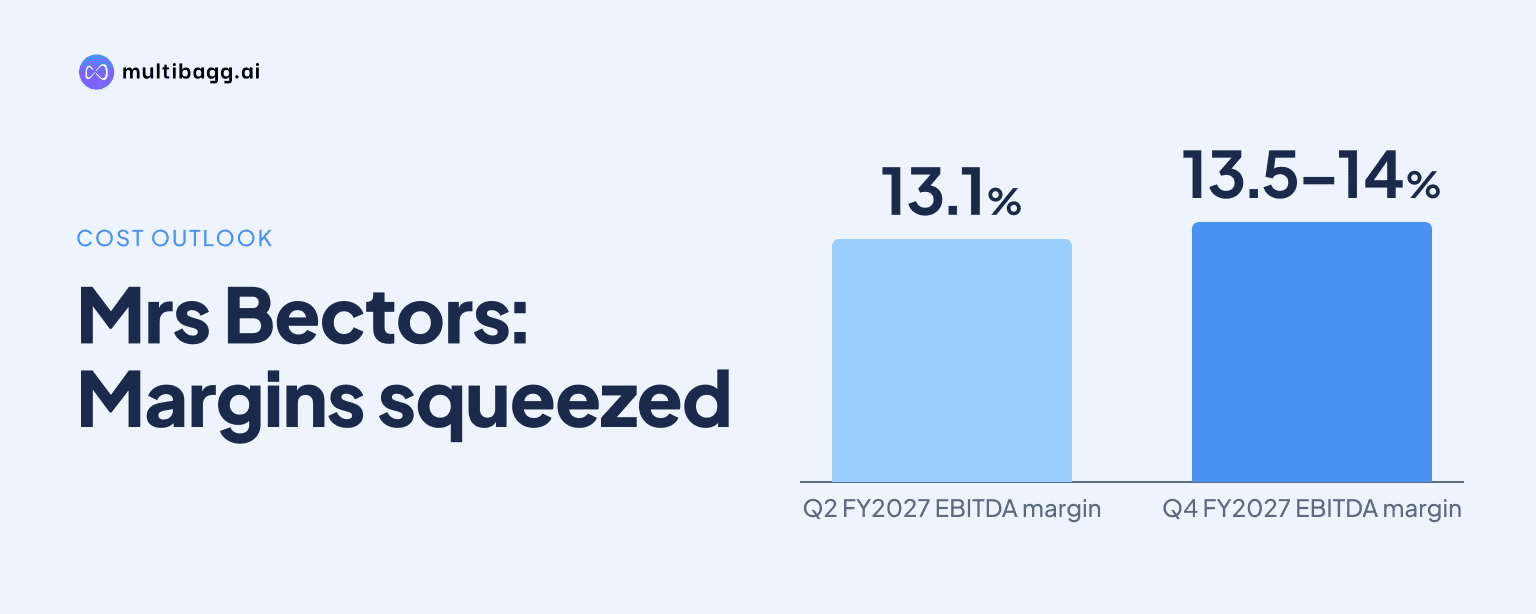
- Q2 FY2027 EBITDA was Rs 82.5 crore and EBITDA margin was 13.1%, up 50 basis points year on year.
- Mrs Bectors said gross margin fell from the first quarter as edible oils, sugar, cereals, freight and packaging costs increased.
- Management aims to maintain Q3 FY2027 EBITDA margin and improve toward 13.5% to 14% in Q4 FY2027.
powered by IRIS
Mrs. Bectors Food Specialities Limited reported record revenue of Rs 630.5 crore in the second quarter (Q2) of financial year 2027 (FY2027), up 14.3% year on year, but said inflation in edible oils, sugar, cereals, freight and packaging pushed gross margin below the first quarter and will pressure near-term margins.
Know Mrs Bectors Food Specialities inside out
Results, valuation, peers and who's buying, in one view.
What did Mrs Bectors report in Q2 FY2027?
Mrs Bectors reported its highest-ever quarterly revenue of Rs 630.5 crore in Q2 FY2027, with earnings before interest, tax, depreciation and amortisation (EBITDA) of Rs 82.5 crore and profit after tax (PAT) of Rs 45.7 crore. Revenue rose 14.3% from Rs 551.4 crore in Q2 FY2026 and increased 14.9% from the preceding quarter, according to management on its November 6, 2026 earnings call.
The Q2 FY2027 EBITDA margin was 13.1%, 50 basis points above Q2 FY2026, while PAT margin increased to 7.3% from 6.6%. EBITDA grew 19.1% year on year and PAT increased 25.3%, meaning both profit measures grew faster than the 14.3% revenue increase despite what management described as a steeper cost environment than in the first quarter.
For the first half (H1) of FY2027, Mrs Bectors recorded revenue of Rs 1,179.3 crore, up 15.1% from Rs 1,024.4 crore in H1 FY2026. H1 EBITDA increased 21.2% to Rs 154.6 crore and PAT rose 25.4% to Rs 84.5 crore; EBITDA margin was 13.1%, up 70 basis points, while PAT margin rose to 7.2% from 6.6%.
Why are Mrs Bectors margins under pressure despite higher profit?
Mrs Bectors said gross margin declined from the first quarter in Q2 FY2027 because price increases and savings under Project IMPACT offset most, but not all, of the increase in costs. Management specifically cited higher prices for edible oils, sugar and cereals, as well as crude-oil-driven increases in freight and packaging expenses.
The consumer backdrop also became less favourable during the quarter. Management said headline consumer inflation increased from about 4.4% in June 2026 to 5.5% in September 2026, the highest level in nearly two years, driven by edible oils, sugar and cereals. It also said a below-normal monsoon affected rural sentiment while food inflation put pressure on household budgets.
The cost pressure extended beyond ingredients. Mrs Bectors said the West Asia situation affected vessel availability and raised freight rates during Q2 FY2027, increasing freight and fuel costs within other expenses. Management said those pressures continued into Q3 FY2027, so the 13.1% Q2 EBITDA margin reflected pricing and cost actions rather than a resolution of input-cost exposure.
Got a follow-up? Ask IRIS
Which businesses and products supported Mrs Bectors sales growth?
Mrs Bectors said domestic and export biscuit businesses grew in the low teens in Q2 FY2027, excluding agencies, while bakery recorded high-teens growth. English Oven achieved mid-teen volume growth and high-teen value growth, while institutional bakery grew at mid- to high-teen rates in both volume and value.
Premium products and quick commerce contributed to the growth plan. Mrs Bectors identified shortbread containing 25% butter and no palm oil, along with Zero Maida coconut biscuits, as its two largest contributors on quick-commerce platforms. Management said it planned three further quick-commerce launches and two seasonal Christmas collaborations at a national level with a leading platform.
The company also launched Zero Maida Pav in Mumbai under English Oven, a peanut-butter on-the-go brownie, NaturBaked pre-sliced whole-wheat sourdough and Cremica coconut cream. Management said these products improved portfolio mix, while its Kolkata and Khopoli bakery units were scaling up to strengthen its presence in eastern and western markets.
Distribution expansion was another part of the domestic biscuit strategy. Mrs Bectors had targeted 40,000 new outlets with billing of Rs 245 and above within 400 to 500 kilometres of its Rajpura plant, and said it had added more than 30,000 outlets by H1 FY2027. It also added about 10% to 15% more distributors and said it was close to 345,000 outlets in the defined geography.
What is Mrs Bectors margin outlook for Q3 and Q4 FY2027?
Mrs Bectors expects margins to remain under pressure in the near term because commodity, freight and packaging costs continued into Q3 FY2027. Management said it would take calibrated price actions and continue Project IMPACT interventions, expecting recovery to build progressively as price increases annualise and the cost initiatives mature.
Management described Q3 FY2027 as the period likely to carry the steepest commodity impact and said its aim was to maintain EBITDA margin at the Q2 level of 13.1%. This is a management objective rather than a reported outcome, and management linked it to commodity volatility, price increases and cost-control efforts.
For Q4 FY2027, management said it planned to improve EBITDA margin and try to get closer to 13.5% to 14%. It also said Mrs Bectors should end FY2027 with mid-teen revenue growth, although it acknowledged that commodity conditions had become more difficult than anticipated earlier in the year.
Management said festive demand, innovation and continued brand investment support its second-half outlook. It qualified that view with two risks: a further escalation in the West Asia conflict, which could affect shipping conditions, and a sharper rise in food inflation, which could affect input costs and household spending.
Conclusion
Mrs Bectors paired record Q2 FY2027 revenue of Rs 630.5 crore with EBITDA margin of 13.1%, 50 basis points above the prior-year quarter. However, the results also show the difference between year-on-year margin expansion and sequential pressure: gross margin fell from the first quarter as ingredient inflation and higher freight, fuel and packaging costs were not fully offset by pricing and savings.
The next measure is whether calibrated pricing and Project IMPACT allow Mrs Bectors to maintain its 13.1% EBITDA margin through Q3 FY2027, which management described as the quarter with the steepest commodity impact. Management aims to improve toward 13.5% to 14% in Q4 FY2027 and deliver mid-teen full-year revenue growth, while food inflation and West Asia shipping disruption remain unresolved factors.