










Page Industries Q2 revenue rises 11.5% while PAT gains 4%
Key highlights
- Page Industries' Q2FY27 revenue rose 11.5% year on year to Rs 1,439.6 crore.
- Page Industries' Q2FY27 PAT increased 4.0% year on year to Rs 202.5 crore.
- Page Industries' Q2FY27 EBITDA margin was 20.8%, versus 21.7% in Q2FY26 and 20.3% in Q1FY27.
- Page Industries' H1FY27 revenue grew 9.7% to Rs 2,860.1 crore while PAT declined 0.1% to Rs 395.4 crore.
powered by IRIS
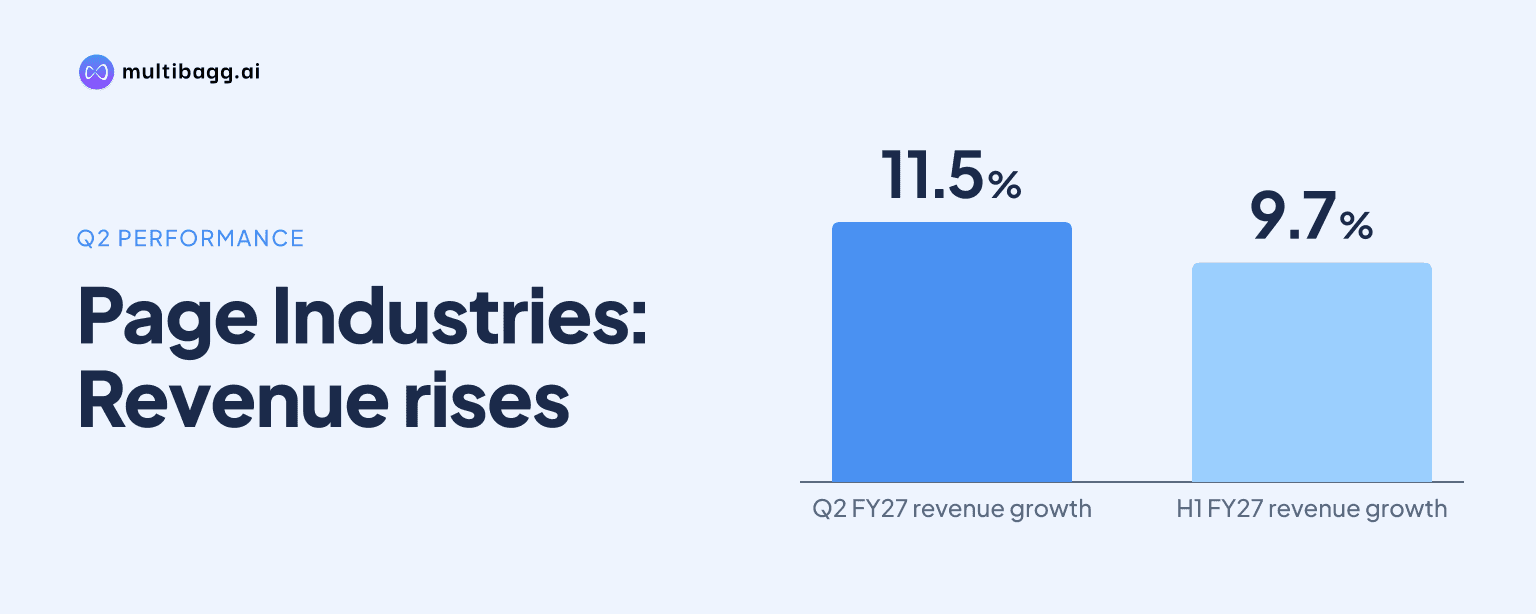
Page Industries Limited reported Q2FY27 revenue of Rs 1,439.6 crore, up 11.5% year on year, while profit after tax rose 4.0% to Rs 202.5 crore as EBITDA margin declined to 20.8% from 21.7%. Management cited expensive, volatile cotton and elevated crude-linked raw-material costs as the constraint on profit conversion.
Know Page Industries inside out
Results, valuation, peers and who's buying, in one view.
How did Page Industries perform in Q2FY27?
Page Industries delivered revenue growth of 11.5% in Q2FY27, reaching Rs 1,439.6 crore from Rs 1,290.9 crore in Q2FY26. Management described the growth as volume-led and said consumer demand remained upbeat through the quarter, extending the momentum from Q1FY27.
Profit growth lagged sales growth in Q2FY27. Earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 7.4% to Rs 300.1 crore; profit before tax, or PBT, increased 3.8% to Rs 271 crore; and profit after tax, or PAT, grew 4.0% to Rs 202.5 crore.
Q2FY27 also improved from Q1FY27, when revenue was Rs 1,420.4 crore and PAT was Rs 192.8 crore. Revenue increased by Rs 19.2 crore sequentially, while PAT rose by Rs 9.7 crore and PAT margin improved to 14.1% from 13.6%.
Why did Page Industries' profit grow more slowly than revenue?
Page Industries' PAT grew more slowly because its Q2FY27 EBITDA margin declined by 90 basis points, or 0.9 percentage points, to 20.8% from 21.7% in Q2FY26. PBT margin fell to 18.8% from 20.2%, while PAT margin declined to 14.1% from 15.1%.
Management said cotton remained expensive and volatile in Q2FY27, while crude-linked raw materials were still well above earlier levels. It said Page Industries absorbed part of this inflation and used a price increase initiated in Q1FY27 to offset some of the pressure.
The quarter nevertheless showed a sequential margin improvement, with EBITDA margin increasing by 50 basis points from 20.3% in Q1FY27 to 20.8% in Q2FY27. Management attributed this support to operational efficiency and procurement strategies, and said the margin remained within its planned range without disclosing that range numerically.
What does Page Industries' first-half performance show?
Page Industries reported H1FY27 revenue of Rs 2,860.1 crore, up 9.7% from Rs 2,607.4 crore in H1FY26, but PAT was almost unchanged at Rs 395.4 crore. PAT was Rs 0.2 crore below the Rs 395.6 crore recorded a year earlier.
The H1FY27 comparison shows that profit conversion remained below the pace of sales growth. EBITDA rose 2.6% to Rs 589.1 crore, PBT declined 0.3% to Rs 529.5 crore, and revenue increased 9.7% over H1FY26.
H1FY27 EBITDA margin was 20.6%, down from 22.0% in H1FY26, while PBT margin declined to 18.5% from 20.4% and PAT margin fell to 13.8% from 15.2%. Q2FY27's 20.8% EBITDA margin was above Q1FY27's 20.3%, but remained below Q2FY26's 21.7%.
Got a follow-up? Ask IRIS
What supported Page Industries' Q2FY27 sales growth?
Page Industries said volume-led growth, upbeat demand and broader channel access supported Q2FY27 revenue of Rs 1,439.6 crore. Its multi-brand trade channel covered 1,14,591 retail outlets across 2,722 cities and towns through 3,934 distributor accounts.
The exclusive-brand-store network comprised 1,626 stores in 608 cities and towns, including 25 exclusive women stores, 32 exclusive juniors stores and 37 factory outlets. Page Industries also reported 921 key department stores across 15 partner chains, with 1,397 points of sale.
Management said e-commerce performed strongly across marketplaces and its own portal, contributing a growing share of sales, but did not quantify the contribution. It also said the Disney and Marvel collections introduced during Q2FY27 were received well, while fulfilment investments in West Bengal were intended to strengthen direct-to-consumer reach.
What is Page Industries planning after Q2FY27?
Page Industries said its S/4HANA rollout was on course for a Q4 go-live. Management also said its Distribution Management System was scaling up as planned, while cyber-security and human-resources transformation programmes were tracking well.
Management said these programmes are intended to make the organisation more agile and resilient and improve service for consumers and retail partners. The company identified the Q3 festive season as the next demand period after reporting upbeat consumer demand in Q2FY27.
Page Industries did not disclose a Q3FY27 or full-year revenue, profit or margin target. Management said it would continue monitoring cotton and crude-linked input costs, while weighing margin protection against consumer value following the Q1FY27 price increase.
Conclusion
Page Industries combined 11.5% Q2FY27 revenue growth with a 4.0% rise in PAT, showing that higher volumes and channel reach supported sales while input costs limited profit growth. The 20.8% EBITDA margin was 50 basis points above Q1FY27 but 90 basis points below Q2FY26, and H1FY27 PAT of Rs 395.4 crore was marginally below the prior-year period.
The next disclosed operational milestone is the planned Q4 go-live of the S/4HANA rollout, while Q3FY27 includes the festive season identified by management. Subsequent disclosures can indicate whether the Q1FY27 price increase, procurement actions and West Bengal fulfilment investment change margins, direct-to-consumer reach and the gap between revenue and PAT growth.