










Page Industries Q2 FY27 Revenue Growth Faces Margin Test
Key highlights
- Page Industries is scheduled to report Q2 FY27 results on November 12, 2026.
- Q1 FY27 revenue rose 7.9% year on year to ₹1,420 crore, while profit after tax fell 4.0% to ₹192.8 crore.
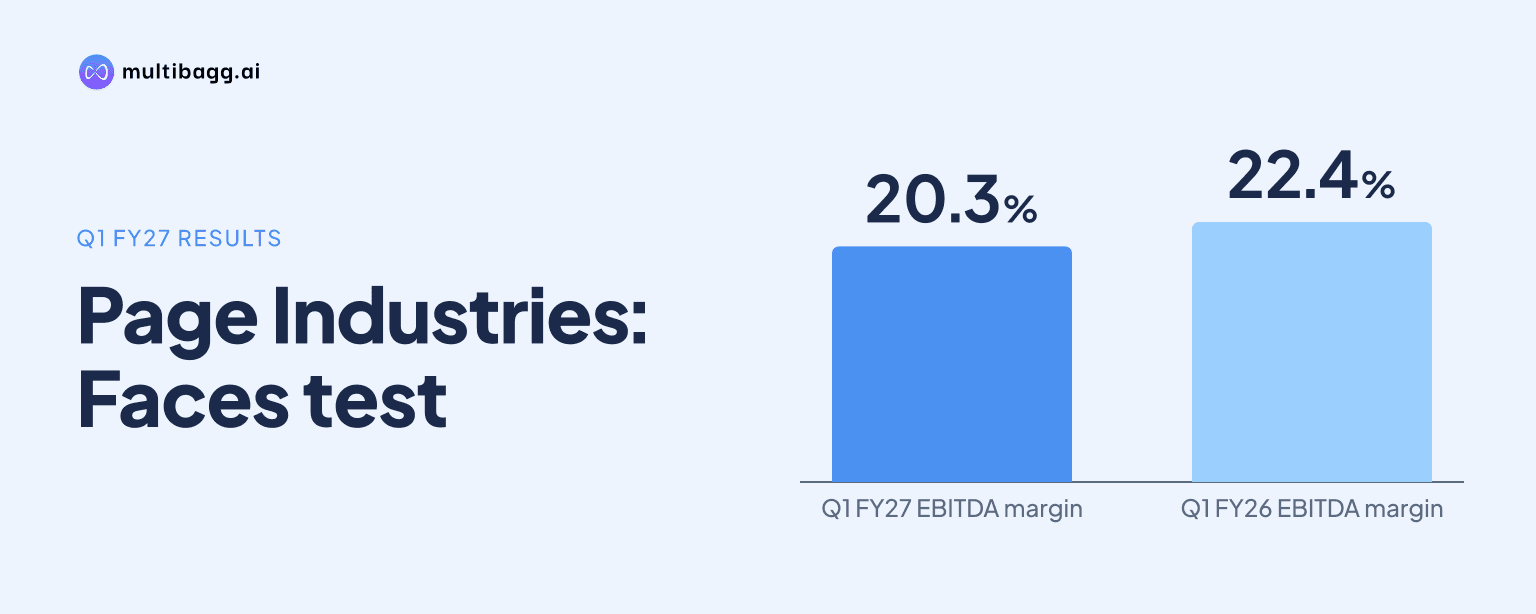
- Q1 FY27 EBITDA margin was 20.3%, versus 22.4% in Q1 FY26.
- Cotton yarn was about ₹400 per kg, roughly 60% above early-2026 levels.
powered by IRIS
Page Industries Limited reports Q2 FY27 results on November 12, 2026, with the key test being whether it can sustain revenue growth while protecting profitability after Q1 revenue rose 7.9% year on year to ₹1,420 crore and profit after tax fell 4.0% to ₹192.8 crore. The September-quarter release will also indicate whether higher volumes and May price increases are offsetting cost pressure.
Know Page Industries inside out
Results, valuation, peers and who's buying, in one view.
When will Page Industries announce its Q2 FY27 results?
Page Industries will place its unaudited Q2 FY27 results, for the quarter ended September 30, 2026, before its board on November 12, 2026. The agenda also includes consideration of a second interim dividend, with November 18 identified as the record date if a dividend is declared.
The scheduled date provides clarity after an earlier preview had stated that a board-meeting intimation had not been filed with the NSE or BSE as of September 15, 2026. The earnings release will be measured against Q2 FY26, when Page Industries reported revenue of ₹1,291 crore and profit after tax of ₹195 crore.
Page Industries is the exclusive licensee for Jockey and Speedo in India. Its quarterly numbers are closely tracked for trends in innerwear demand, product mix, distribution expansion and the ability to pass through input-cost changes.
What does Page Industries' Q1 FY27 performance show?
Page Industries' Q1 FY27 performance showed revenue growth but a decline in profitability, making margin recovery the central issue for Q2. Revenue rose 7.9% year on year to ₹1,420 crore, while profit after tax declined 4.0% year on year to ₹192.8 crore.
The company reported an EBITDA margin of 20.3% in Q1 FY27, compared with 22.4% in Q1 FY26. Employee costs increased 21% year on year to ₹247.58 crore, while quarter-end delivery disruptions left about three days of invoiced billing undelivered. Management expects much of that pending billing to be recognised in Q2.
Volume growth was 5.7% in Q1, below the company's double-digit volume-growth target for FY27. Management nevertheless retained this target and said the next three quarters should record above-average volume growth. The Q2 print will show whether this recovery has begun.
What revenue and profit figures are being watched for Q2 FY27?
Q2 FY27 expectations vary across the available previews, but all focus on whether Page Industries can convert demand growth into year-on-year profit growth. One set of expectations places standalone revenue at about ₹1,410 crore to ₹1,430 crore and profit after tax at ₹185 crore to ₹200 crore.
A separate Zee Business estimate projects revenue of ₹1,477 crore, up 14.4% year on year from the ₹1,291 crore Q2 FY26 base. It projects profit after tax of ₹210 crore, up 7.7%, and EBITDA of ₹306 crore, up 9.4%, but expects EBITDA margin to decline to 20.7% from 21.7% a year earlier.
These are external estimates rather than company guidance. Page Industries has not issued formal quarterly guidance. The broader reference point is FY27 Street consensus of ₹5,820 crore in revenue, representing 10.9% growth, and earnings per share of ₹771.60, implying 7.7% growth.
Demand indicators have been supportive. Apparel retail growth tracked by RAI accelerated from 8% year on year in July to 10% in August, while September GST collections increased 10.1% year on year. A CMAI survey also found that 52% of apparel makers expected stronger festive sales.
Got a follow-up? Ask IRIS
Why are margins central to Page Industries' Q2 FY27 results?
Margins are central because Page Industries retained its FY27 EBITDA-margin guidance of 19% to 21% despite renewed input-cost inflation. Cotton yarn was reported at about ₹400 per kg, around 60% above early-2026 levels, while Brent crude stayed above $100 for most of the quarter.
Synthetic polyester yarn costs also remained elevated, with the wholesale price index for the product up 20.6% year on year in August. These input trends can affect gross margins, especially when price increases are not fully sufficient to absorb cost changes.
Management expects May price increases to flow through more fully in Q2 and support gross-margin stabilisation if input costs remain stable. Investors will therefore assess the balance between price-led value growth and underlying volume growth, rather than revenue alone.
How could the Q2 result affect Page Industries investors and operations?
For investors, a result showing revenue growth in the 8% to 10% range together with year-on-year profit growth would support the view that cost controls and pricing are beginning to work. A repeat of Q1, where revenue increased but profit declined, would keep attention on employee expenses, raw-material costs and the pace of volume recovery.
The operational data will be equally important. Recovery in logistics and manpower issues, sales through exclusive brand outlets, e-commerce penetration and distribution expansion could indicate whether the company is building sustainable scale. The available preview expects volume growth of around 12% and realisation growth of around 5%, but these remain estimates until the company reports.
The sector context is also relevant. Innerwear demand is linked to discretionary consumer spending, festive buying and retail footfall, while Page Industries faces a cost structure exposed to cotton, synthetic yarn and energy-linked inputs. Its ability to maintain the 19% to 21% EBITDA band will be a practical measure of how it is managing these pressures.
Conclusion
Page Industries enters Q2 FY27 with improving demand indicators and a stated commitment to restore double-digit volume growth, but its Q1 performance established that revenue growth alone may not be enough. The September-quarter result will be assessed against a ₹1,291 crore revenue and ₹195 crore profit base from Q2 FY26, with margins, employee costs and volume growth carrying significant weight.
Investors should watch the reported volume growth, the EBITDA margin against the 19% to 21% FY27 guidance band, and management's comments on cotton-yarn costs and the May price increase. The board's decision on a possible second interim dividend and the November 18 record date, if declared, are also scheduled matters to monitor.