










PNC Infratech keeps FY27 revenue and 12% margin targets
Key highlights
- PNC Infratech retained FY27 revenue guidance of Rs 6,000 crore after reporting Rs 2,664 crore in H1.
- PNC Infratech set its 12% EBITDA-margin target on about Rs 5,800 crore of revenue excluding the Rs 217 crore arbitration award.
- PNC Infratech reported an Rs 18,000 crore unexecuted order book, excluding the cancelled BESS project.
- PNC Infratech submitted 17 bids worth Rs 16,600 crore and identified 80 opportunities worth about Rs 1.8 lakh crore.
powered by IRIS
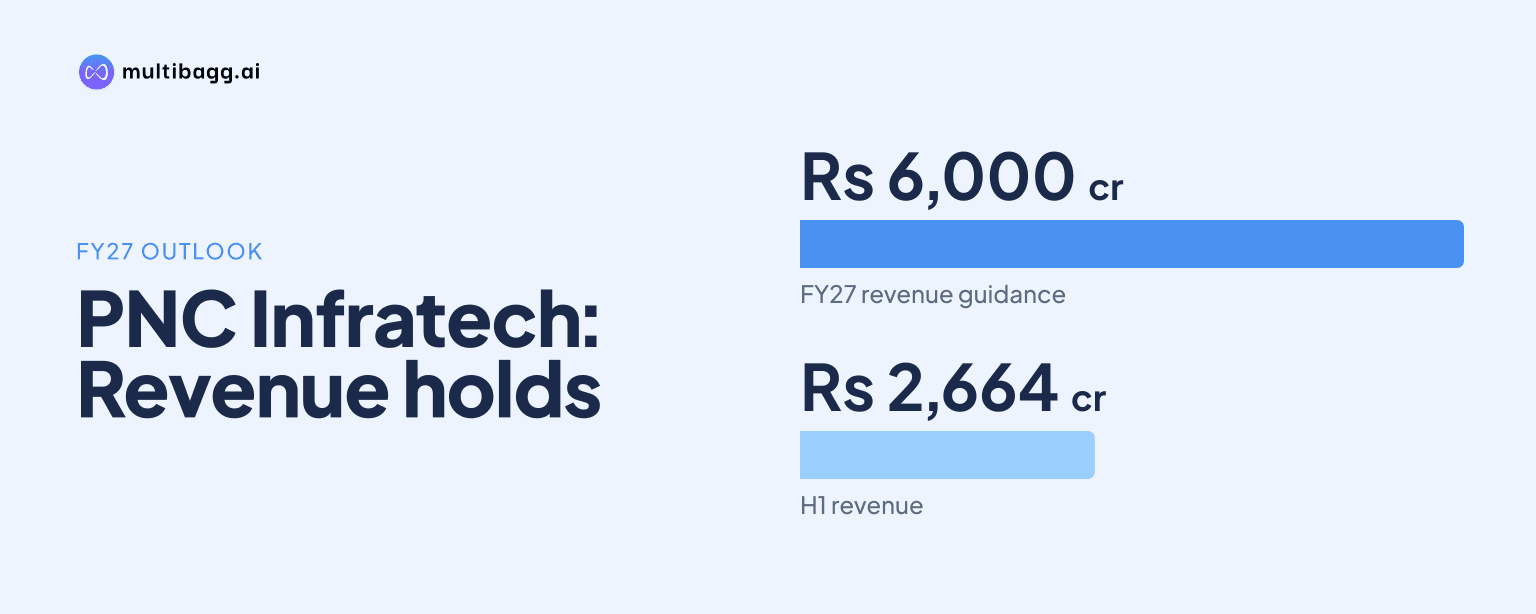
PNC Infratech Limited retained its FY27 guidance of Rs 6,000 crore in revenue and a 12% earnings before interest, taxes, depreciation and amortisation (EBITDA) margin, despite reporting Rs 2,664 crore in H1 revenue. Management said Rs 3,336 crore remains to be earned in H2, supported by an Rs 18,000 crore unexecuted order book and an execution ramp-up after the monsoon.
Know PNC Infratech inside out
Results, valuation, peers and who's buying, in one view.
Can PNC Infratech meet its FY27 revenue guidance?
Yes, PNC Infratech said it can meet its Rs 6,000 crore FY27 revenue target because it expects execution to rise in H2 after a monsoon-affected first half. H1 revenue was Rs 2,664 crore, including an Rs 217 crore arbitration award, leaving Rs 3,336 crore to be recognised in the final six months of FY27.
Management said the first half of a financial year is usually slower for construction because of monsoon conditions. It expects five major hybrid annuity model (HAM) road projects and two Maharashtra State Road Development Corporation (MSRDC) highway projects to move into fuller execution, while recently awarded work is expected to start during Q3 and Q4.
PNC Infratech said its Rs 18,000 crore unexecuted order book should support more than Rs 3,000 crore of turnover in H2. Management added that even without new awards, it expects to hold about Rs 15,000 crore of unexecuted orders at the end of FY27, compared with the Rs 18,000 crore balance cited during the call.
What does PNC Infratech’s 12% EBITDA margin target cover?
PNC Infratech said its 12% EBITDA-margin guidance applies to about Rs 5,800 crore of FY27 revenue excluding the Rs 217 crore arbitration claim. The company separately said its Rs 6,000 crore full-year revenue guidance includes that arbitration award, creating a different basis for revenue and margin guidance.
The distinction is material because the Rs 2,664 crore H1 revenue figure includes the Rs 217 crore award. An analyst said that excluding the claim, first-half margin appeared to be below 12%, but management did not provide a separate reported H1 EBITDA margin in response. It said a higher H2 revenue run rate should improve the absorption of fixed overheads, which would remain broadly unchanged.
Management also said its 12% margin target takes account of the partial impact of bitumen prices. Its explanation for retaining the target rests on the Rs 3,336 crore of revenue still planned for H2 and the associated fixed-cost absorption, rather than on a disclosed reduction in material costs or overheads.
Got a follow-up? Ask IRIS
What supports PNC Infratech’s H2 execution plan?
PNC Infratech’s main support for H2 execution is its Rs 18,000 crore unexecuted order book, alongside five active HAM projects and two MSRDC highway projects. Management said these projects are moving into full swing, and it expects other recently awarded projects to start in Q3 and Q4.
The Rs 18,000 crore order book excludes the cancelled battery energy storage system (BESS) project, which management said was never included in that backlog. The BESS letter of award was cancelled after NHPC could not complete the required power sale agreement and power purchase agreement within the stipulated period, despite an extension from August 31 to September 30.
PNC Infratech said its bid security for the BESS project was refunded after the cancellation. Roads remain the main execution segment, accounting for 63% of the order book, while management said it sees more competition in engineering, procurement and construction (EPC) and smaller projects than in larger fund-based projects such as HAM.
Management’s assessment of competition is linked to its focus on larger projects requiring investment. It said this segment could face less intense competition than smaller EPC contracts, although the call did not provide win-rate data or a quantified comparison of bid intensity across project categories.
What new orders could affect PNC Infratech’s outlook?
PNC Infratech retained FY27 order-inflow guidance of Rs 12,000 crore to Rs 15,000 crore after recording Rs 4,260 crore of inflows. Management said it had submitted 17 bids worth Rs 16,600 crore, whose price bids had not yet been opened, and had identified 80 projects worth about Rs 1.8 lakh crore for bids through the end of January.
The identified pipeline comprises 35 EPC projects, 25 HAM projects and 20 build-operate-transfer toll and tariff-based competitive bidding (TBCB) projects. Management said projects from the National Highways Authority of India, Ministry of Road Transport and Highways, and National Highways and Infrastructure Development Corporation account for 60% to 65% of that pipeline, compared with 35% to 40% from railways and other clients.
PNC Infratech is not including international orders in its FY27 inflow guidance. Management said it is initially pursuing non-fund-based EPC highway projects in Kazakhstan, Georgia, Uzbekistan and the United Arab Emirates, where capital requirements would mainly be working capital rather than project equity.
Two new National Highways Authority of India HAM projects are expected to receive appointed dates in Q4, subject to conditions including 80% land availability. Management said around 90% of right of way under the relevant 3G process had been achieved, while 3H land-payment disbursements were under way; it expects 35% to 40% project progress in FY28 and about 60% in FY29, with no significant FY27 work.
Conclusion
PNC Infratech has kept its FY27 revenue and margin guidance unchanged because management expects a monsoon-weighted H2 execution increase to deliver the Rs 3,336 crore still needed after H1. The Rs 18,000 crore unexecuted order book and active HAM and MSRDC projects underpin that view, while the 12% EBITDA target excludes the Rs 217 crore arbitration award.
The next points to watch are the planned start of newly awarded projects in Q3 and Q4, the expected Q4 appointed dates for two new HAM projects and the opening of price bids for 17 submitted bids worth Rs 16,600 crore. Management also plans to bid for identified opportunities worth about Rs 1.8 lakh crore through the end of January while targeting Rs 12,000 crore to Rs 15,000 crore in FY27 domestic order inflows.