










Popular Vehicles and Services Limited Reports 40% Q2 Growth
Key highlights
- Popular Vehicles reported approximately 40% year-on-year revenue growth and 51% new vehicle volume growth in Q2 FY27.
- H1 FY27 revenue from operations grew approximately 46% year-on-year, including 29% organic growth.
- New vehicle inventory fell to about 41 days from 44 days a year earlier, although debt rose sequentially due to pre-price-hike inventory build-up.
- Popular Vehicles guided for FY27 revenue of ₹8,200 crore to ₹8,300 crore, implying 20% to 25% growth.
powered by IRIS
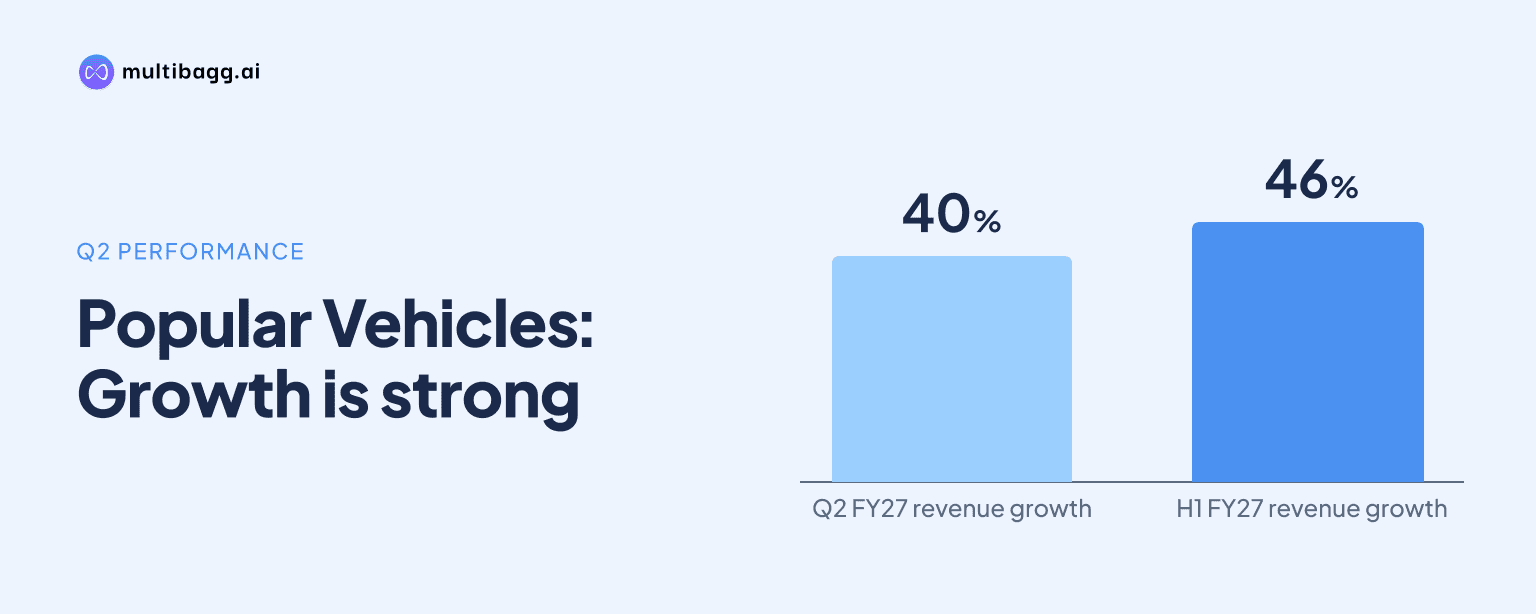
Popular Vehicles and Services Limited reported approximately 40% year-on-year growth in revenue from operations for Q2 FY27, while new vehicle sales volumes rose 51%, ahead of its 12 November 2026 earnings call. The business update also showed 46% revenue growth for the first half, supported by organic expansion and acquired network integration.
Know Popular Vehicles & Services inside out
Results, valuation, peers and who's buying, in one view.
What did Popular Vehicles report for Q2 FY27?
Popular Vehicles reported approximately 40% year-on-year growth in consolidated revenue from operations in the quarter ended 30 September 2026, with organic revenue growth of 26%. The company said new vehicle sales volumes increased 51% year-on-year, while organic volume growth was 28%.
The reported growth rates reflect both underlying operations and expansion through acquisitions. Popular Vehicles noted that its calculations adjust for Honda and Piaggio volumes and revenue, which were included only until August 2025, and for Audi, which was added from the fourth quarter of FY26. These adjustments are relevant when comparing reported and organic growth rates.
For H1 FY27, consolidated revenue from operations increased approximately 46% year-on-year, including 29% organic growth. New vehicle volumes grew 67% on a reported basis and 41% organically over the six-month period. The figures indicate that the first-half increase was stronger than the quarterly growth rate on both reported and organic measures.
The company had earlier reported revenue of ₹1,890 crore for the quarter ended 30 June 2026, up 44.1% from ₹1,311 crore a year earlier. It posted a profit of ₹1.37 crore for that quarter, compared with a loss of ₹8.76 crore in the prior-year period. Popular Vehicles' separate stock report described Q1 FY27 revenue as ₹1,903.1 crore and profit after tax as ₹1.4 crore.
Which business segments supported Popular Vehicles' growth?
Passenger vehicles excluding luxury models were the largest reported growth contributor, with revenue up 46% year-on-year in Q2 FY27 and 57% in H1 FY27. Organic growth in this segment was 31% for the quarter and 38% for the first half.
Luxury passenger vehicle revenue rose 53% in Q2 FY27 and 48% in H1 FY27. Organic growth was lower at 19% in the quarter and 20% in the half year, showing that network additions and other non-organic factors contributed to the overall reported increase.
Commercial vehicle revenue increased 28% year-on-year in the quarter and 32% during the first half. The respective organic growth rates were 23% and 22%. The EV and spare-parts distribution division reported 43% growth in both Q2 and H1, with 16% organic growth in each period.
Popular Vehicles also said its Yanik business-to-business automotive spare-parts marketplace had begun full-scale operations with more than 13,000 verified parts. It added a Maruti Suzuki service centre at Karukachal and a Tata Motors commercial vehicle service centre at Kayamkulam in Kerala during the period.
Why did Popular Vehicles' debt increase despite lower inventory days?
Popular Vehicles said its debt increased sequentially mainly because it built inventory before original equipment manufacturer price increases that took effect on 1 October 2026. This inventory accumulation was a working-capital decision linked to anticipated price changes rather than a separately disclosed capital-expenditure programme.
At the same time, new vehicle inventory stood at about 41 days, compared with 44 days a year earlier. The reduction suggests that inventory turnover improved year-on-year despite the pre-price-hike stock build-up. The company did not disclose quarterly capital-spending figures for India.
For investors, the difference between reported and organic growth remains important. In Q2 FY27, reported revenue growth of 40% exceeded organic growth of 26%, and reported volume growth of 51% exceeded organic volume growth of 28%. The gap reflects the contribution of acquired businesses and network expansion alongside growth in existing operations.
Service operations recorded positive year-on-year volume growth through existing centres and newly integrated locations. Popular Vehicles said operating momentum could improve as acquired service points complete integration, but it did not provide a quantified forecast for service revenue or profitability.
Got a follow-up? Ask IRIS
What governance and reporting events has Popular Vehicles disclosed?
Popular Vehicles disclosed that R.G.N. Price & Co., statutory auditor of material subsidiary Popular Mega Motors (India) Private Limited, resigned effective 3 November 2026. The stated reason was auditor rotation at the holding company to align audit processes.
The disclosure concerns the statutory audit of a material subsidiary rather than a revision to the group's operating update. No financial restatement, accounting irregularity, or additional issue was stated in the information provided. Auditor changes in material subsidiaries are relevant to shareholders because subsidiary financial reporting is included in consolidated accounts.
The board was scheduled to meet on 11 November 2026 to consider and approve unaudited standalone and consolidated financial results for Q2 and H1 ended 30 September 2026. The meeting will provide the formal financial-result context for the earlier operational business update.
Popular Mega Motors also received Great Place to Work certification as a Great Workplace for the second consecutive year. The certification is valid from October 2026 to October 2027 and carries a Trust Index score of 95%, according to the company disclosure.
When will Popular Vehicles discuss its Q2 FY27 results?
Popular Vehicles will hold an earnings conference call at 8:45 AM IST on 12 November 2026 to discuss Q2 FY27 results and half-year performance. Shareholders and other market participants can use the call to assess management's explanation of revenue growth, volumes, working capital and segment-level performance.
The call follows the 11 November board meeting for unaudited Q2 and H1 results. The sequence means investors will have the approved results before management discusses operational outcomes and financial performance. Popular Vehicles has not provided further details in the supplied information on the call's agenda or participants.
Management has guided for FY27 revenue of ₹8,200 crore to ₹8,300 crore, implying growth of 20% to 25%. This target provides a benchmark against which investors can evaluate the first-half operating update once the company releases its unaudited financial statements.
Conclusion
Popular Vehicles' Q2 FY27 update shows reported revenue growth of approximately 40% and new vehicle volume growth of 51%, while organic growth was 26% and 28%, respectively. Passenger vehicles, luxury vehicles, commercial vehicles and EV and spare-parts distribution all recorded year-on-year growth, with acquisitions and network additions contributing to the reported expansion.
The next disclosures to watch are the board-approved unaudited Q2 and H1 FY27 results on 11 November and management's earnings call on 12 November. Investors will be able to compare the formal financial numbers, debt and inventory position, and management commentary with the FY27 revenue guidance of ₹8,200 crore to ₹8,300 crore.