










Power Mech Q2 revenue rose 30% while EBITDA margin declined
Key highlights
- Power Mech reported Q2 FY27 revenue of Rs 1,609 crore, up 30% from Rs 1,238 crore in Q2 FY26.
- Power Mech’s Q2 FY27 EBITDA was Rs 187 crore, while EBITDA margin was 11.55% versus 12.65% a year earlier.
- Infrastructure Construction generated Rs 582 crore of Q2 FY27 revenue, followed by Industrial Services at Rs 570 crore.
- Power Mech’s FY27 year-to-date backlog, including MDO, stood at Rs 56,729 crore, of which MDO represented Rs 39,243 crore.
powered by IRIS
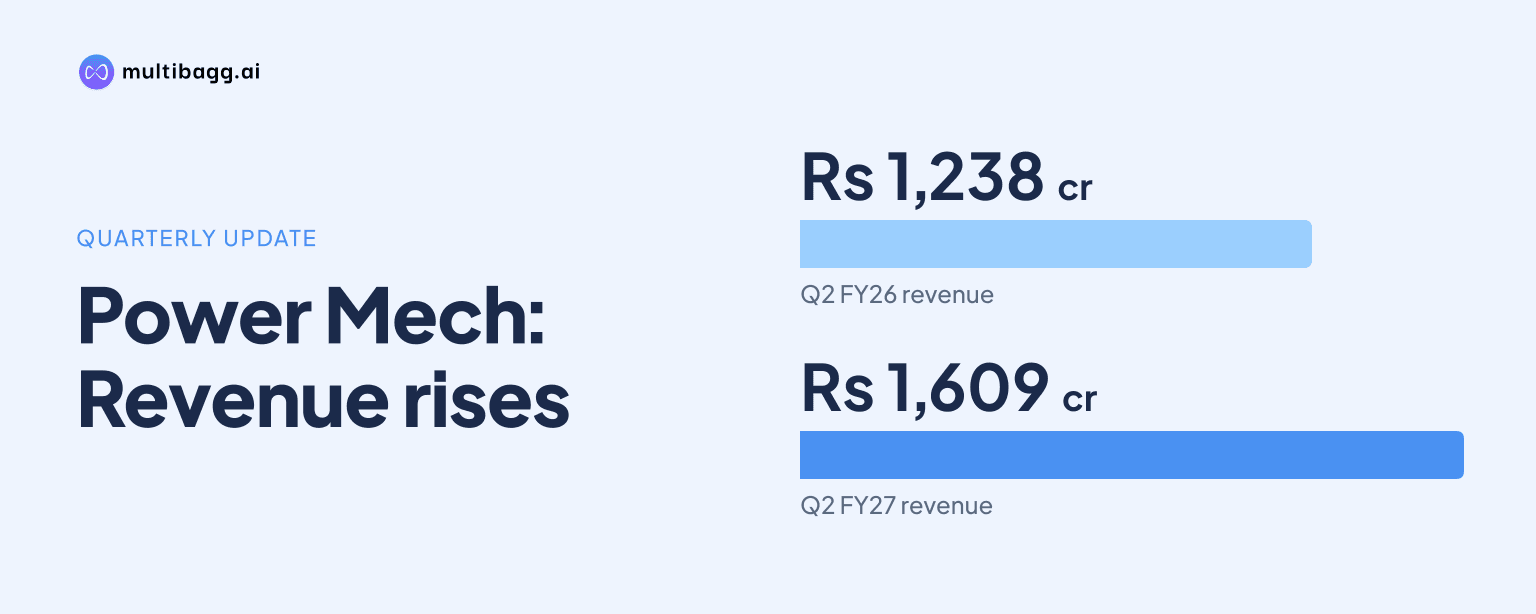
Power Mech Projects Limited reported Q2 FY27 revenue of Rs 1,609 crore, up 30% year on year from Rs 1,238 crore, while earnings before interest, tax, depreciation and amortisation (EBITDA) margin declined to 11.55% from 12.65%. EBITDA nevertheless increased 18.4% to Rs 187 crore as execution rose across key business verticals.
Know Power Mech Projects inside out
Results, valuation, peers and who's buying, in one view.
How did Power Mech’s Q2 FY27 earnings change?
Power Mech recorded Rs 1,609 crore of Q2 FY27 revenue, Rs 371 crore above Q2 FY26 revenue of Rs 1,238 crore, but Rs 15 crore below Q1 FY27 revenue of Rs 1,624 crore. Management attributed the year-on-year growth to higher execution in Infrastructure Construction, Industrial Construction, Industrial Services and international projects.
EBITDA was Rs 187 crore in Q2 FY27, compared with Rs 158 crore a year earlier and Rs 176 crore in Q1 FY27. The Rs 29 crore year-on-year EBITDA increase was lower than the Rs 371 crore revenue increase, while the Rs 11 crore sequential EBITDA rise followed management’s cited improvement in operating costs.
For H1 FY27, Power Mech reported revenue of Rs 3,233 crore, up 28% year on year, and EBITDA of Rs 363 crore, up 6.8%. The H1 EBITDA margin was 11.17%, below the Q2 FY27 margin of 11.55%, while Q2 accounted for Rs 1,609 crore of the first-half revenue total.
Which segments produced Power Mech’s Q2 FY27 revenue?
Infrastructure Construction was Power Mech’s largest Q2 FY27 revenue segment at Rs 582 crore, representing 36.17% of revenue, followed by Industrial Services at Rs 570 crore, or 35.43%. Infrastructure Construction rose Rs 250 crore from Rs 332 crore in Q2 FY26 but declined Rs 214 crore from Rs 796 crore in Q1 FY27.
Industrial Services increased Rs 130 crore year on year from Rs 440 crore and Rs 139 crore sequentially from Rs 431 crore. Management said operations and maintenance, or O&M, growth was gaining pace with new order inflows during FY27, and the segment’s share of quarterly revenue was close to Infrastructure Construction’s 36.17%.
Industrial Construction contributed Rs 372 crore in Q2 FY27, compared with Rs 435 crore in Q2 FY26 and Rs 313 crore in Q1 FY27. Mining development and operations, or MDO, generated Rs 85 crore, up from Rs 31 crore a year earlier and Rs 84 crore sequentially; its revenue share rose to 5.28% from 2.50% as production ramped up at the KBP mine.
Why was Power Mech’s EBITDA margin below last year’s level?
Power Mech’s EBITDA margin was 11.55% in Q2 FY27, down 1.10 percentage points from 12.65% in Q2 FY26, despite EBITDA rising to Rs 187 crore from Rs 158 crore. The presentation does not provide a detailed year-on-year cost bridge for the lower margin, but it reports the margin outcome alongside the 30% revenue increase.
The Q2 FY27 margin was 0.77 percentage points above Q1 FY27’s 10.78%. Management said the sequential improvement reflected sustained execution across core segments and the ramp-up of operations on newly secured orders, while the presentation separately said the Rs 11 crore quarter-on-quarter EBITDA increase resulted from better operating costs.
Profit after tax, or PAT, was Rs 88 crore in Q2 FY27, up Rs 10 crore from Rs 78 crore in Q2 FY26 but down Rs 1 crore from Rs 89 crore in Q1 FY27. PAT margin declined to 5.46% from 6.31% a year earlier and 5.50% sequentially; management attributed the Rs 2 crore sequential PAT reduction to higher finance and depreciation costs.
Got a follow-up? Ask IRIS
What does Power Mech’s order position show?
Power Mech reported FY27 year-to-date order inflows of Rs 4,801 crore, which it said was 40% of its target. Industrial Services accounted for Rs 3,718 crore of that amount and Infrastructure Construction contributed Rs 1,083 crore, while Q2 FY27 alone delivered Rs 1,890 crore of inflows.
Management disclosed a further Rs 1,046 crore of order inflows in Q3 FY27 to date. The awards it highlighted included five-year comprehensive O&M contracts for Vedanta’s 2 x 600 megawatt Athena plant and Adani’s 2 x 600 megawatt Moxie Power Thermal Plant at Tuticorin, plus a three-year O&M contract at TGGENCO’s Yadadri Thermal Power Station.
The FY27 year-to-date order backlog, including MDO, was Rs 56,729 crore, compared with Rs 55,151 crore at FY26 end. MDO represented Rs 39,243 crore of the disclosed backlog, ahead of Infrastructure Construction at Rs 7,903 crore, Industrial Services at Rs 5,689 crore and Industrial Construction at Rs 3,894 crore.
What is management’s plan after Q2 FY27?
Power Mech management said it is focused on operational excellence, profitability improvement and execution of the Rs 56,729 crore backlog across power, infrastructure, O&M and mining. It identified balance-of-plant engineering, procurement and construction packages, domestic and international power O&M, civil infrastructure and urban mobility as areas where it intends to strengthen its presence.
Management expects margins to trend upward in coming quarters as MDO revenue scales up, an expectation rather than a Q2 FY27 result. The presentation describes Rs 39,243 crore of MDO contracts as operationalised and gives MDO a peak-rated mining capacity of 9 million metric tonnes annually, but the business contributed Rs 85 crore, or 5.28%, of Q2 FY27 revenue.
Conclusion
Power Mech combined 30% year-on-year Q2 FY27 revenue growth with an 18.4% rise in EBITDA, led by Rs 582 crore of Infrastructure Construction revenue and Rs 570 crore from Industrial Services. However, EBITDA margin of 11.55% remained below the 12.65% recorded in Q2 FY26, and PAT margin fell to 5.46%.
The next reported progress point is whether MDO revenue rises beyond the Q2 FY27 level of Rs 85 crore and supports the margin uptrend management expects. Investors can also watch execution of the Rs 4,801 crore of FY27 year-to-date order inflows and conversion of the Rs 56,729 crore backlog, including Rs 39,243 crore related to MDO.