










Prataap Snacks Revenue Rises 26% as Q2 FY27 Loss Returns
Key highlights
- Prataap Snacks reported Q2 FY27 revenue from operations of ₹541 crore, up 26% year on year.
- Q2 FY27 EBITDA fell 43.7% year on year to ₹12.9 crore, with a 2.4% margin.
- Prataap Snacks reported a Q2 FY27 net loss of ₹2.5 crore versus a ₹4.64 crore profit a year earlier.
- First-half FY27 revenue was ₹1,031 crore, up 23% year on year.
powered by IRIS
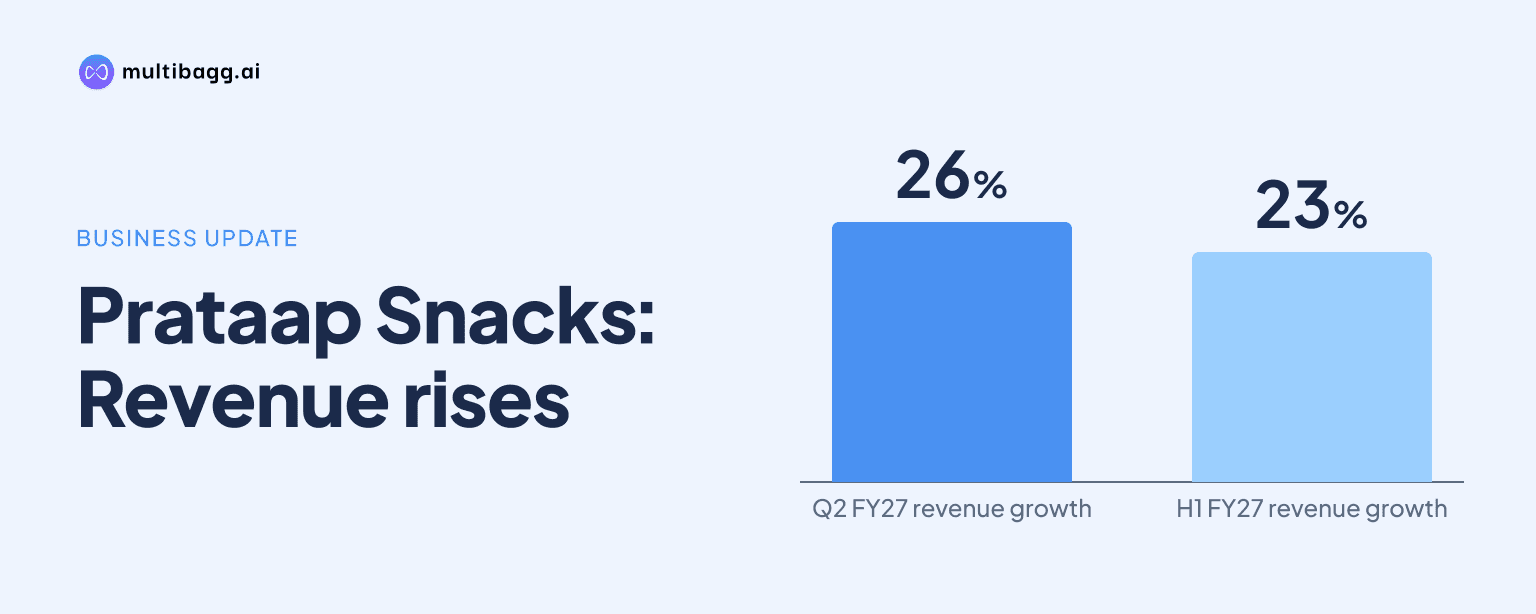
Prataap Snacks Limited reported record Q2 FY27 revenue from operations of ₹541 crore, up 26% year on year, but profitability weakened as the company recorded a net loss of ₹2.5 crore and EBITDA fell to ₹12.9 crore. The results underline strong demand and distribution growth alongside significant pressure from input and operating costs.
Know Prataap Snacks inside out
Results, valuation, peers and who's buying, in one view.
What did Prataap Snacks report for Q2 FY27?
Prataap Snacks reported its highest quarterly revenue from operations, at ₹541 crore in the quarter ended September 30, 2026. The figure was 26% higher than the year-ago quarter and 10% above the preceding quarter, according to the company's Q2 FY27 investor presentation. Revenue growth took the company past the ₹500 crore quarterly milestone for the first time.
The separately reported quarterly-results data put standalone revenue at ₹543.93 crore, compared with ₹431.89 crore in Q2 FY26. The difference reflects the presentation of revenue from operations versus standalone revenue in the reported material. Both disclosures show year-on-year growth of about 26%.
For the first half of FY27, revenue was reported at ₹1,031 crore, up 23% year on year. Management indicated that growth was broad-based, with namkeen and potato chips contributing alongside new products and wider distribution.
Why did profitability weaken despite higher revenue?
Profitability weakened because key input and distribution costs rose sharply during the quarter. Management identified palm oil, potatoes, packaging, fuel and logistics as areas that materially pressured margins. Q2 gross margin declined to 25.5% from 29.8% a year earlier.
EBITDA declined 43.7% year on year to ₹12.9 crore from ₹22.9 crore, resulting in an EBITDA margin of 2.4%. The combination of a lower gross margin and higher operating cost burden meant that topline growth did not translate into higher operating profit.
The company reported a net loss of ₹2.5 crore for the quarter, compared with a net profit of ₹4.64 crore in Q2 FY26. The reported loss followed the decline in operating profit and represents a reversal from the profit recorded in the corresponding period last year.
How is Prataap Snacks building its revenue base?
Prataap Snacks is expanding its revenue base through growth in namkeen, potato chips, new products and distribution. Management said namkeen has increased from roughly 15%-16% of revenue two years earlier to about 25%, making it a more material contributor to the sales mix.
The company also highlighted emerging channels as an area of focus. Its investor presentation set a target for these channels to contribute more than 5% of revenue within three years. The disclosed target provides a direction for channel expansion, though the presentation did not specify a current emerging-channel revenue share.
The 10% sequential increase in Q2 revenue indicates that sales momentum continued from Q1 FY27. However, the company said margin recovery would depend on pricing and grammage actions as well as structural initiatives, which it expects to take time to deliver.
Got a follow-up? Ask IRIS
What does the quarter mean for investors and operations?
The quarter shows that Prataap Snacks has maintained revenue momentum despite a difficult cost environment. The move beyond ₹500 crore in quarterly revenue and the 23% first-half growth are relevant operating indicators, particularly because growth was reported across more than one product category.
But the margin decline is equally important for investors. Revenue rose substantially while EBITDA fell and the company returned to a quarterly loss, showing the effect of raw-material, packaging, fuel and logistics inflation on earnings. The available disclosures do not provide a timetable for margin normalisation.
Prataap Snacks held its Q2 and H1 FY27 earnings conference call on November 3, 2026. The company has made the audio recording available on its website, allowing shareholders to review management's commentary on the unaudited quarterly and half-year results.
How should the Q2 FY27 numbers be assessed in context?
The results place growth and profitability on different trajectories. Revenue increased by roughly one-quarter year on year, while gross margin contracted by 4.3 percentage points and EBITDA declined by 43.7%. This gap is central to assessing the quarter because cost inflation absorbed much of the benefit of higher sales.
Management's comments suggest that pricing, grammage and structural measures are intended to address the cost pressure. The company did not disclose a quantified near-term margin target in the supplied material. Its stated three-year emerging-channel objective is a longer-term commercial target rather than an immediate earnings forecast.
Conclusion
Prataap Snacks delivered record quarterly revenue of ₹541 crore in Q2 FY27, supported by growth in namkeen, potato chips, product additions and distribution. Yet higher costs reduced gross margin, cut EBITDA to ₹12.9 crore and resulted in a ₹2.5 crore net loss, making profitability the key issue alongside sales growth.
The next disclosures will be relevant for evidence of the price, grammage and structural actions referenced by management, and for progress toward the target of emerging channels contributing more than 5% of revenue within three years. Investors can also review the November 3 earnings-call recording for management's discussion of the unaudited results.