










PSP Projects Limited Reports 58% Q2 Revenue Growth to ₹1,113 Crore
Key highlights
- PSP Projects reported record Q2 FY27 revenue of ₹1,113 crore, up 58% year-on-year.
- Q2 FY27 profit after tax rose 87% year-on-year to ₹30 crore.
- H1 FY27 revenue increased 61% year-on-year to ₹1,957 crore.
- The order book stood at ₹12,872 crore as of September 30, 2026, up 30% year-on-year.
powered by IRIS
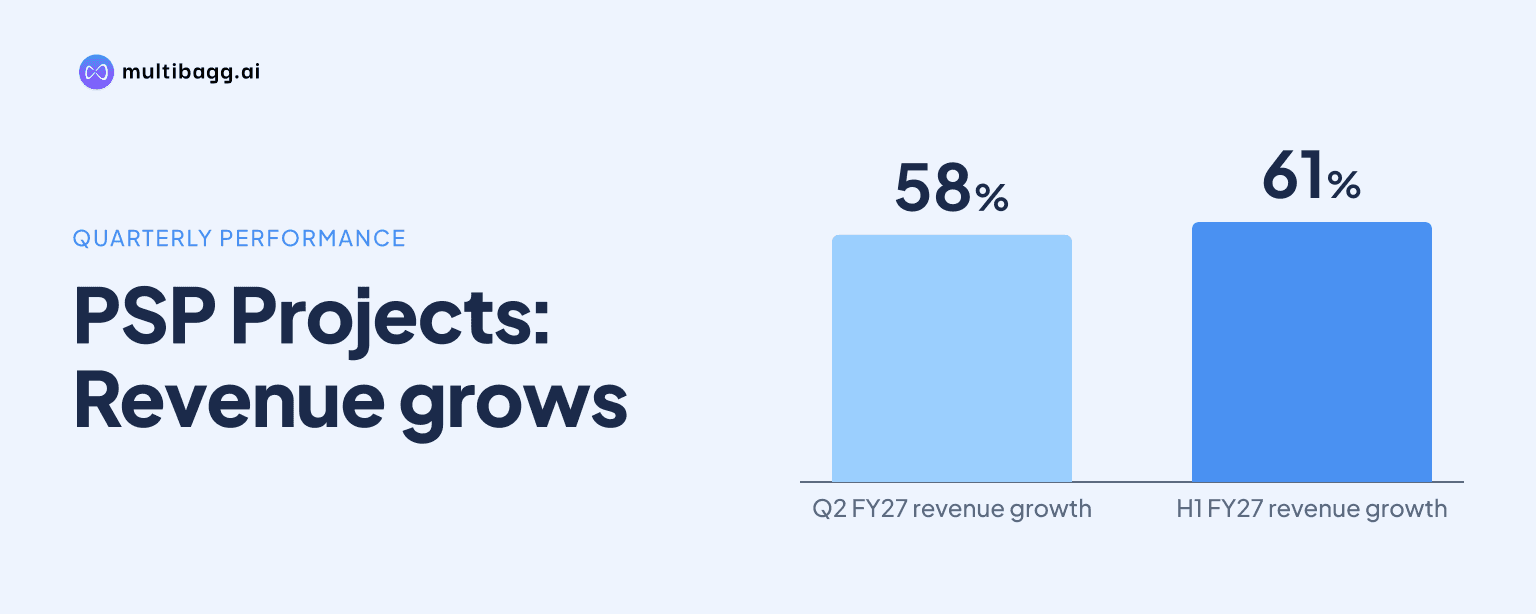
PSP Projects Limited reported record Q2 FY27 revenue of ₹1,113 crore, a 58% year-on-year increase, supported by stronger project execution and better labour availability. The company also reported an order book of ₹12,872 crore as of September 30, 2026, providing visibility over future project execution.
Know PSP Projects inside out
Results, valuation, peers and who's buying, in one view.
What did PSP Projects report for Q2 FY27?
PSP Projects reported consolidated revenue from operations of ₹1,113 crore for the quarter ended September 30, 2026, compared with ₹703 crore in Q2 FY26. The 58% year-on-year rise marked the company’s highest quarterly revenue, according to Chief Executive Officer Pooja Patel.
EBITDA rose 38% year-on-year to ₹69 crore from ₹50 crore. Profit after tax increased 87% to ₹30 crore from ₹16 crore in the corresponding quarter of the previous financial year. The quarterly EBITDA margin, however, was 6.21%, compared with 7.10% in Q2 FY26.
Management attributed the higher revenue to healthy execution across the project portfolio and improved availability of labour and other execution resources. The company discussed the unaudited standalone and consolidated results for the quarter and half year during its November 2 earnings conference call.
The financial performance showed that profit growth exceeded revenue growth during the quarter, even as the operating margin was lower on a year-on-year basis. The results also followed a period of higher execution across the company’s construction contracts.
How did PSP Projects perform in the first half of FY27?
PSP Projects reported H1 FY27 revenue of ₹1,957 crore, up 61% year-on-year, while EBITDA rose 66% to ₹124 crore and profit after tax increased 193% to ₹48 crore. Management described the first-half revenue as the company’s highest half-year revenue.
The H1 EBITDA margin was 6.30%, compared with 6.12% in H1 FY26. This 18-basis-point improvement indicates a modest expansion in first-half operating profitability despite the lower quarterly margin reported in Q2.
The company’s half-year figures reflect the combined impact of the Q2 execution increase and the performance in the first quarter. Higher project activity and resource availability were the operational factors identified by management in its comments on the results.
PSP Projects has maintained FY27 revenue growth guidance of 25% to 30%. It has also indicated that margins are expected to improve in the second half as projects advance towards finishing work. This is management guidance rather than a reported financial outcome.
Got a follow-up? Ask IRIS
What does the ₹12,872 crore order book indicate?
PSP Projects had an outstanding order book of ₹12,872 crore as of September 30, 2026, up 30% year-on-year. The order book represents contracted work yet to be executed and is a key measure of revenue visibility for an engineering and construction company.
Within-group projects accounted for about 72% of the order book, or ₹9,229 crore. External projects represented the remaining 28%. This composition indicates that a substantial share of the pending work was sourced from within the group, while external contracts formed a smaller but material component.
During H1 FY27, PSP Projects secured order inflow of about ₹1,305 crore, including ₹675 crore during Q2. These additions contributed to the backlog while the company continued to execute existing contracts at a higher pace.
Why do execution and margins matter for investors?
Execution and margins matter because revenue in construction contracting depends on the pace at which awarded projects are completed. PSP Projects linked its Q2 revenue growth to healthy execution and improved labour availability, making operational capacity central to the reported increase in revenue.
The difference between revenue growth and EBITDA growth is also relevant. Revenue expanded 58% in Q2, while EBITDA rose 38%, and the EBITDA margin declined to 6.21% from 7.10%. Investors will therefore need to track whether the anticipated H2 margin improvement is reflected in subsequent reported results.
The ₹12,872 crore order book gives PSP Projects a large base of work to execute over multiple years. However, the conversion of this order book into revenue depends on project progress and execution conditions. The company has not provided a specific schedule for revenue recognition from the backlog in the disclosed comments.
For customers and project stakeholders, better availability of labour and execution resources may support project delivery activity. For investors, the key reported measures are order inflows, backlog composition, revenue conversion, operating margins and profitability.
Conclusion
PSP Projects delivered its highest reported quarterly and half-year revenue in Q2 FY27 and H1 FY27, respectively. Q2 revenue rose 58% to ₹1,113 crore, profit after tax rose 87% to ₹30 crore, and the order book increased 30% year-on-year to ₹12,872 crore as of September 30, 2026.
The next areas to watch are the company’s stated FY27 revenue growth guidance of 25% to 30%, progress of projects towards finishing work, and whether the expected H2 margin improvement becomes visible in reported EBITDA margins. Order inflows and the mix between within-group and external projects will also remain relevant to the pace of future execution.